


Perimeter Group stock reacts to sharp earnings turnaround
Perimeter Group (PRM) drew fresh attention after its 5 November third quarter report, as the business moved from a net loss a year ago to a substantial profit on higher sales.
Perimeter Group’s share price has climbed 11.7% year to date and delivered a 19.4% total shareholder return over the past year. However, the 90 day share price return declined 11.1%, which suggests recent momentum has cooled even as the longer term story remains strong.
Spot opportunities around Perimeter Group's earnings reset by scanning a curated set of 36 high quality undervalued stocks with resilient cash flows and balance sheets.Perimeter Group now looks like a healthier business on paper after its earnings reset and share price rebound. The next hurdle is simpler and harder at the same time: Is that quality already fully in the price?
Most Popular Narrative: 26% Undervalued
On the latest numbers, the analyst consensus Narrative on Simply Wall St sees fair value for Perimeter Group at $41.50, compared with a last close of $30.72. That gap frames the earnings reset as only part of a bigger valuation story built on long term contracts and margin assumptions.
Five year contracts with the Defense Logistics Agency and CAL FIRE, including annual price escalators and a year one pricing reset for CAL FIRE, increase visibility on volumes and pricing, which can support revenue growth and help protect segment margins.
Integration of MMT and IMS under a long duration ownership model, with targeted capital for new product development, productivity projects and add on product line acquisitions, is aimed at lifting Specialty Products revenue and improving adjusted EBITDA margins.
See why 3 investors see Perimeter Group as 26% undervalued.
Result: Fair Value of $41.50 (UNDERVALUED)
Still, the Perimeter Group story depends heavily on long term government contracts and on fixing the PDI issues at the Flexsys operated Sauget facility. Setbacks on either front could quickly challenge this undervalued narrative.
Find out about the key risks to this Perimeter Group narrative.
Another View: Perimeter Group on earnings multiples
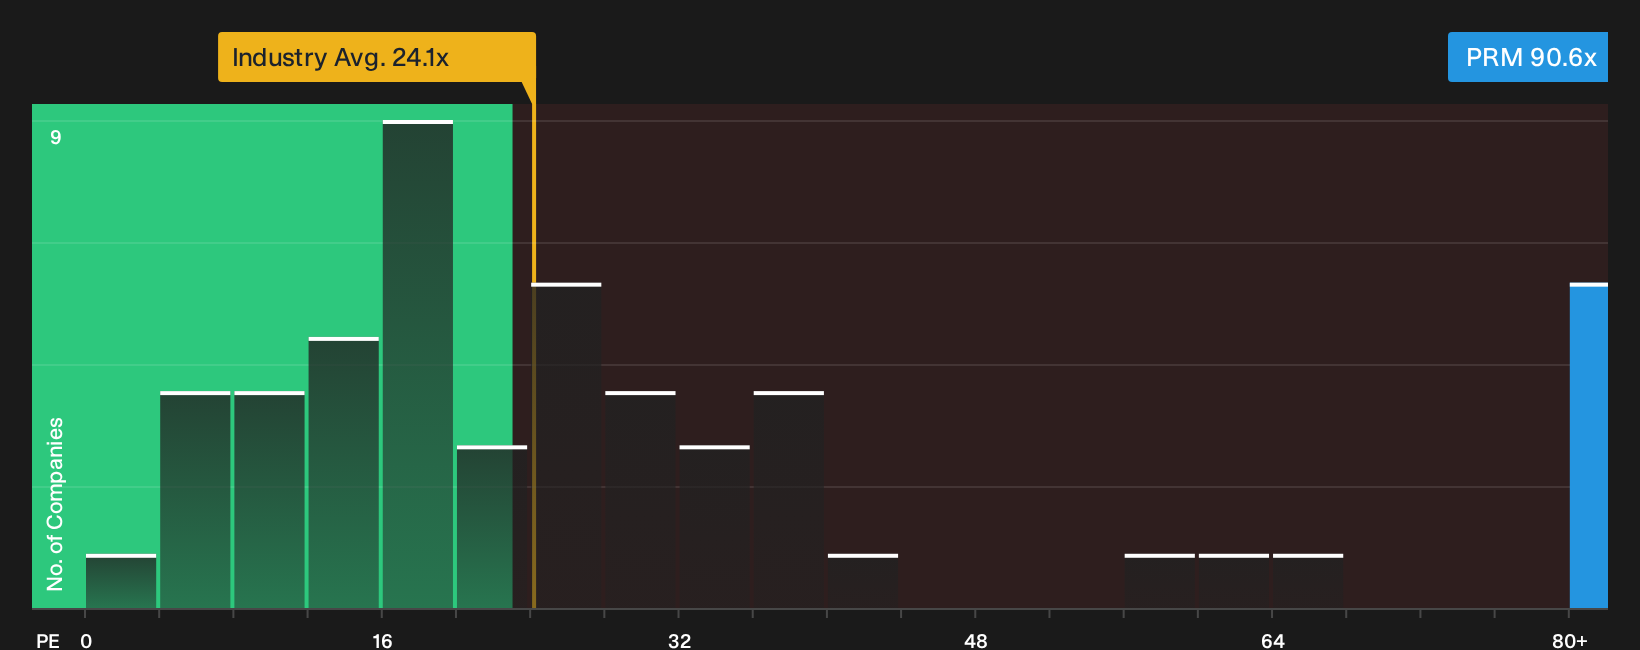
Perimeter Group looks cheap on future cash flow, yet the current P/E of 90.6x is much higher than the Chemicals industry at 24.1x, the peer average at 31.2x, and the fair ratio of 33.2x. That gap points to real valuation risk if sentiment or forecasts shift.
Investors who lean on earnings multiples rather than cash flow models may want to stress test their assumptions against this richer P/E and what it implies for downside if the market drifts closer to the fair ratio. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Perimeter Group is split, with both clear risks and clear upside in play. Move quickly and stress test the data yourself. To weigh both sides in one place and sharpen your own view, start with these 3 key rewards and 2 important warning signs
Looking for more investment ideas beyond Perimeter Group?
Perimeter Group may be front of mind after this earnings shift, but your next strong idea could come from a completely different corner of the market.
- Target steadier journeys by reviewing companies with resilient profiles through our 30 resilient stocks with low risk scores and see which businesses hold up when conditions get choppy.
- Hunt for mispriced opportunities by scanning the 36 high quality undervalued stocks that pair solid fundamentals with prices that do not fully reflect their underlying strength.
- Strengthen the foundation of your portfolio by checking companies with cleaner finances in the list of solid balance sheet and fundamentals (24 results) before others move in on them.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com