


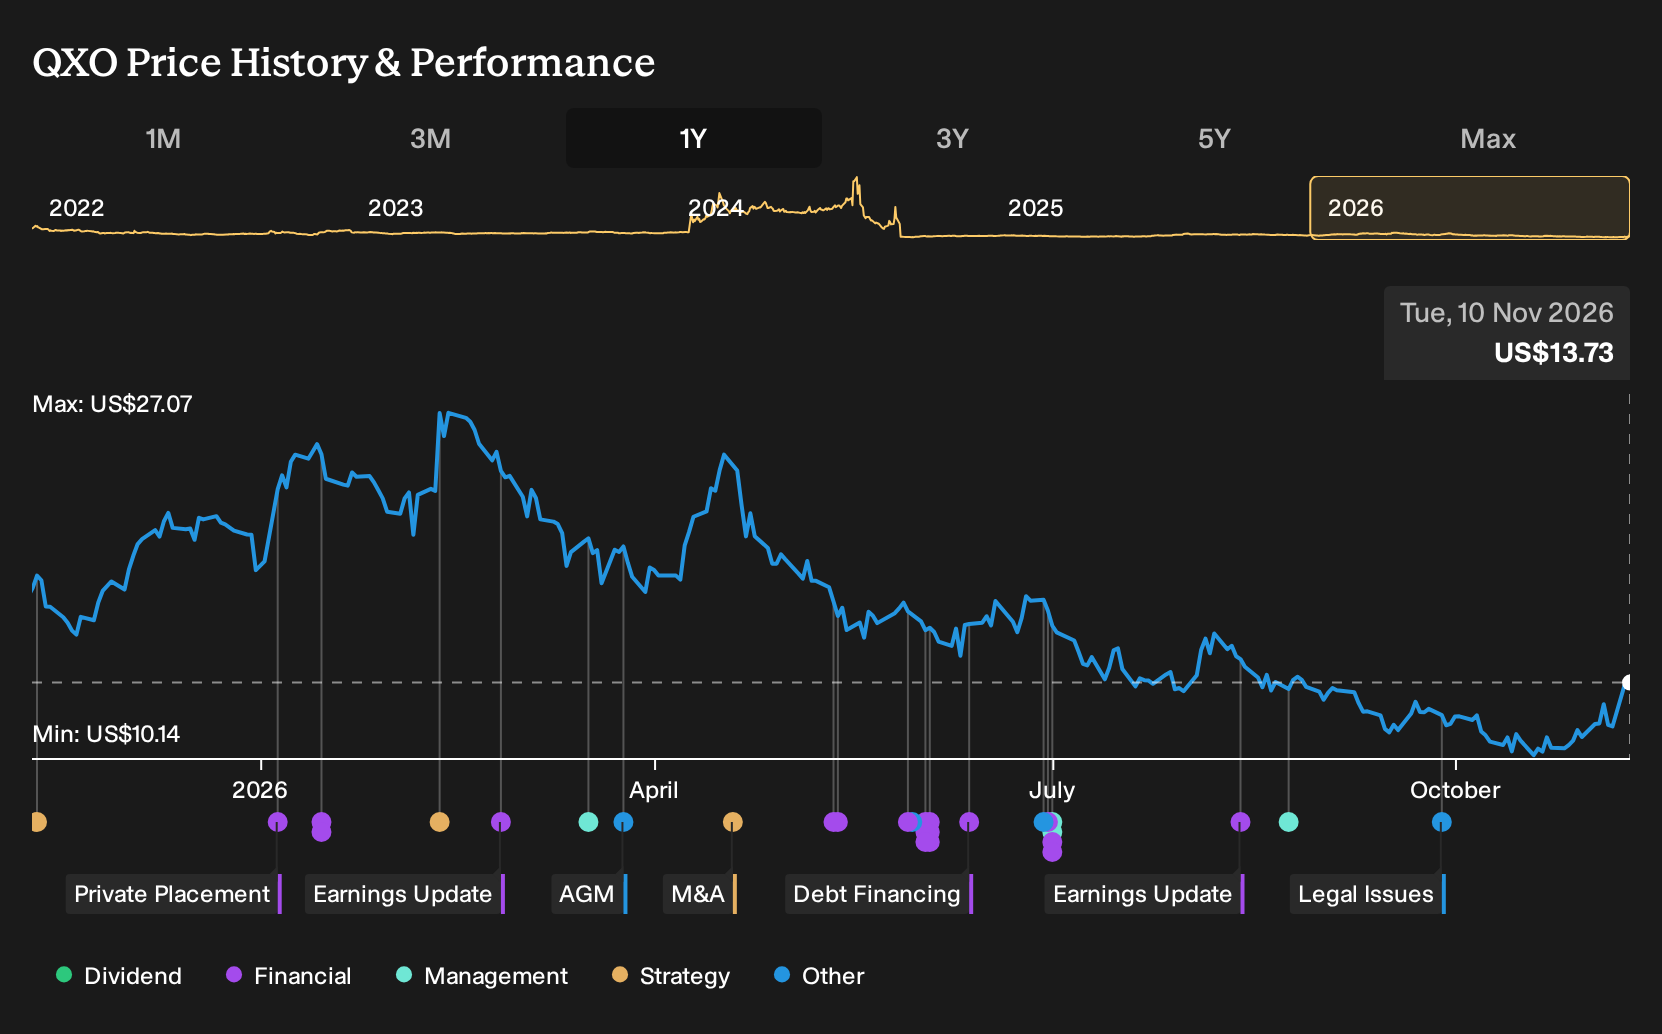
- QXO recently reported preliminary third quarter 2026 figures that highlighted much higher net sales and a narrower net loss, largely reflecting contributions from newly acquired businesses such as TopBuild, Kodiak Building Partners and Beacon Roofing Supply.
- The update put hard numbers behind QXO's acquisition heavy model in building products distribution and installation, giving investors a clearer view of how quickly recent deals are translating into operating scale and cost absorption across the combined platform.
- This article examines how QXO's investment narrative is being reshaped by preliminary Q3 results that highlight integration progress across its major acquisitions.
Compare QXO's acquisition-heavy story with other potential compounders by scanning our hand picked 20 high quality undiscovered gems across different sectors.
QXO Investment Narrative Recap
Owning QXO means believing the acquisition heavy model in building products distribution can turn today’s large revenue base into a healthier earnings profile over time. According to OOO97, an investor in the Simply Wall St Community, the key potential upside comes from improving gross margins with technology and squeezing more efficiency from the enlarged network.
Right now, the near term catalyst is basic execution. Investors are watching how quickly QXO can integrate TopBuild, Kodiak and Beacon while keeping service levels intact and interest costs under control. The biggest risk is that complexity from leverage and preferred stock slows that progress or limits flexibility for future deals.
The announcement that Brad Jacobs is committing US$1b into CKX Lands to build a separate roll up platform matters for QXO holders because it clarifies how his time and attention may be allocated. He will remain chairman and CEO at QXO while also leading CKX, which makes board process and management depth more important.
For catalysts, investors will likely focus on whether QXO can show clean, acquisition inclusive quarters that build on the preliminary Q3 trends without relying on fresh equity or heavy dilution. The CKX vehicle will be watched in parallel, since any perception of distraction or competing capital priorities could amplify existing concerns around QXO’s complex funding structure.
OOO97 anchors a fair value of US$32.53 for QXO based on a narrative where revenue compounds at 36.0% a year and the business reaches a 12.5% profit margin, which together support higher earnings power on a much larger distribution platform.
Uncover why QXO's fair value indicates a 137% potential upside to its current price. This gap may not last much longer.
Exploring Other Perspectives
Three fair value views from the Simply Wall St Community span roughly US$24.47 to US$44.83 for QXO, which already shows how far apart retail investors can land. Those opinions predate the CKX Lands plan and the upcoming Q3 release on 12 November 2026, so you may want to compare fresh scenarios and stress tests with them.
Explore 2 other QXO fair value estimates, including one that suggests as much as 226% potential upside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your QXO research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for QXO. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate QXO's overall financial health at a glance.
Looking for more investment ideas beyond QXO?
Once you have a view on QXO, it can help to benchmark that thesis against other companies with different strengths, balance sheet profiles and payout policies using the Simply Wall St Screener.
- For readers who want to focus on quality at a sensible entry point, scan a curated set of 36 high quality undervalued stocks that combine strong fundamentals with more modest pricing.
- If capital preservation sits high on your priority list, filter for resilience by reviewing a 30 resilient stocks with low risk scores that may better match a steadier approach.
- Income focused investors can look for reliability first and yield second by checking a 5 dividend fortresses that highlight companies with higher payouts and supportive metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com