


UK rates are rising, inflation is sticky and energy remains expensive, which puts income portfolios under real stress. Cash in the bank feels safer, yet inflation at 3.5% and forecasts above 4% quietly eats into that comfort. This article looks at three large UK dividend stocks exposed to these rate and inflation shocks, and shows where the current backdrop could help or hurt long term income hunters.
The three stocks covered next are only a starter set from this defensive income idea, and the full screen on Simply Wall St surfaced 10 more large UK dividend payers with similarly solid stories that are not covered here. To identify and analyze potential higher conviction picks that match your own risk and income needs, head straight to the UK Large-Cap Defensive Dividend Stocks screener.
A.G. BARR (LSE:BAG)
Overview: A.G. BARR is a long-established UK soft-drinks group whose IRN-BRU and other brands provide consumer-staple exposure and dividend-paying cash generation.
Operations: A.G. BARR generates most of its revenue from Soft Drinks at £399 million, with Cocktail Solutions contributing £32 million and Others £25 million.
Market Cap: £659 million
A.G. BARR fits this defensive dividend screen through its branded soft drinks focus, £659 million scale and 3.16% yield. However, the dividend is not well covered by free cash flow, so the appeal for income investors still hinges on what happens if a single key assumption breaks around cash conversion and funding costs.
If that cash conversion question is on your mind, go straight to the DCF valuation analysis for A.G. BARR to see how those assumptions shift the long term income story.
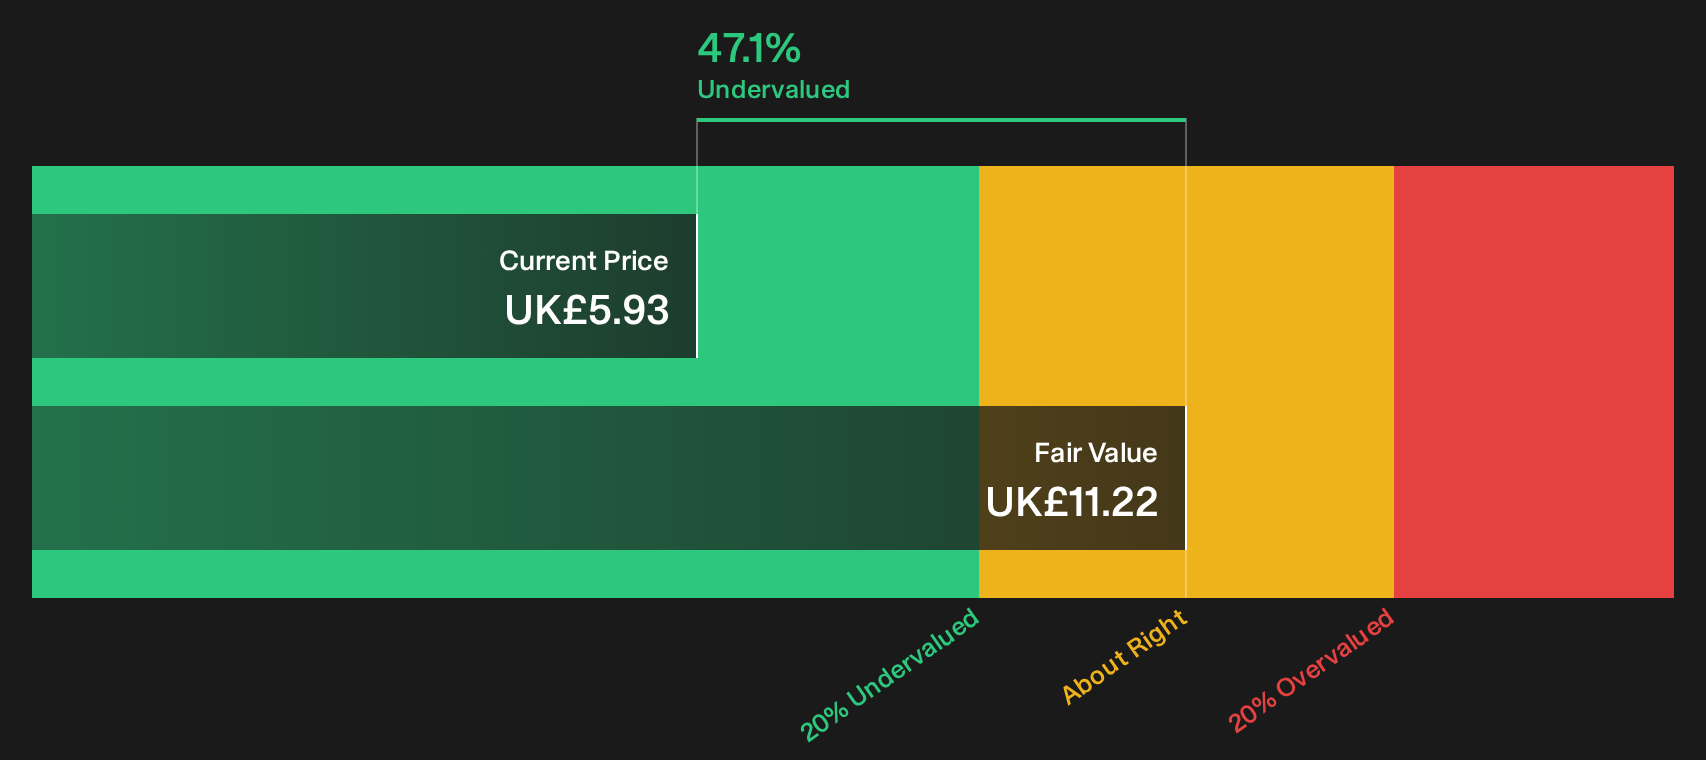
Cranswick (LSE:CWK)
Overview: Cranswick is a UK-based producer of fresh meat, poultry, and convenience foods supplying major grocers and food service customers.
Operations: Cranswick generates about £2.93b from Food and £47.6 million from Other activities, with roughly £2.91b coming from the United Kingdom.
Market Cap: £3.0b
Cranswick sits neatly in this defensive dividend screen because it is a large UK consumer staples supplier where shoppers still need to buy protein and convenience foods. DKDGI, an investor in the Simply Wall St Community, argues its income profile reflects that consistency over time.
"Dividend raised 36 years in a row, with payout steady at ~37% of EPS and very low debt.
What really matters now is how one shifting cost pressure interacts with that long record of discipline around cash, pricing, and investment.
That shifting pressure is exactly what sits behind the full narrative for Cranswick, which explains how Cranswick’s discipline could either accelerate or stall income resilience from here.

Nichols (AIM:NICL)
Overview: Nichols is a UK soft-drinks group behind brands like Vimto and SLUSH PUPPiE, supplying defensive everyday beverages to retailers and leisure venues worldwide.
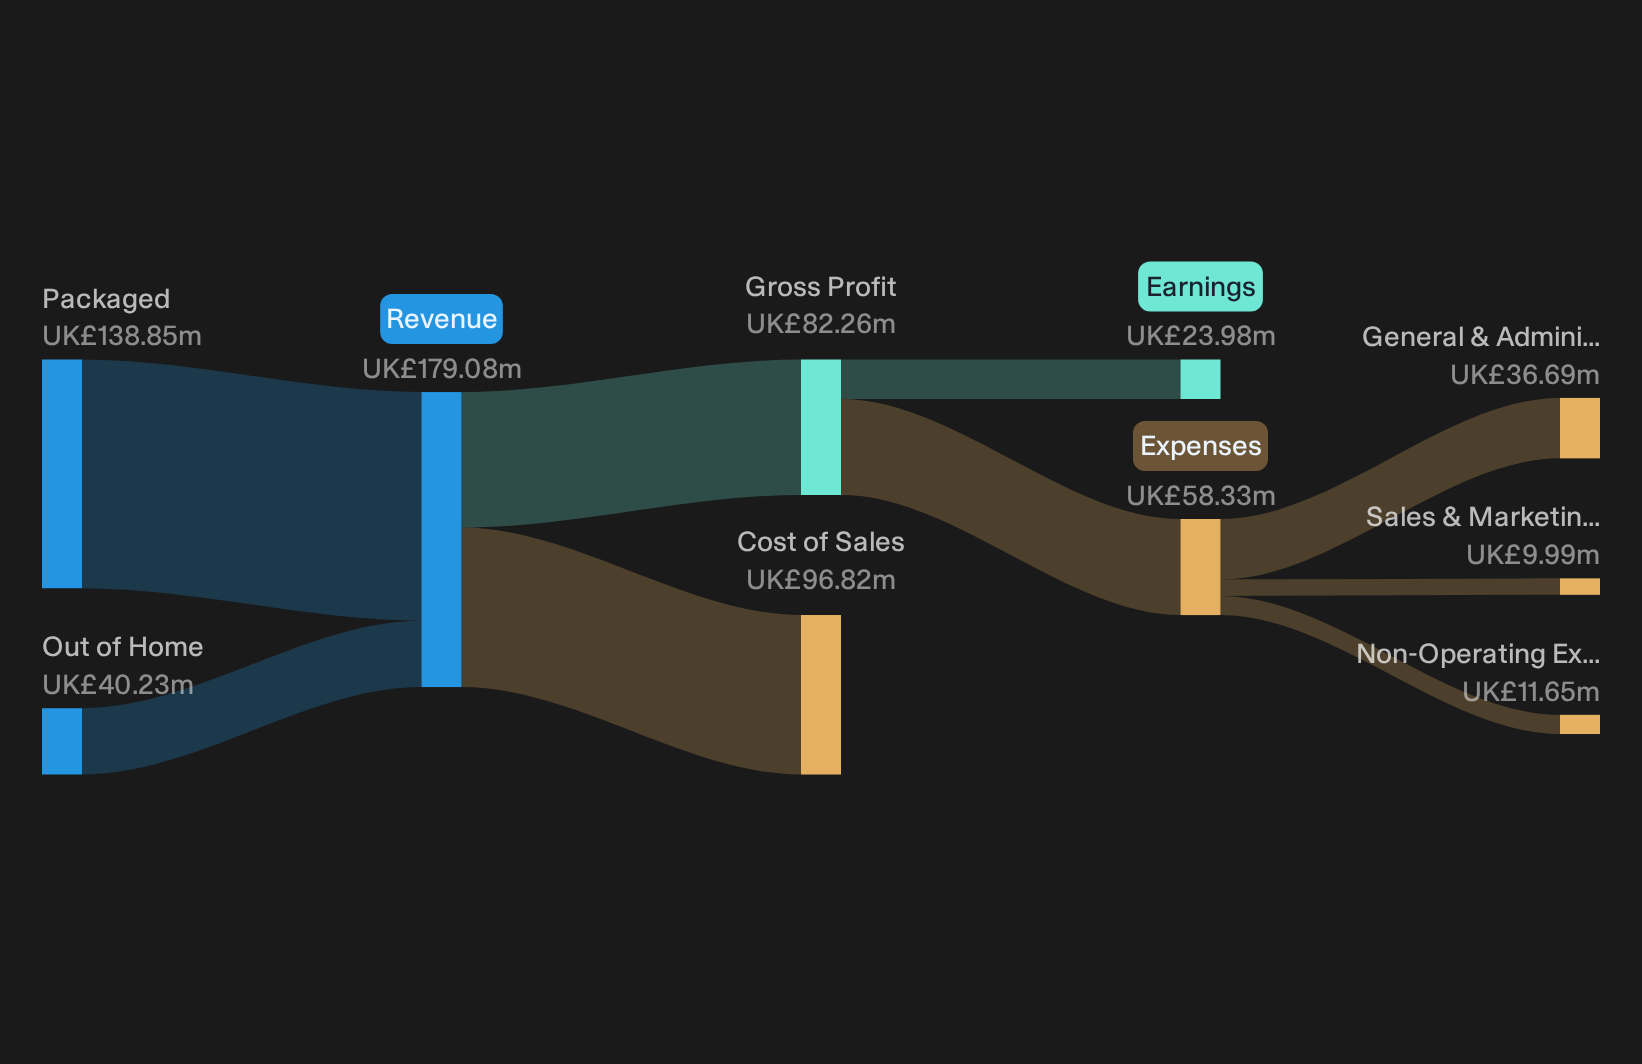
Operations: Nichols generates about £139 million from packaged drinks and £40 million from out-of-home channels, with roughly £133 million from the UK and meaningful sales across Africa and the Middle East.
Market Cap: £388 million
Nichols fits this defensive dividend screen because its soft-drinks portfolio spans everyday UK consumption and higher margin concentrates in overseas markets. This is where the bullish analyst Narrative on Simply Wall St focuses its discussion of income and cash flow.
"Expansion of Ramadan themed activity in the Middle East, where Nichols reports value growth ahead of the wider market, can support further premiumisation of cordial and concentrate formats and lift revenue and earnings from that region."
What may decide how Nichols serves long-term dividend-focused investors is whether any less visible pressures limit how far that premiumisation can push margins.
Those hidden pressures are exactly what the Simply Wall St full narrative for Nichols unpacks, separating short term noise from where Nichols’ income story could be quietly accelerating.
Seeking Alternatives Before Momentum Flies
Fresh opportunities do not sit still. Breakout stories gain momentum, under-the-radar ideas get caught, and entry points start dropping out of reach. Scan these hand-picked lists and get in early.
- Spot resilient cash generators before the crowd by running the list of solid balance sheet and fundamentals (9 results). This lets you focus on fundamentals that can carry an income stream through tougher cycles.
- Target stronger yield opportunities by using the 6 dividend fortresses to sift for income plays where high payouts and sturdier profiles sit together, not in conflict.
- Track early winners in automation by scanning the 91 robotics and automation stocks and see which operators could benefit first if spending keeps shifting toward robots and smarter production lines.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com