


Vir Biotechnology (VIR) is back in focus after its two-drug regimen for chronic hepatitis delta hit all primary and key secondary targets in the pivotal Phase 3 ECLIPSE 1 study.
The latest hepatitis delta data arrived in a market that had already re-rated Vir Biotechnology sharply, with a 1-year total shareholder return of 130.30% and a year-to-date share price return of 121.38%, pointing to strong momentum that recent trial wins have reinforced.
Scan how other healthcare and biotech names are reacting to breakthroughs like Vir Biotechnology’s ECLIPSE 1 win by running the hand picked 36 healthcare AI stocks alongside your watchlist.
Vir Biotechnology’s surge now forces a simple question: Are you seeing clinical progress finally catching up with the share price, or a sentiment reset that has run ahead of what the business currently supports on fundamentals?
Most Popular Narrative: 37% Undervalued
Vir Biotechnology closed at $13.15, while the analyst consensus Narrative on Simply Wall St anchors fair value at $21.00 using a 7.53% discount rate. This frames the recent rally as still short of narrative fair value.
Analysts are assuming Vir Biotechnology's revenue will decrease by 21.2% annually over the next 3 years.
Analysts are not forecasting that Vir Biotechnology will become profitable in the next 3 years. To represent the Analyst Price Target as a Future PE Valuation, this approach estimates that Vir Biotechnology's profit margin will change from -83.0% to the average US Biotechs industry margin of 18.3% in 3 years.
What is behind 13 investors see Vir Biotechnology as 37% undervalued.
Result: Fair Value of $21.00 (UNDERVALUED)
Still, the Vir Biotechnology story carries real pressure points, including reliance on unproven HDV and oncology programs and analyst assumptions for sharply declining near term revenue.
Find out about the key risks to this Vir Biotechnology narrative.
Another View: Vir Biotechnology Through The Sales Multiple Lens
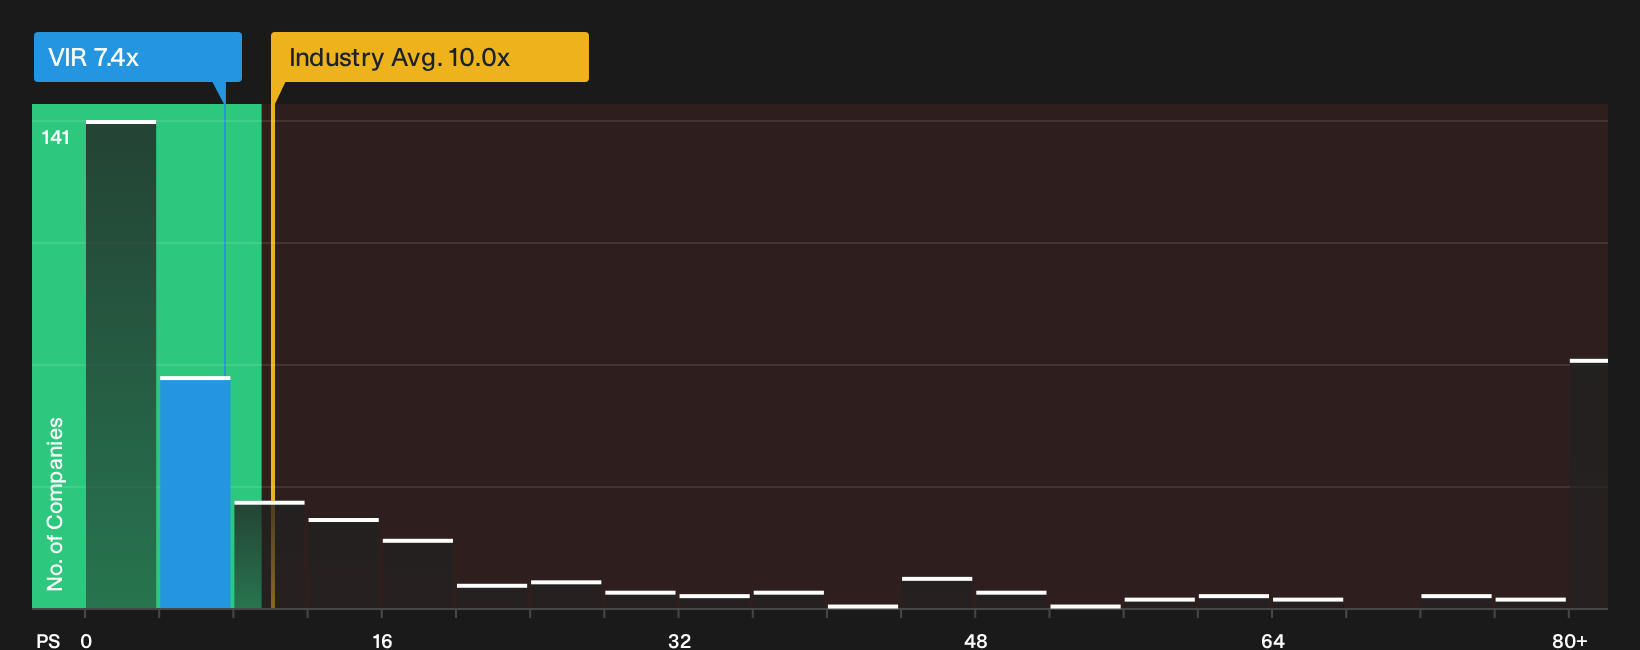
The analyst fair value narrative presents Vir Biotechnology as 37% undervalued, yet the P/S ratio tells a tougher story. The stock trades at 7.4x revenue while the US Biotechs industry sits around 10x, and the fair ratio points closer to 1.1x, which signals meaningful repricing risk if sentiment cools.
Put differently, Vir Biotechnology appears cheaper than peers but far richer than the fair ratio that the market could eventually lean toward. That gap can cut both ways for investors, since it can either compress sharply or stay elevated if confidence in the HDV and oncology story remains. Which side of that trade are you really underwriting?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Big moves and strong opinions often go together, but your decision on Vir Biotechnology should rest on your own reading of the numbers and risk profile. Before you commit fresh capital or pass altogether, weigh the upside story against at least one concern flagged in our breakdown of 3 important warning signs.
Looking for more investment ideas beyond Vir Biotechnology?
If Vir Biotechnology has your attention today, do not stop there. Use the same discipline across a wider watchlist to keep fresh opportunities on your radar.
- Target potential mispricing across the market by checking companies that screen as quality and undervalued through the 36 high quality undervalued stocks.
- Strengthen the defensive side of your portfolio by focusing on businesses with robust finances using the list of solid balance sheet and fundamentals (24 results).
- Hunt for underfollowed opportunities with strong fundamentals by scanning the 20 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com