


Bank of New York Mellon Corporation (BNY) just pushed deeper into digital finance by expanding its custody platform with Ripple and linking LiquidityDirect into Tradeweb’s ICD Portal for treasury clients.
Recent headlines around Ripple and Tradeweb arrive after a strong run. BNY’s share price is up 29.14% year to date to US$151.14, while the 1-year total shareholder return of 38.14% sits on top of a very large 3-year gain and a 192.25% 5-year total return. This points to momentum that has been building over several years, even with a 90-day share price return that has slipped 7.24% as investors reassess risk around faster digital expansion.
Scan how Bank of New York Mellon Corporation’s push into digital custody compares with other institutions leaning into tokenization and on-chain workflows by reviewing the 20 high quality undiscovered gems in this space.
After Bank of New York Mellon Corporation’s digital custody push and a period of strong multi year share gains, the real tension is simple: does the current valuation still leave enough upside to justify the extra digital risk?
Most Popular Narrative: 7% Undervalued
Bank of New York Mellon Corporation’s analyst consensus Narrative on Simply Wall St places fair value at about $163.36 compared with the last close at $151.14. This frames the current digital push against a valuation that still prices in solid execution.
Accelerated investment in digital platforms, including the AI supported platform operating model funded by roughly US$4b of annual engineering spend and hundreds of AI use cases, is now showing up in 600 basis points of positive operating leverage in the first half of 2026. This can continue to influence net margins and earnings as capacity creation allows more revenue on a relatively fixed employee base.
See why 48 investors see Bank of New York Mellon as 7% undervalued.
Result: Fair Value of $163.36 (UNDERVALUED)
Still, Bank of New York Mellon Corporation’s story can change quickly if fee pressure hits core custody and asset servicing, or if sector wide P/E multiples reset lower.
Find out about the key risks to this Bank of New York Mellon narrative.
Another View: Our DCF Model Paints A Tighter Picture
The first take on Bank of New York Mellon Corporation leans on analyst targets that frame BNY as about 7% undervalued at $151.14 versus a US$163.36 fair value. Our DCF model is more conservative, with a future cash flow value of $147.18, which implies the shares trade slightly above that estimate. Which lens do you trust when the digital story is moving this fast?
Investors who want to see how this second framework works line by line can review the Look into how the SWS DCF model arrives at its fair value..
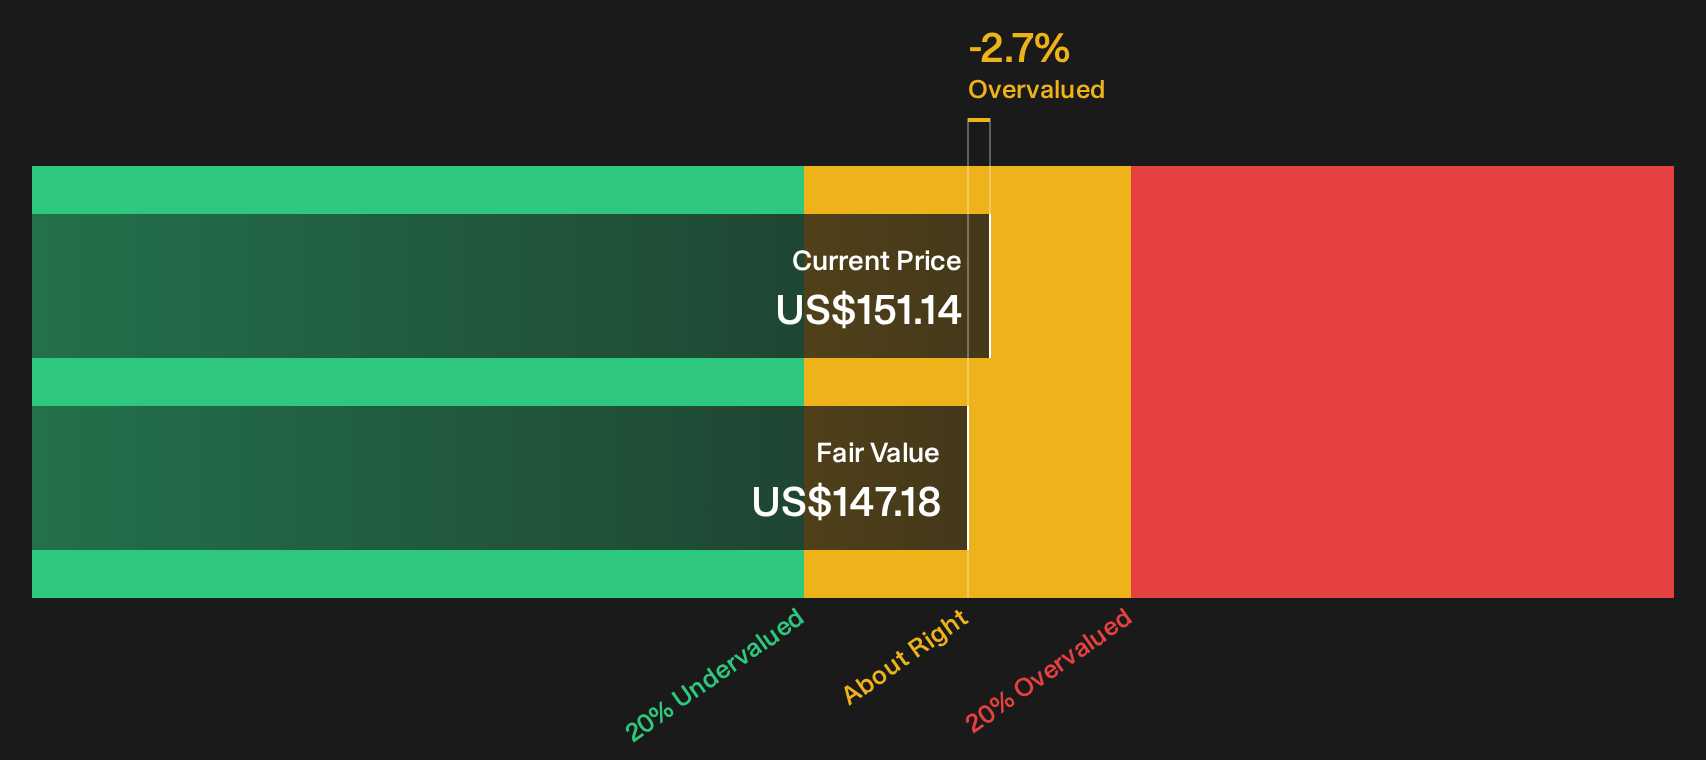
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Bank of New York Mellon for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 36 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Bank of New York Mellon Corporation’s digital push and valuation so far. Act while the numbers are fresh in your mind and test the narrative against the underlying data by weighing the 5 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Bank of New York Mellon Corporation?
You have seen how quickly a story like Bank of New York Mellon Corporation can evolve. Do not stop here when a broader watchlist could sharpen your next move.
- Target resilient compounders by scanning companies with strong cash generation and attractive valuations through the 36 high quality undervalued stocks.
- Build a steadier income stream by focusing on businesses that match your yield expectations using the 5 dividend fortresses.
- Lower your downside risk by concentrating on businesses that score well on stability metrics through the 30 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com