


Sunoco (TXSE:SUN) has just posted third quarter 2026 results that reshaped the recent story around the stock, with sharp moves in both sales and earnings catching investors’ attention.
Recent trading tells a mixed story. Sunoco’s share price is down 16.3% over the past month and 15.1% over the past quarter, yet it is still up 19.9% year to date, with a 1 year total shareholder return of 31.6% and a 5 year total shareholder return of 122.4%. This suggests that long term holders are still being rewarded even as short term momentum has cooled following the earnings reaction.
Spot under-the-radar peers pursuing similar scale and earnings stories by scanning our curated list of 20 high quality undiscovered gems alongside Sunoco.Sunoco now splits opinion. Bulls point to surging earnings and acquisition scale, while bears flag the sharp pullback and execution risk. Which story does the current valuation actually support next?
Most Popular Narrative: 24% Undervalued
Against a last close of $63.21, the analyst consensus Narrative on Simply Wall St anchors Sunoco’s fair value at $83. This frames the recent pullback as a valuation gap rather than a broken story and leans heavily on the acquisition and integration plan to close that gap over time.
Synergy capture and operational optimisation remain central to the Sunoco playbook, with Parkland integration expected to deliver US$125 million of in year synergies in 2026 toward a targeted annual run rate above US$250 million. This directly targets higher EBITDA and distributable cash flow per unit from acquired assets.
See why 21 investors see Sunoco as 24% undervalued.
Result: Fair Value of $83 (UNDERVALUED)
Still, if gasoline demand remains roughly flat and maintenance capital stays near US$400 million to US$450 million, Sunoco’s acquisition-heavy approach could face tougher scrutiny.
Find out about the key risks to this Sunoco narrative.
Another View: How Sunoco Looks On Earnings Multiples
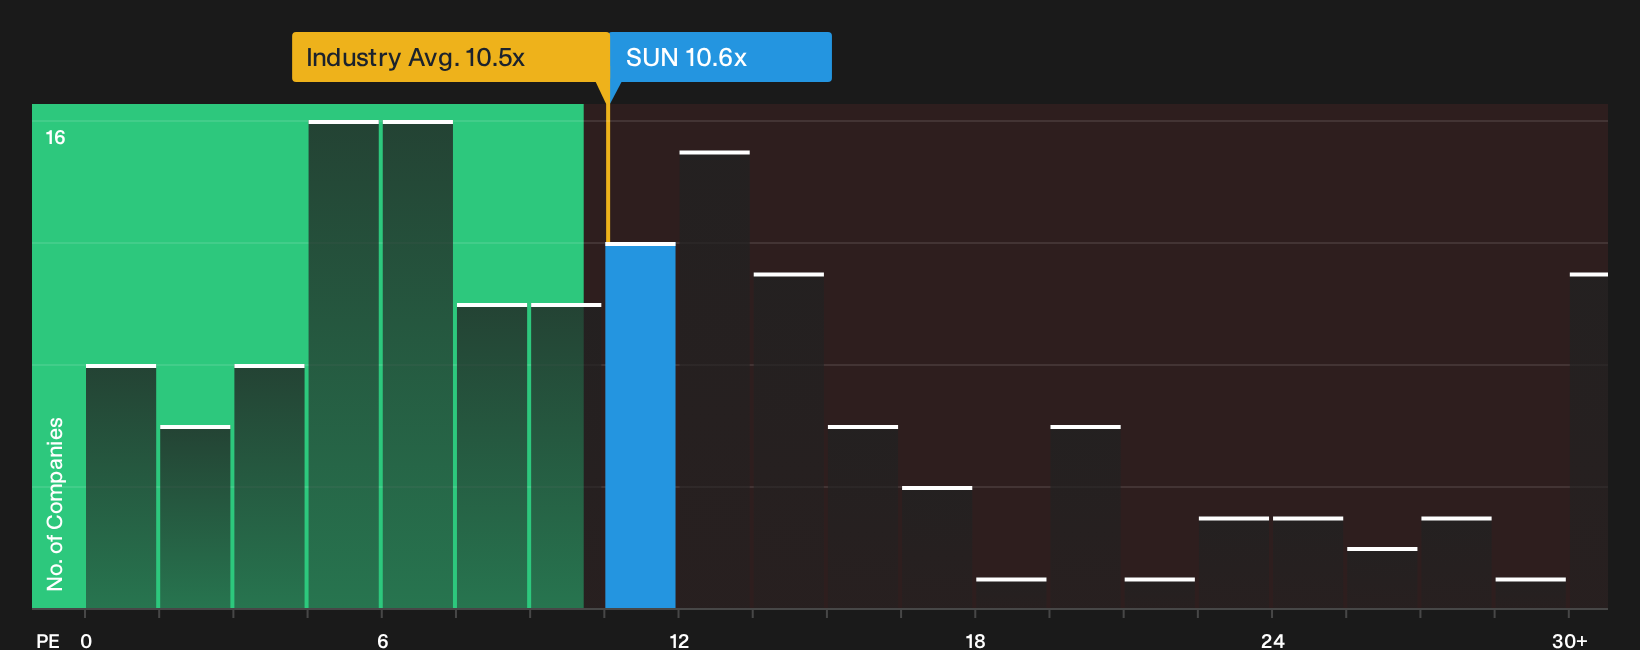
There is a very different message once you leave models and look at what investors are actually paying for Sunoco today. The units trade on a P/E of 10.6x, which is slightly higher than the US Oil and Gas industry at 10.5x and well above the 6.9x peer average.
At the same time, the fair ratio sits at 21.8x, roughly double the current P/E. That gap highlights a potential difference between the current price and the fair ratio, yet it also raises a simple question for you. Is the market being conservative, or are peers signaling caution about how much you pay for this growth story?
See what the numbers say about this price, find out in our valuation breakdown.See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Sunoco can be confusing. Move quickly to test the numbers, weigh both the concern and the optimism, and then lean on the 5 key rewards and 1 important warning sign.
Looking for more Sunoco sized investment ideas?
If you stop with Sunoco, you risk missing other opportunities entirely. Put a few fresh watchlist candidates through their paces with these focused stock ideas.
- Target resilient cash generators first by scanning a list of solid balance sheet and fundamentals (24 results) that can help support steadier compounding when conditions get tougher.
- Hunt for mispriced quality by reviewing a hand picked 36 high quality undervalued stocks that pairs strong fundamentals with a gap between price and underlying worth.
- Build your income stream on sturdier foundations by checking a curated list of 5 dividend fortresses that aim to balance yield with staying power.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com