


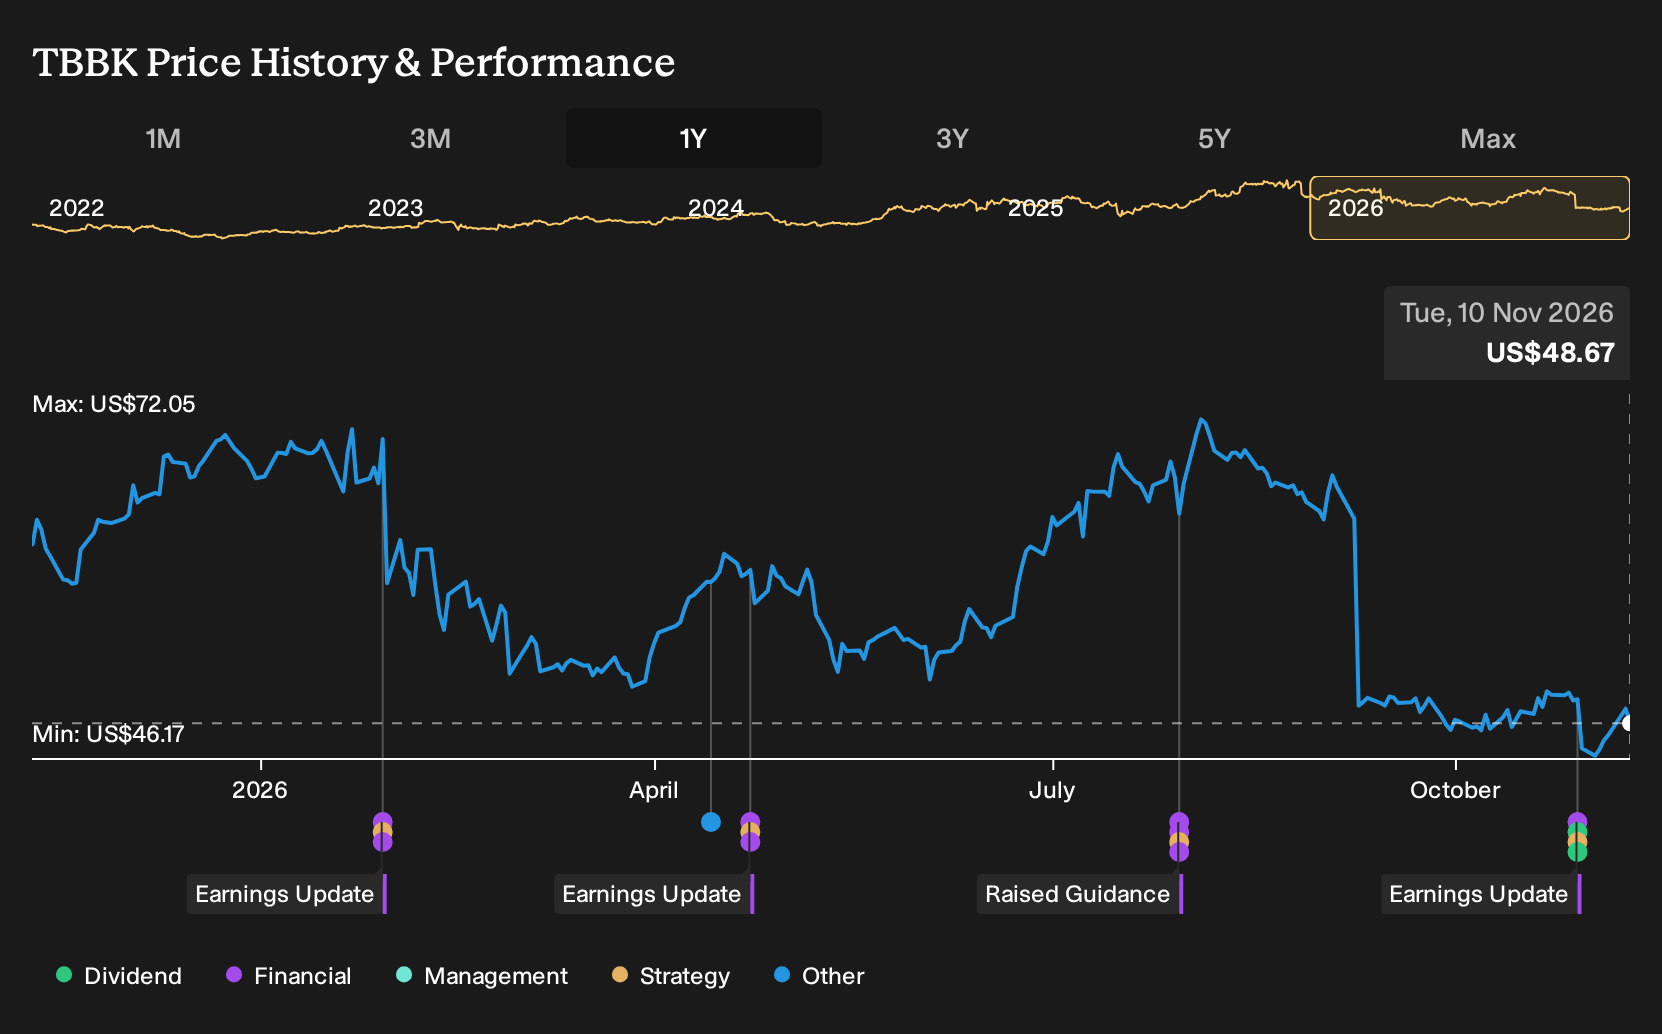
- The Bancorp, Inc. reported third quarter 2026 net income of US$62.78 million and basic EPS from continuing operations of US$1.54, alongside a new share repurchase authorization tied to cumulative adjusted net income through the first quarter of 2028.
- Despite lower net interest income for both the quarter and year to date, Bancorp’s higher earnings per share and sizeable buyback plan highlight a business focusing on efficiency, fee mix and capital returns, rather than relying solely on balance sheet expansion.
- Investors can now observe how Bancorp’s investment narrative may evolve with rising earnings per share in conjunction with this cumulative net income repurchase commitment.
Scan how Bancorp’s capital return focus compares with other banks by running the hand picked list of solid balance sheet and fundamentals (24 results) that keeps earnings power and balance sheet strength front and center.
Bancorp Investment Narrative Recap
Bancorp asks you to believe that a specialist banking model can keep turning partner programs into steady earnings, even as individual relationships change. The latest quarter showed net interest income for both the quarter and year to date below the prior period, yet net income and EPS were higher. As a result, the near term story leans on mix, efficiency and fee engines rather than sheer asset growth.
The biggest short term swing factor still ties back to fintech partner concentration and how any shifts flow through revenue and returns. Credit quality trends matter too. Net charge offs of US$40.664 million were similar to a year ago, so the new numbers do not materially change the key risk reward debate around partner churn and margin resilience.
The fresh buyback authorization, which allows Bancorp to repurchase up to roughly 100% of cumulative adjusted net income through the first quarter of 2028, is the announcement that really connects to this earnings release. EPS from continuing operations moved to US$1.54 basic and US$1.53 diluted in the quarter while net income reached US$62.78 million, so each dollar retired has a clearer earnings reference point.
According to John_Eric, an investor in the Simply Wall St Community, past capital returns already had a big influence on reported return on equity, and the new program keeps that capital allocation thread in focus. For you as a shareholder, the execution question is whether the bank can keep generating enough profits, while managing partner and credit risks, for this level of repurchases to stay aligned with the long term earnings power of the business.
In John_Eric’s narrative, Bancorp’s fair value of US$52.00 reflects a model that assumes revenue growth of 1.2% a year and a future profit margin of 43.6%. Together, these factors frame what the business might justify on its current balance sheet and partner mix over time.
Uncover why Bancorp's fair value indicates a 7% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic analysts focus less on Chime risk and more on Bancorp’s ability to grow fintech earnings. Before this earnings release, the bullish group was looking for revenue of about US$328.8 million and earnings of US$296.4 million by 2029, with EPS near US$9.12. Those expectations could shift as you compare today’s results with several competing viewpoints.
Explore 2 other Bancorp fair value estimates, including one that suggests as much as 179% upside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis.
- A great starting point for your Bancorp research is our analysis highlighting 5 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Bancorp. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Bancorp's overall financial health at a glance.
Looking For More Investment Ideas Beyond Bancorp?
Bancorp’s story might be front of mind right now. Your overall results often depend on the mix of opportunities held alongside it. The Simply Wall St Screener can help you quickly scan for other companies that match the kind of quality, value or resilience you want to pair with this bank.
- If you want potential upside with quality in focus, review a 20 high quality undiscovered gems that filters for strong fundamentals that may not yet be widely followed.
- For investors who care most about capital strength and staying power, run a 30 resilient stocks with low risk scores that highlights businesses with more resilient profiles.
- Income focused readers can turn to a 5 dividend fortresses that concentrates on higher yielding companies with an emphasis on consistency.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com