


- Rakuten Group and AST SpaceMobile have created Rakuten AST in Japan to build a low Earth orbit, direct-to-smartphone satellite network, backed by up to ¥148b of government support over roughly three years under the J LEo program.
- The venture positions Rakuten Group closer to critical communications infrastructure, with potential value in disaster resilience, nationwide coverage, and future AI-driven spectrum management services across telecom and connectivity-heavy industries.
- The next phase will focus on how Rakuten Group's investment narrative could shift as this government-backed satellite network plan develops.
Rakuten Group Investment Narrative Recap
For Rakuten Group, you really need to buy into the idea that the mobile, internet services and FinTech ecosystem can absorb heavy network spending and still move closer to consistent profitability. The analyst consensus Narrative on Simply Wall St puts that ecosystem execution at the center, with AI efficiency gains and cost discipline doing much of the work on margins.
The new Rakuten AST venture adds an extra layer to that operating story. Government support of up to ¥148b softens some investment strain, but Rakuten Mobile already plans over ¥200b of capex in 2026 and still reports non GAAP operating losses. The near term swing factor remains whether mobile losses shrink fast enough relative to group cash generation.
Among the existing catalysts, Rakuten Group’s AI deployment sits closest to this satellite move. Management reports ¥25.5b of profit contribution from AI in 2025 and is targeting roughly triple the 2024 contribution in 2026. That same toolkit is now earmarked for AI driven spectrum management and edge computing in the non terrestrial network.
If execution lines up, the combination of AI, mobile and satellite could influence both operating leverage and ecosystem engagement, especially in connectivity heavy industries such as logistics and infrastructure monitoring. The analyst consensus Narrative on Simply Wall St already leans on AI and mobile capex as key drivers, so the Rakuten AST project mainly raises the bar on delivery and capital allocation discipline rather than changing the core thesis.
What The Current Forecasts Assume For Rakuten Group
Analysts currently model a steady revenue climb for Rakuten Group, with forecasts pointing to 7.5% yearly top line growth over the next three years. Profitability in those projections also shifts from a loss position today, where the group reports a profit margin of 2.4%, to a positive margin of 3.3% in roughly three years.
On earnings, the consensus view aggregates into a target of ¥109.6b of profit by about 2029, compared with an earnings loss of ¥64.4b today. That indicates an earnings swing of roughly ¥174.0b from current levels to the 2029 forecast. Analyst estimates are wide, with the most optimistic modeling ¥213.0b of earnings and the most cautious closer to ¥73.7b.
These assumptions underpin the current Rakuten Group valuation framework. For the analyst price targets to hold, the business would need to support a P/E of 24.8x on the 2029 earnings estimate of ¥109.6b, up from a current implied multiple of 21.6x, which is compared with a JP Multiline Retail industry average of 15.7x. Forecasts also factor in modest equity dilution, with the share count projected to grow by 0.68% per year over the next three years.
Rakuten Group's narrative projects revenues of ¥3,285.1b and earnings of ¥109.6b by 2029. This rests on analyst assumptions of 7.5% yearly revenue growth and an earnings swing of about ¥174.0b from an earnings loss of ¥64.4b today.
Discover why Rakuten Group's fair value indicates a 37% potential upside to its current price, which could materialize sooner than many investors expect.
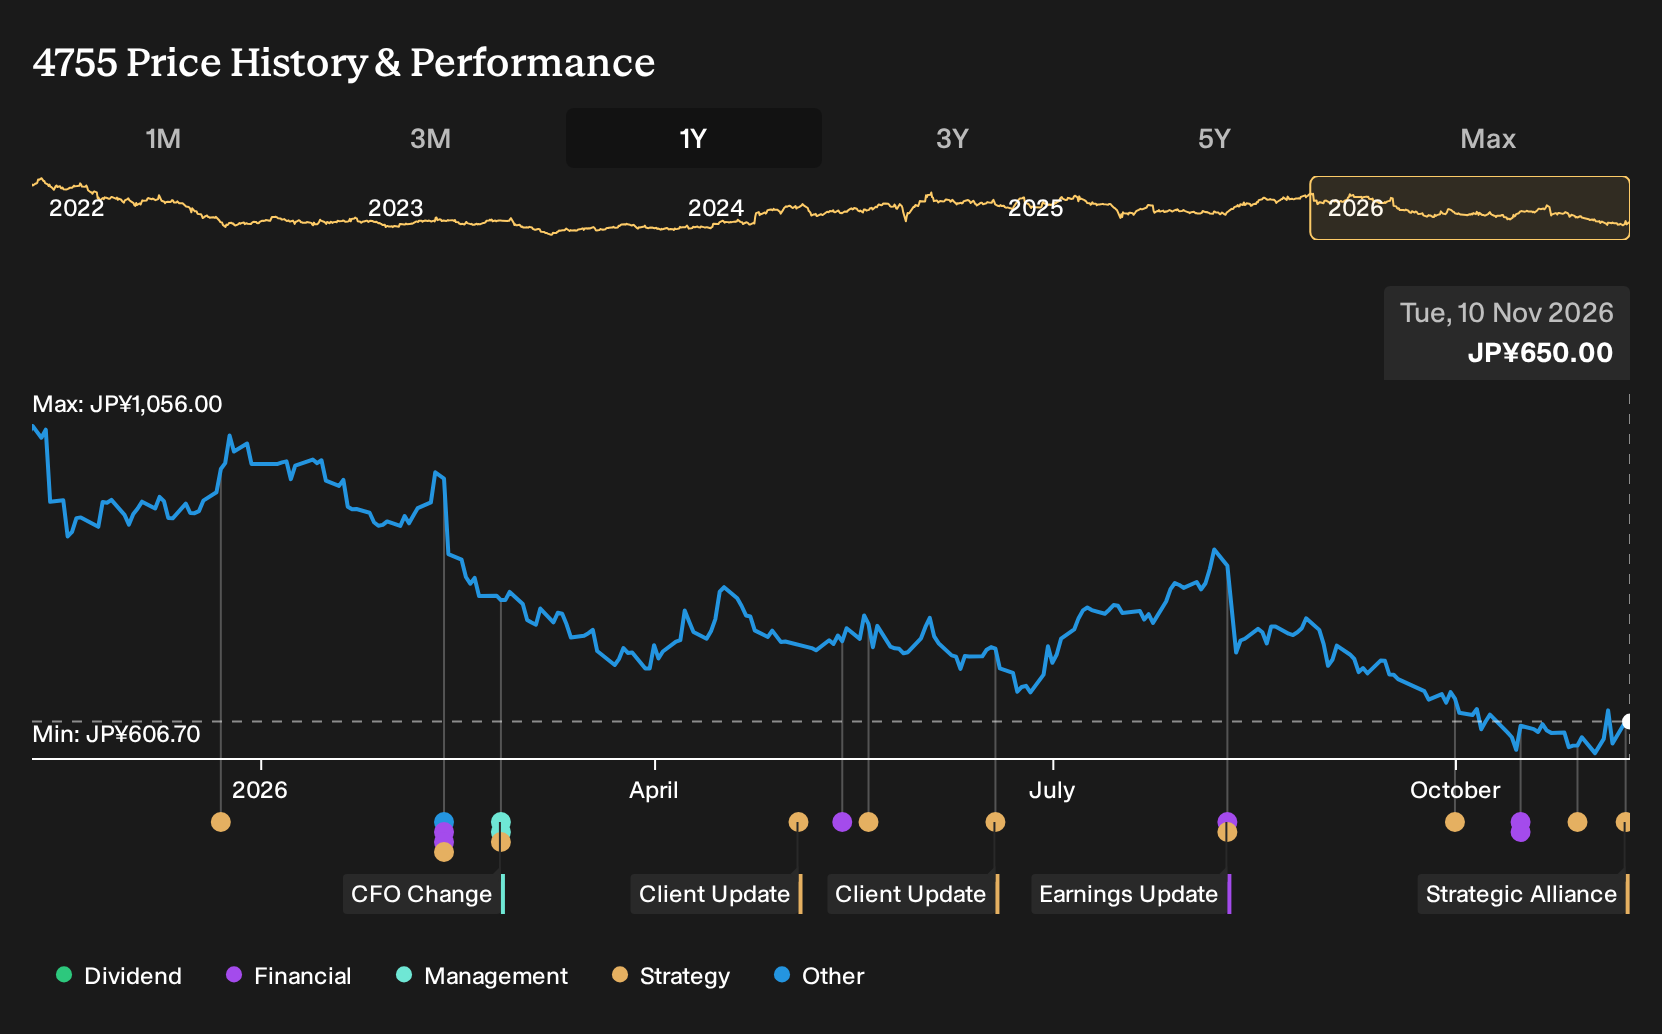
Exploring Other Perspectives
One alternate angle focuses on capital strain. The most bearish analysts already assumed Rakuten Group would reach only ¥3,023.1b in revenue and ¥73.4b in earnings by 2029, well below consensus. You can read that as a view that heavy mobile and now satellite spending might cap profitability. Future updates to these forecasts may revisit that view after this news.
Explore 3 other Rakuten Group fair value estimates, including one that suggests it could be worth just ¥890!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Rakuten Group research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Rakuten Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Rakuten Group's overall financial health at a glance.
Looking For More Investment Ideas Beyond Rakuten Group?
Once you have a view on Rakuten Group, it can help to compare that thesis with other stocks that share similar qualities or appeal to a different risk profile. The Simply Wall St Screener groups companies by traits that matter, so you can quickly build a watchlist that matches your style rather than scrolling aimlessly through tickers.
- If capital preservation is a priority, start with companies that score well on resilience and balance sheet strength by reviewing 19 resilient stocks with low risk scores.
- If you want to focus on businesses that already generate solid cash flows and have cleaner financial footing, scan the list of solid balance sheet and fundamentals (23 results).
- If you are hunting for future leaders that are not widely followed yet, filter for structurally strong but less crowded opportunities with the 73 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com