


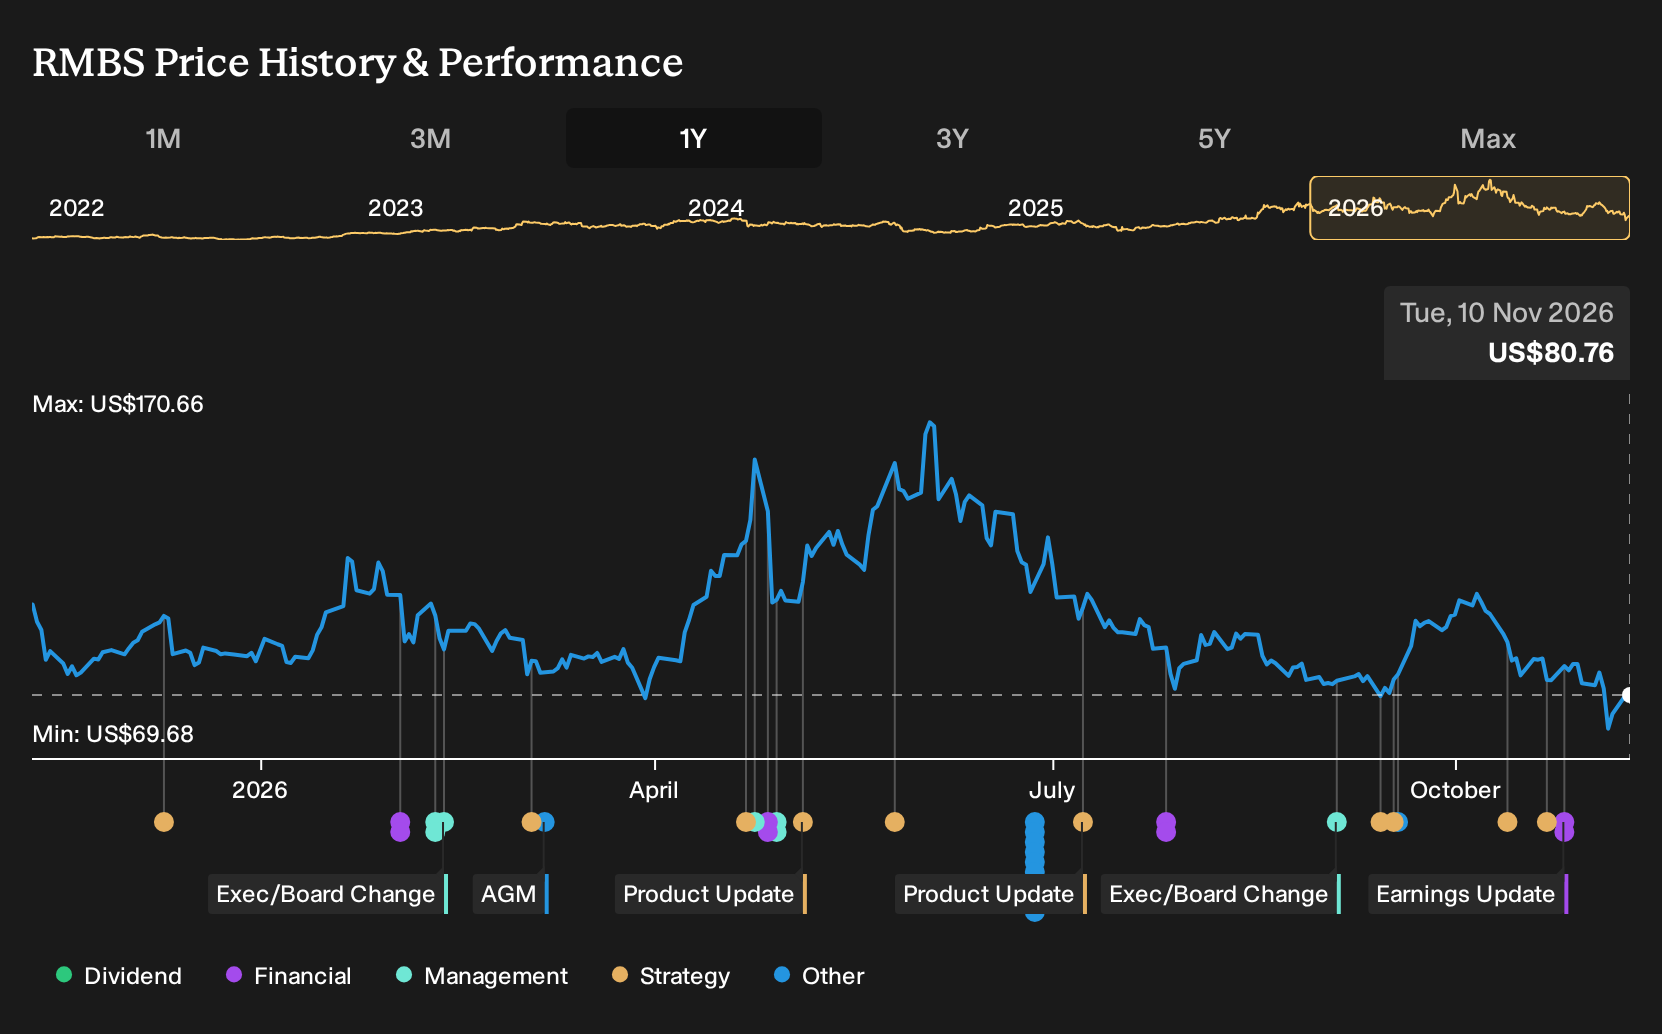
- Rambus recently saw a technical hammer pattern form after a period of pressure, coinciding with higher Street earnings estimates that reflect rising confidence in its ability to monetise demand for AI and data center focused memory solutions.
- The interesting angle is how the upgraded forecasts connect directly to Rambus execution on DDR5, companion chips and high speed IP, which ties analyst enthusiasm back to the underlying commercialization of its technology rather than pure sentiment.
- This analysis considers how the Rambus investment narrative is affected by the hammer pattern that aligns with higher Street earnings estimates.
Scan other AI infrastructure opportunities moving on similar earnings momentum with our hand picked 53 AI infrastructure stocks to compare how Rambus stacks up against peers tied to data center and memory demand.
Rambus Investment Narrative Recap
To own Rambus, you need to believe its DDR5 memory interface chips, companion parts and high speed IP can continue to benefit from AI and data center demand while staying profitable. The main near term catalyst, in the analyst consensus Narrative on Simply Wall St, is the ability to turn that demand into ongoing revenue and earnings expansion despite tight supply chains.
The biggest current risk is margin pressure and cost creep, which has already shown that higher volumes do not always mean stronger profitability. The recent hammer pattern and higher earnings estimates do not change the fact that any squeeze in gross margin or a prolonged antitrust process could weigh on Rambus cash generation.
With no fresh corporate announcements tied directly to this chart move, the most relevant reference point is the recent context of record quarterly revenue of US$207.4 million and guidance for further sequential revenue and EPS growth in Q3 2026. That context is where the current optimism around Rambus is anchored.
For you, the link is straightforward. If Rambus can keep scaling DDR5, companion chips and IP licensing into that AI and data center workload demand, while managing OSAT and DRAM capacity limits and protecting margins, then the current technical bounce becomes one small data point inside a much larger execution story.
Rambus narrative projects US$1.2b revenue and US$474.9 million earnings by 2029, based on analysts assuming 17.4% yearly revenue growth and an earnings rise of about US$235.2 million from US$239.7 million today.
Uncover why Rambus' fair value indicates a 75% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate view puts the LPDDR6 SOCAMM2 launch at the center of the Rambus story, arguing that this extra power management content could justify much faster expansion than consensus assumes. Those bullish analysts were already modeling revenue of about US$2.0b and earnings of US$857.8 million by 2029 before this hammer pattern and estimate upgrades, which shows how far opinions can stretch. You can use that spread between narratives as a prompt to test your own assumptions and see which scenarios feel realistic to you.
Explore 2 other Rambus fair value estimates, including one that suggests there could be as much as 75% upside from the current price!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own research and analysis.
- A great starting point for your Rambus research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Rambus. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Rambus' overall financial health at a glance.
Looking For More Ideas Beyond Rambus?
If the Rambus story has sharpened how you think about risk, upside and execution, use that same lens to scan a wider field of opportunities with the Simply Wall St Screener.
- If capital preservation comes first for you, start with steadier candidates through the 30 resilient stocks with low risk scores and see which businesses line up with your tolerance for volatility.
- If balance sheet strength matters more than headlines, filter for companies with robust finances using the list of solid balance sheet and fundamentals (24 results) and compare how their fundamentals stack up against Rambus.
- If you are hunting for potential mispricings, use the 36 high quality undervalued stocks to spot businesses where quality and valuation may be out of sync.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com