


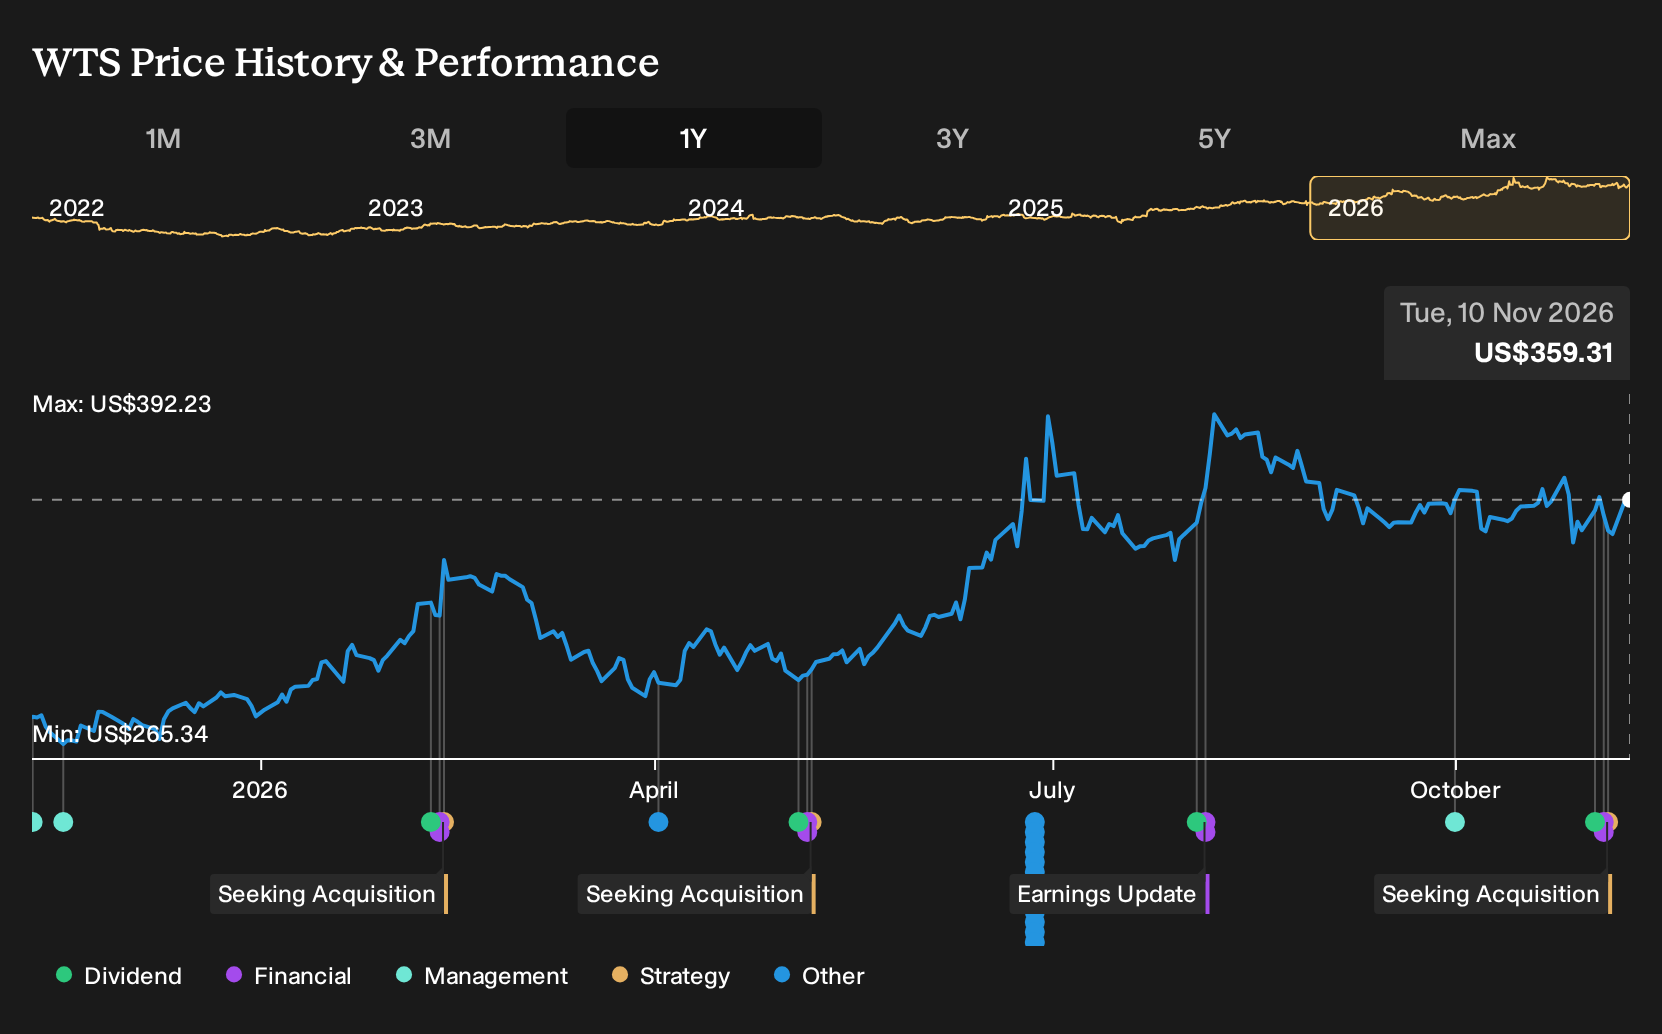
If you had backed the IoT water story instead of the old valves and fittings label, this past year with Watts Water Technologies looks very different. Holding Watts Water Technologies over the past year would have returned 31.3%, including dividends. That gain now sits beside last year’s split analyst calls on saturation risk versus IoT-led renewal. If you were weighing those views on 10 November 2025, which signals would have mattered most for your decision?
A Narrative on Simply Wall St is one investor's written case for a company, with its growth, margin and multiple assumptions spelled out. Those assumptions imply an estimated Fair Value.
Watts Water Technologies is not the only name tied to this theme. Zero in on 41 power grid technology and infrastructure stocks and compare how each one is priced.
The Two Stories Investors Had To Weigh On Watts Water Technologies
The shares cost US$276 at the start of the period, so any investor looking at Watts Water Technologies had to decide which story felt more realistic.
The bullish narrative argued for a fair value of US$293, about 6% above the start price, built on IoT water management, recurring high margin services, and the I-CON Systems integration supporting sustained margin expansion.
The bearish narrative pointed to a fair value of US$225, 18% below the start price, focusing on saturation in North America and Europe and the risk that new efficient building technologies would slowly chip away at demand.
What The Results Changed For The Watts Water Technologies Thesis
Watts Water Technologies posted Q3 2026 revenue of US$728 million and net income of US$145.4 million, up from US$611.7 million and US$82.2 million in Q3 2025, with net margin rising from 13.4% to 20.0%. That pattern supported the bullish story that called for IoT led efficiencies and higher profitability, although margin gains helped both sides because the cautious case still allowed for higher earnings over time.
The lesson is simple: when a forecast depends on better profitability, track net margin alongside sales rather than just watching headline revenue or the share price.
What Watts Water Technologies’ Price Now Asks You To Believe
Watts Water Technologies now trades at US$359 after a 31.3% gain over the past year, so any fresh buyer is paying up for execution. The bullish analyst Narrative on Simply Wall St still sets its Fair Value above the current share price rather than below it.
The Narrative focuses on data center cooling, portfolio reshaping and programs like One Watts as the core drivers. The key question is whether continued expansion in higher margin, data center linked projects can keep offsetting tariff, inflation and geopolitical pressures.
"Accelerating data center cooling demand, with sales to this segment reported at 8% of first half 2026 revenue and the served addressable market estimate lifted to about US$2b, creates scope for Watts Water Technologies to build a larger, dedicated solutions franchise that could influence overall revenue growth rates and operating leverage."
That disagreement has a full argument behind it. → Uncover the higher Fair Value this Narrative argues for
How Could You Get There Earlier?
You may be late to this rally, but that does not have to mean arriving late to every opportunity. Start with companies whose prices leave room for a different view of their future. Here are three trading below our estimates.
- Company 1 - 46% below our estimate - sells full-stack accelerated computing systems that large cloud customers use for AI workloads.
- Company 2 - 42% below our estimate - extends a subscription identity platform from airport fast lanes into broader travel and secure access settings.
- Company 3 - 31% below our estimate - builds a dense, app-driven store network that balances rapid expansion and in-store productivity metrics.
That is three of the list. See the full list of 36 companies trading below our fair value estimates →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com