


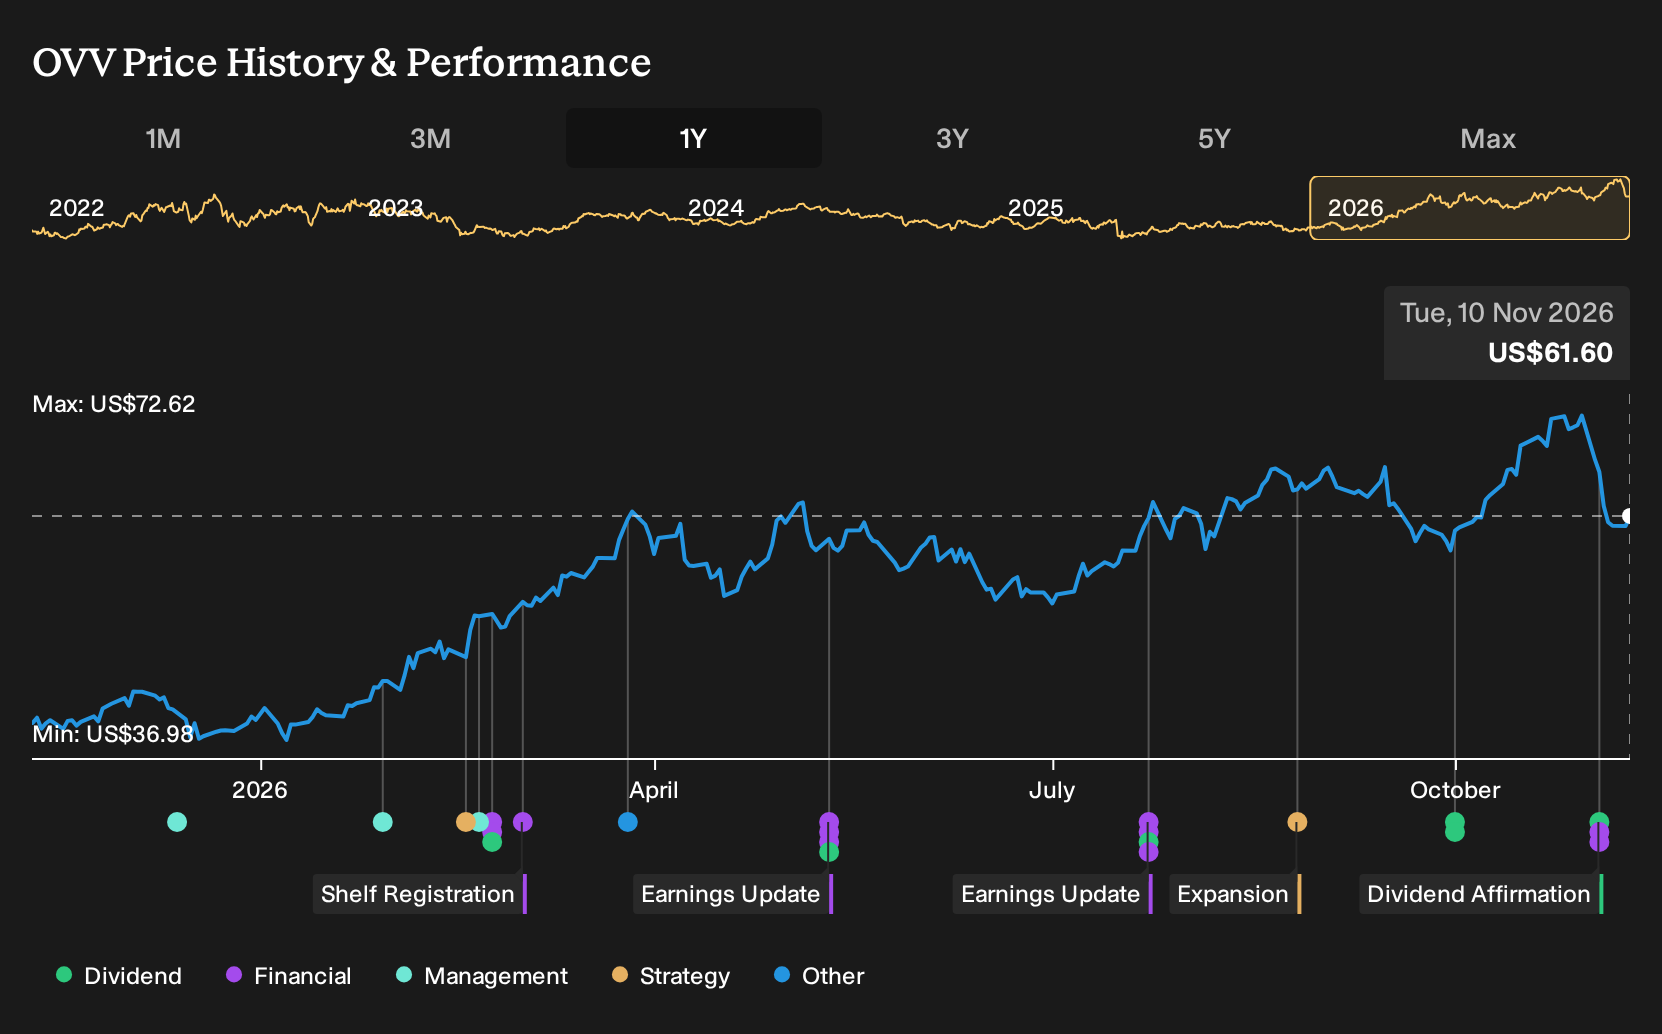
- Ovintiv reported third quarter 2026 revenue of US$2,602 million and net income of US$549 million, affirmed full year 2026 production guidance, and declared a US$0.30 quarterly dividend payable on December 31, 2026 to shareholders of record on December 15, 2026.
- The business paired higher earnings per share with completed buybacks of 13,925,579 shares for US$814.52 million, which reduces the share count and concentrates future dividends and any cash flow per share benefits for remaining investors.
- This article reviews how Ovintiv's investment narrative is affected by stronger quarterly earnings together with reaffirmed 2026 production guidance.
Ovintiv Investment Narrative Recap
To own Ovintiv, you need to be comfortable with a production-led story where efficiency in the Permian and Montney, plus disciplined capital returns, matter more than headline revenue growth. The affirmed 2026 production guidance keeps that thesis intact, since it reinforces volume visibility rather than resetting expectations. For now, the key near term catalyst remains operational execution on those core programs.
The biggest near term risk still comes from potential earnings volatility if commodity benchmarks soften or if further non cash impairments emerge, given the recent large charge earlier in 2026. The latest trading update does not materially change that risk balance; it just gives a clearer line of sight on production levels.
The analyst consensus narrative on Simply Wall St leans heavily on operating gains in the Permian and Montney. In that context, the reaffirmed full year 2026 production guidance looks like the most relevant new datapoint, since it ties directly to those drilling and completion programs and to the long inventory runway analysts have been modeling.
That guidance also matters for how investors think about catalysts such as cost per foot, free cash flow and the ability to fund dividends and buybacks from operations. If Ovintiv delivers production within the guided ranges while holding to the existing capital return framework, it would address the execution questions some skeptics have raised and inform views on whether the current P/E and cash flow based valuations remain compelling.
Ovintiv's narrative projects US$8.9b revenue and US$1.9b earnings by 2029. This implies a 2.4% yearly revenue decline and an earnings increase of about US$980.0m from current earnings of US$920.0m.
Uncover why Ovintiv's fair value indicates a 31% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Some of the lowest ranked analysts focus on the risk that Ovintiv’s recent US$1.2b after tax impairment hints at weaker long term project returns. Those forecasters were only penciling in revenue of about US$7.8b and earnings of roughly US$1.3b by 2029. You can treat this dividend affirmation and steady production guidance as a fresh data point that might eventually shift those more pessimistic views, and then compare both perspectives with your own expectations.
Explore 5 other Ovintiv fair value estimates, including one that suggests it could be worth just $60.00.
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Ovintiv research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Ovintiv. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Ovintiv's overall financial health at a glance.
Looking for more investment ideas beyond Ovintiv?
If Ovintiv has sharpened your view on income, risk and balance sheet strength, use that same lens across a broader watchlist with the Simply Wall St Screener.
- For investors who want potential income plus resilience, start with a curated set of 5 dividend fortresses that aim to balance yield with staying power.
- If value is your priority, use the Screener to narrow in on 36 high quality undervalued stocks that pair solid fundamentals with prices that may not fully reflect them.
- To keep risk in check while still hunting for ideas, filter for 30 resilient stocks with low risk scores and see which businesses align best with your comfort level.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com