


Regeneron Pharmaceuticals (REGN) has put its early liver disease program in the spotlight after first in human data showed that a single CIDEBsiRNA dose reduced liver fat and improved injury markers in MASLD patients.
Regeneron Pharmaceuticals shares trade at US$916.06 after a sharp 22.71% 30 day share price return and a 14.80% gain over 90 days, while a 36.50% total shareholder return over the past year signals momentum building around earnings, the CIDEBsiRNA data and recent capital returns including the dividend and buyback.
Look beyond Regeneron Pharmaceuticals and CIDEBsiRNA by reviewing hand-picked biopharma peers in our 20 high quality undiscovered gems, which couples breakthrough pipelines with solid fundamentals.
After a 36.5% one year total return and fresh excitement around CIDEBsiRNA, the real tension is simple. Does Regeneron Pharmaceuticals still offer enough upside potential to justify the risks at US$916 a share, or has most of the reward already been taken?
Most Popular Narrative: 5% Overvalued
Regeneron Pharmaceuticals closed at $916.06, while the analyst consensus Narrative on Simply Wall St puts fair value at about $869. This implies a modest premium that rests heavily on how the pipeline and partnerships deliver over time.
Regeneron Pharmaceuticals is still advancing a broad late stage pipeline in areas such as immunology, oncology, genetic medicines, and obesity. Continued readouts and regulatory decisions on these programs can add new revenue streams that support earnings growth beyond the current product portfolio.
See why 97 investors see Regeneron Pharmaceuticals as 5% overvalued.
Result: Fair Value of $869 (OVERVALUED)
Still, the Regeneron Pharmaceuticals story can change quickly if retinal rivals pressure EYLEA HD economics, or if legal disputes around Libtayo and fianlimab escalate.
Find out about the key risks to this Regeneron Pharmaceuticals narrative.
Another View: Regeneron Pharmaceuticals Through The P/E Lens
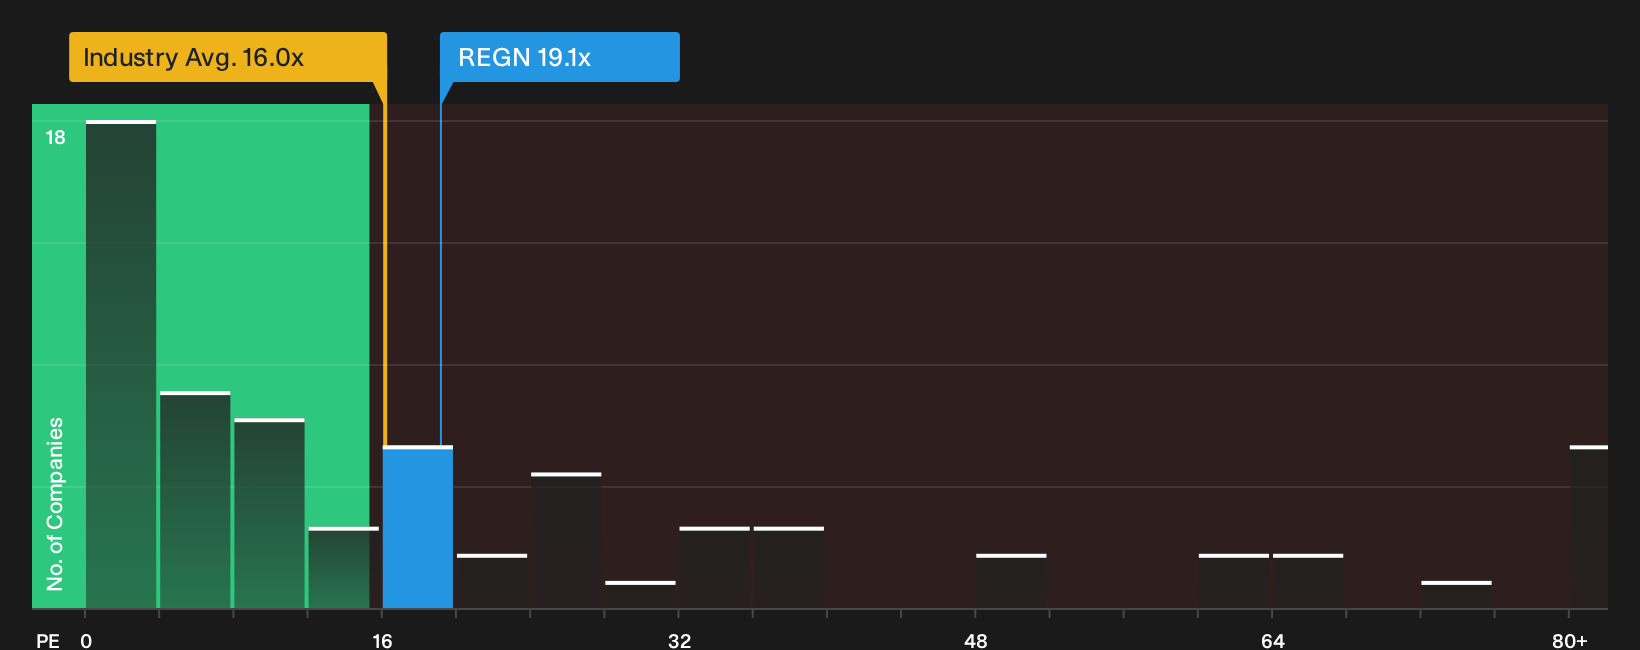
The first fair value estimate pegs Regeneron Pharmaceuticals at about $869, slightly below the current $916.06 share price. On simple valuation ratios though, the picture shifts. REGN trades on a P/E of 19.1x, above the US Biotechs average of 16x yet far below a fair ratio of 30.6x and a peer average of 55.6x. That mix of premium to the sector but discount to peers and the fair ratio raises a practical question for investors. Is the stock being priced for its current pipeline risk, or is the market underestimating how its earnings profile could evolve from here?
To pressure test that P/E gap and see what the numbers imply for upside or downside risk, it helps to unpack the valuation drivers in more detail, starting with our See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around valuation and pipeline risk can be hard to weigh, especially when both caution and optimism show up in the same story. Act quickly by reviewing the full balance of concerns and upsides in the 2 key rewards and 1 important warning sign.
Ready For More Investment Ideas Beyond Regeneron Pharmaceuticals?
Regeneron Pharmaceuticals may already be in your sights, but the next strong addition to your portfolio could be hiding elsewhere. Do not leave those possibilities unchecked.
- Target resilience first by checking companies that prioritize balance sheet strength through our list of solid balance sheet and fundamentals (24 results), so potential shocks hit you less hard.
- Hunt for quality at a discount with the 36 high quality undervalued stocks, where you can focus on stocks that pair solid fundamentals with prices that look out of sync.
- Protect your downside by scanning for steadier performers using the 30 resilient stocks with low risk scores, so you are not only chasing excitement at the expense of durability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com