


Wix.com has seen its share price fall sharply in recent years, which puts a fresh spotlight on a basic question investors keep coming back to. At around US$64.38, is the current valuation of the business adequately supported by its sales today and the revenue it may be able to generate in the future?
- Over the past 5 years the stock has declined 66.9%, which raises questions about how the market now values each dollar of Wix.com's sales.
- The launch of Studio Two, an AI-native visual editor, may support expectations for future sales and could influence how investors think about the durability of Wix.com's revenue base.
- Your read on Wix.com is one view; the desks covering it have another. See what analysts think Wix.com's shares could be worth.
The issue now is whether Wix.com's current share price can be explained by the level and quality of its sales.
If you want to stress test this same sales question across a broader set of AI focused software stocks, take a look at 40 AI small caps
Is Wix.com Still Cheap on Sales?
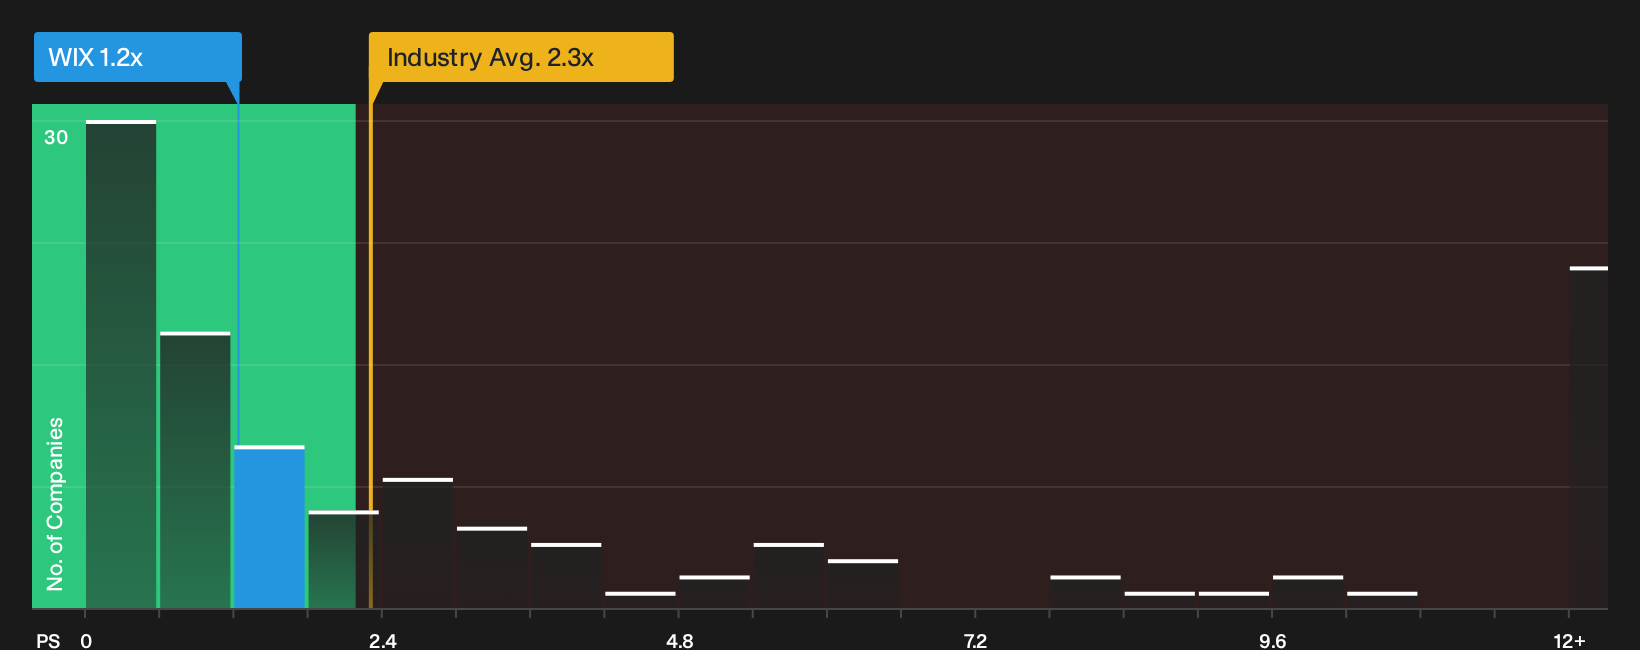
P/S works well for Wix.com because investors often focus on its ability to turn subscription and partner revenue into future cash generation rather than current earnings. On this lens, the stock trades on a P/S of about 1.2x, compared with an IT sector average near 2.3x and a peer group around 2.5x, so the market currently pays far less for each dollar of Wix.com's sales than it does for similar software businesses.
That gap widens against a tailored fair P/S level that our model suggests for Wix.com. This points to the shares trading at a discount to what its growth profile, margins and risk mix might justify. Because the launch of Studio Two and the broader AI push have not prevented concern about the core business after the recent downgrade, this lower P/S also reflects investor questions about how durable those revenues will be. To decide whether that discount is appealing, you need to weigh how much confidence you have in Wix.com's ability to defend and expand its sales base from here. Explore the numbers behind Wix.com's P/S valuation.
The Wix.com Narrative: What Would Justify Today's Price?
Simply Wall St Narratives take the valuation puzzle around Wix.com and turn it into clear, competing stories that explain what would need to happen to future growth, margins and earnings for the stock to be worth materially more or less than today. Each one links its number to a specific view on how Wix.com's growth profile, profitability and risk balance could shift, giving you something you can return to as new results and updates come through.
The Wix.com debate splits sharply between an AI led upside story and concerns that higher costs and legal pressure already sit in the price.
Bull case: 45% undervalued
The bullish analyst Narrative on Simply Wall St argues that Wix.com’s AI stack and cost actions are not fully reflected in today’s valuation.
"The numbers and current valuation suggest that the market assigns limited value to Wix.com’s AI stack, Base44 growth and capital return program, which supports the view that the stock may be undervalued..."
Discover why this Narrative puts Wix.com at 45% undervalued.
Bear case: 29% overvalued
The bearish analyst Narrative on Simply Wall St focuses on whether AI driven spending and legal scrutiny will restrain profit progression.
"Bearish analysts expect Wix.com to struggle to translate higher AI-related operating expenses and legal or regulatory scrutiny into durable margin expansion, which could weigh on the business if growth slows..."
Explore why this Narrative puts Wix.com at 29% overvalued.
For Wix.com, the share price is only one piece of the story
There is another lens that investors often check against today’s valuation: where professional forecasts expect Wix.com to be a few years from now. Explore where analysts expect Wix.com to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com