


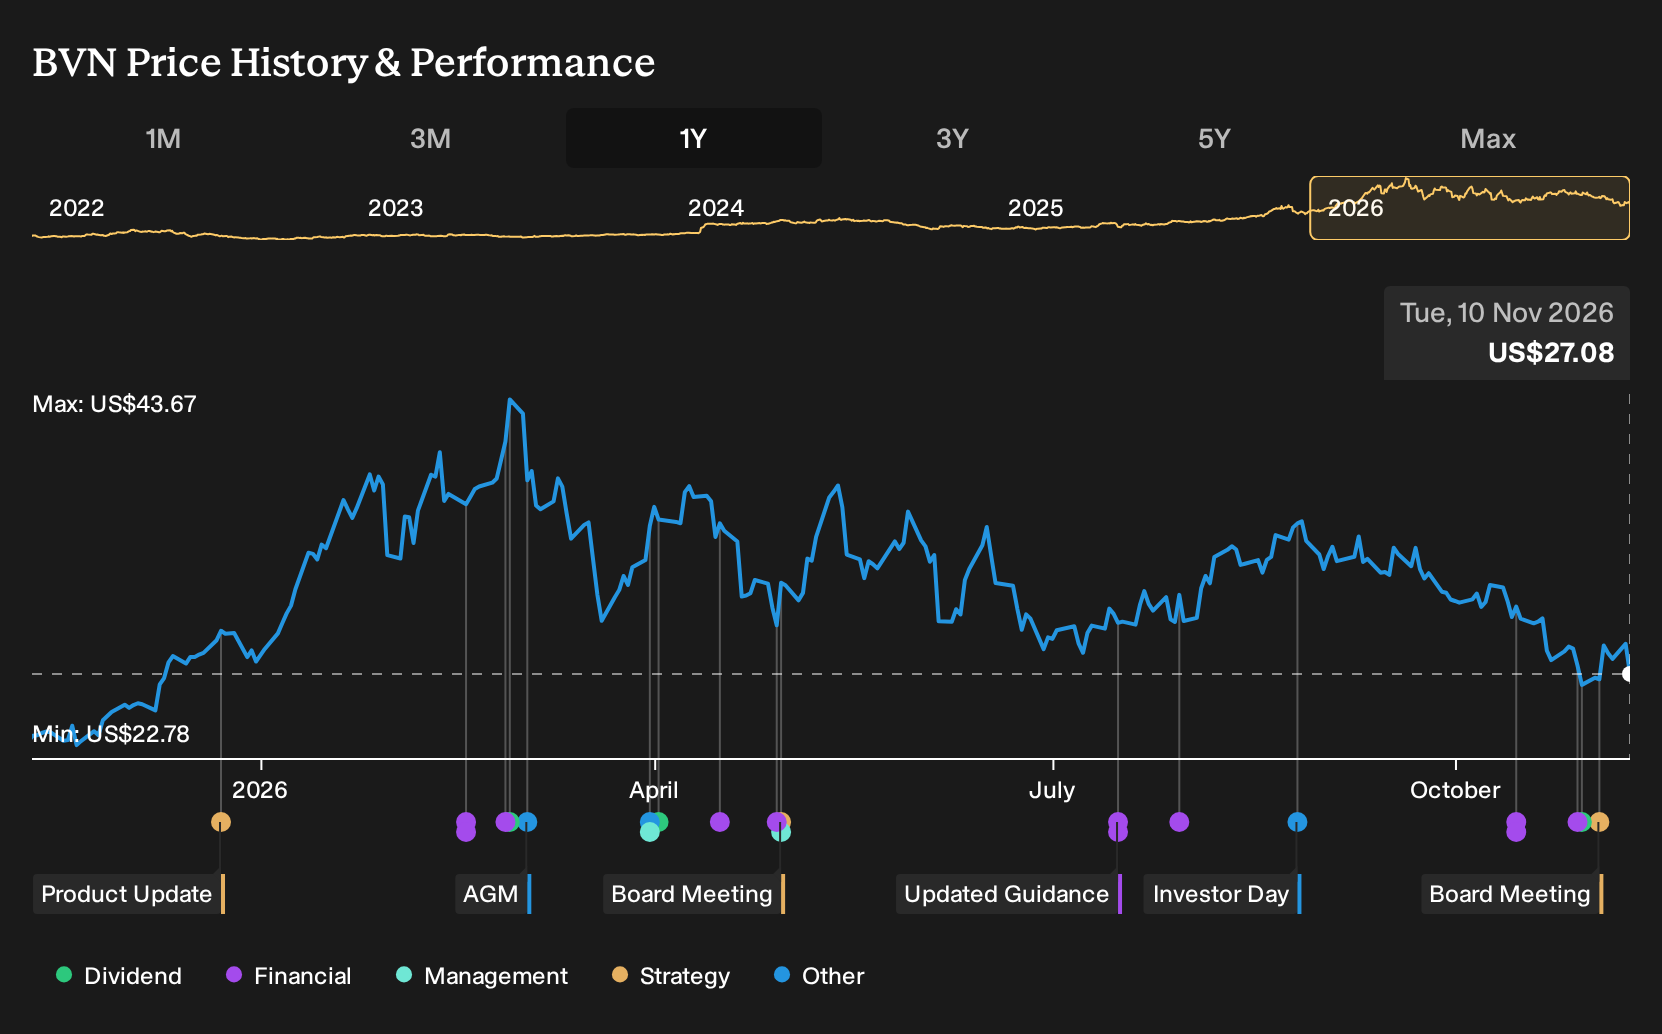
- Compañía de Minas BuenaventuraA reported third quarter 2026 revenue of US$545.33 million and net income of US$245.09 million. Following its October 29, 2026 meeting, the board approved an interim dividend of US$0.5508 per share or ADS.
- The combination of higher earnings for both the third quarter and the first nine months of 2026, together with a fresh cash dividend, highlights how current operations are translating into distributable profits rather than only headline revenue growth.
- We will now look at how Compañía de Minas BuenaventuraA's stronger earnings and new interim dividend could reshape the existing investment narrative.
Compañía de Minas BuenaventuraA Investment Narrative Recap
To own Compañía de Minas BuenaventuraA, you really need to believe its current portfolio and projects can keep turning today’s strong operating performance into consistent cash generation. The latest quarterly results show sizeable revenue and net income, which supports that view in the near term. The main short term catalyst still sits with project execution at San Gabriel, Yumpag and El Brocal and how efficiently those assets run.
The biggest near term risk remains heavy 2026 capex and rising costs across fuel, labor and silver linked contracts eating into that profitability. On balance, this earnings beat and interim dividend do not remove those pressures. They provide more up to date evidence that operations are currently absorbing them.
The most relevant announcement for this update is the interim dividend of US$0.5508 per share or ADS, approved on October 30, 2026. That payout follows higher earnings for both the third quarter and the first nine months of 2026, indicating that recent profits are being shared rather than only recycled into projects.
For you as a shareholder, the key question is whether Compañía de Minas BuenaventuraA can keep balancing sizable capex, cost inflation and its policy of distributing at least 40% of prior year net income. The analyst consensus narrative on Simply Wall St highlights large 2026 spending plans and sensitivity to metals prices, so sustaining dividends at this level still depends heavily on operating delivery and commodity markets.
Compañía de Minas BuenaventuraA's current earnings are about US$1.1b, and analysts expect earnings to reach US$993.2 million by 2029, on forecast revenues of US$2.3b in that same year. This outlook is based on projected annual revenue growth of 1.7%. The consensus implies an earnings decline of roughly US$100 million from today to the 2029 forecast level.
Uncover why Compañía de Minas BuenaventuraA's fair value indicates a 39% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic analysts frame the bigger catalyst as Cerro Verde cash flows and Trapiche potential rather than today’s interim dividend. Before this update, they were pencilling in about US$2.5b of 2029 revenue and US$1.1b of earnings for Compañía de Minas Buenaventura. Those views did not factor in these latest results or the new payout, so you may see forecasts and narratives shift as fresh information is absorbed.
Explore 2 other Compañía de Minas BuenaventuraA fair value estimates, including one that suggests as much as 42% upside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Compañía de Minas BuenaventuraA research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Compañía de Minas BuenaventuraA. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Compañía de Minas BuenaventuraA's overall financial health at a glance.
Looking for more investment ideas beyond Compañía de Minas BuenaventuraA?
Once you have formed a view on Compañía de Minas BuenaventuraA, it can help to scan a wider field of opportunities so you are comparing this thesis against other potential candidates with different risk and income profiles.
- If capital preservation is high on your list, start with companies that screen well on balance sheet strength by running the list of solid balance sheet and fundamentals (24 results).
- If dependable income streams appeal to you, look at businesses with higher yields and consistent payouts through the 5 dividend fortresses.
- If you want to widen the opportunity set and hunt for lesser known prospects, cast a wider net with the 20 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com