


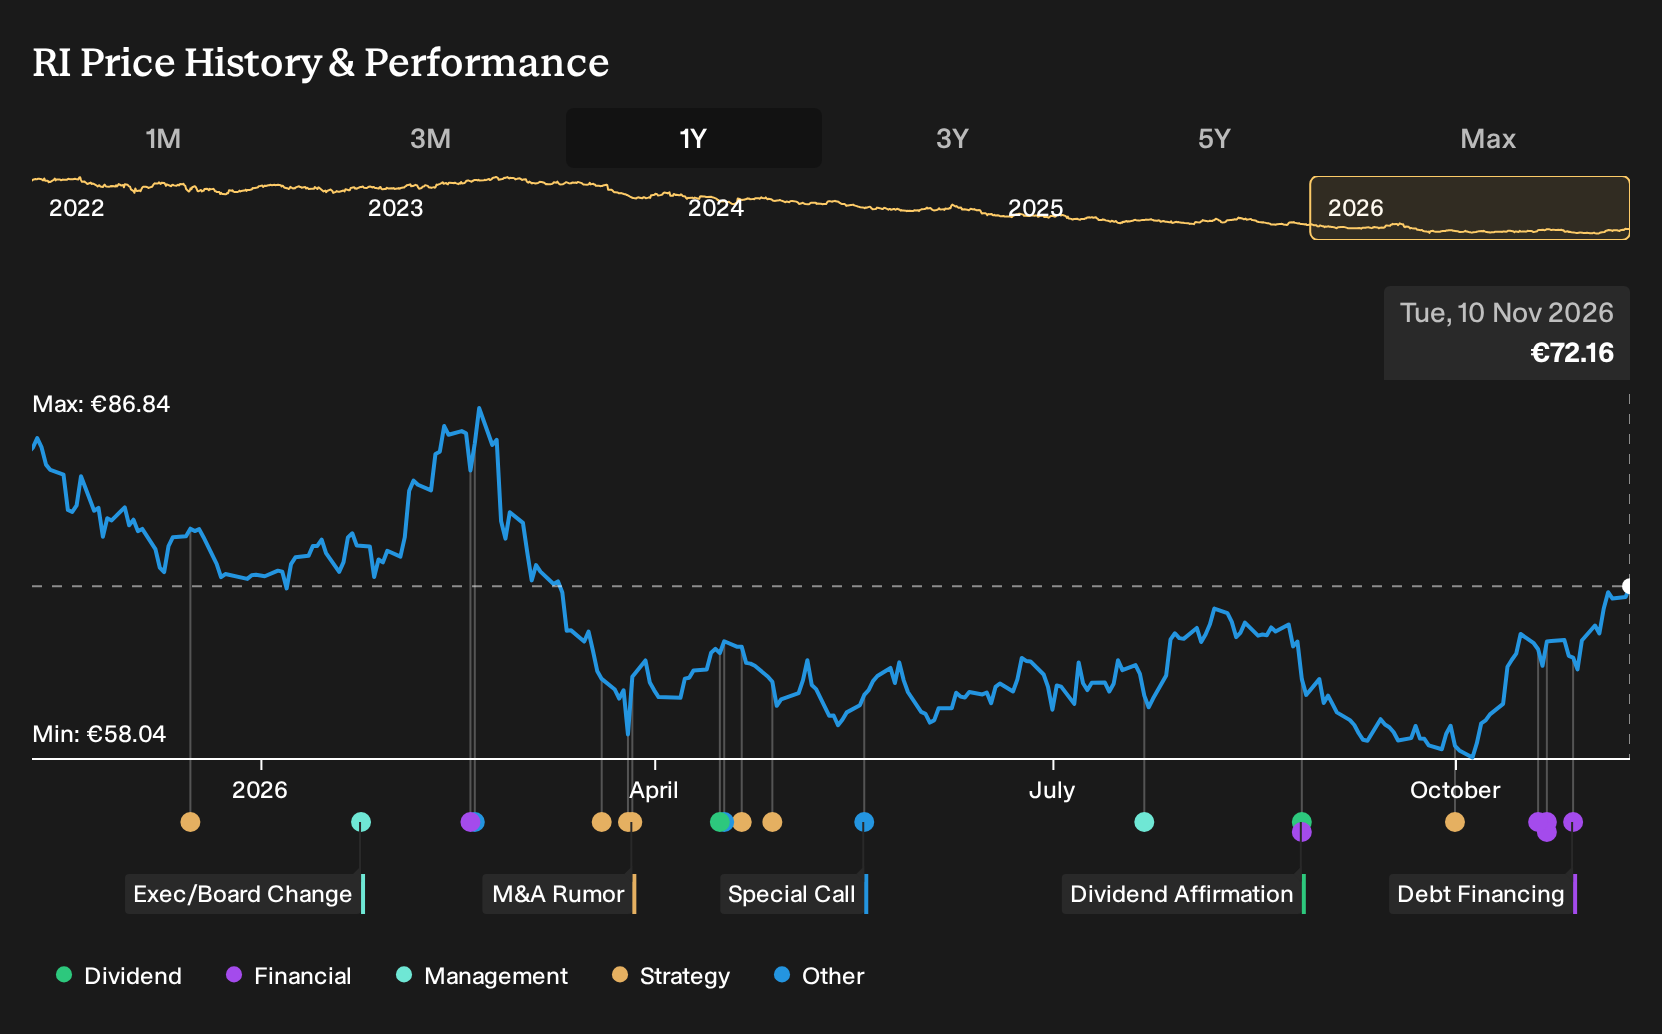
- Pernod Ricard completed a tender offer for several euro bonds issued between 2027 and 2032 and cancelled the repurchased notes, after issuing €1.5b of perpetual deeply subordinated instruments treated as equity under IFRS and listed on Euronext Paris.
- The combination of cancelled debt and equity classified perpetual notes reshapes Pernod Ricard’s capital structure and shifts part of its funding mix away from conventional borrowings.
- We will now see how Pernod Ricard's equity classified perpetual notes could influence its investment narrative around balance sheet planning.
Pernod Ricard Investment Narrative Recap
To own Pernod Ricard, you need to be comfortable with a spirits group leaning on premium brands, efficiency gains and growth in markets like India, while accepting pressure in the U.S. and parts of Asia. The analyst consensus Narrative on Simply Wall St centres on margins holding up as the €1b cost program advances and portfolio reshaping continues.
The latest tender offer and equity classified perpetual notes mostly affect funding, not demand for Absolut, Jameson or Martell. If higher financing costs start to constrain brand spending, the main near term catalyst remains execution in India and ready to drink, while the biggest risk is a prolonged volume drag in the U.S. combined with regulatory setbacks in India.
The equity classified perpetual instruments are the cleanest recent reference point for this tender offer. Management issued €1.5b of deeply subordinated perpetual notes under the EMTN program, split into two tranches with fixed coupons of 5.625% and 6.125%, and accounted them entirely as equity under current IFRS standards.
That move matters for the same balance sheet story investors are watching today. Equity classification helps reported leverage and may support the plan to keep net debt to EBITDA in check, even as earnings have been under pressure and debt is described as not well covered by operating cash flow. For you, the real watchpoints stay the same: execution on the efficiency program, protection of brand equity despite cost cuts and how much financial headroom Pernod Ricard preserves if the weak U.S. spirits market and legal issues in India persist.
Pernod Ricard's narrative projects €9.8b revenue and €1.5b earnings by 2029. This assumes 1.3% yearly revenue growth and an earnings increase of about €300m from €1.2b today.
Uncover why Pernod Ricard's fair value indicates an 11% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Some of the most cautious analysts focus less on India and more on the risk that Pernod Ricard simply uses its new perpetual notes and tender offer to manage leverage instead of reigniting growth. Before this funding move, the lowest forecasts were closer to €9.3b revenue and €1.3b earnings by 2029, so those views may shift once this balance sheet rethink filters through.
Explore 4 other Pernod Ricard fair value estimates, including one that suggests as much as 17% downside from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Pernod Ricard research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Pernod Ricard. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Pernod Ricard's overall financial health at a glance.
Looking for more Pernod Ricard style investment ideas?
If Pernod Ricard's balance sheet moves have you thinking about portfolio construction, it can help to scan a wider field of listed companies that match your preferred mix of resilience, value and income.
- For investors who want quality on sale, review a focused set of opportunities through 199 high quality undervalued stocks that pass strict cash flow and balance sheet checks.
- If capital preservation comes first for you, start with companies flagged for lower overall risk using the 204 resilient stocks with low risk scores tailored to resilience over headline excitement.
- Income orientated portfolios can use 216 dividend fortresses to zero in on higher yielding payers that still clear basic financial health filters.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com