


AXT earnings jump and new guidance reset expectations
AXT (AXTI) has just paired a sharp swing to profitability in its third quarter with fresh guidance calling for GAAP net income of $0.56 to $0.58 in the fourth quarter of 2026.
The semiconductor substrate maker reported third quarter sales of $73.41 million and net income of $25.72 million, compared with sales of $27.96 million and a net loss of $1.91 million in the same period a year earlier.
AXT shares have swung sharply in recent weeks, with the stock down 42.6% on a 30 day share price return and 49.9% over 90 days, even though the year to date share price return is 134.6% and the 1 year total shareholder return is 272.3%. This points to strong long term gains but fading short term momentum as investors reassess growth potential and risks after the latest earnings and guidance reset.
Compare AXT's sharp earnings reset with a curated list of other high quality undervalued opportunities using the 35 high quality undervalued stocks that meet similar fundamental criteria.
The market has crushed AXT in the past three months while analyst targets and intrinsic value estimates point far higher. Where does a reasonable fair value line actually land between those two anchors?
Most Popular Narrative: 57% Undervalued
AXT last closed at $39.31, while the analyst consensus Narrative on Simply Wall St anchors fair value at $91.60 using an 11.51% discount rate. That gap frames AXT as heavily undervalued in that Narrative, with the story leaning on long contracts and aggressive capacity plans rather than short term share price swings.
Accelerating AI data center optical buildouts are tying AXT to long-dated indium phosphide wafer supply agreements that include capacity reservations and prepayments of more than US$90 million through 2031. This structure can support multi year visibility in revenue from high value substrates.
See why 47 investors see AXT as 57% undervalued.
Result: Fair Value of $91.60 (UNDERVALUED)
Still, the AXT narrative leans heavily on export permits and very high P/E multiples, so any permitting setbacks or valuation reset could quickly challenge that upside story.
Find out about the key risks to this AXT narrative.
Another View: What AXT's P/E Is Telling You
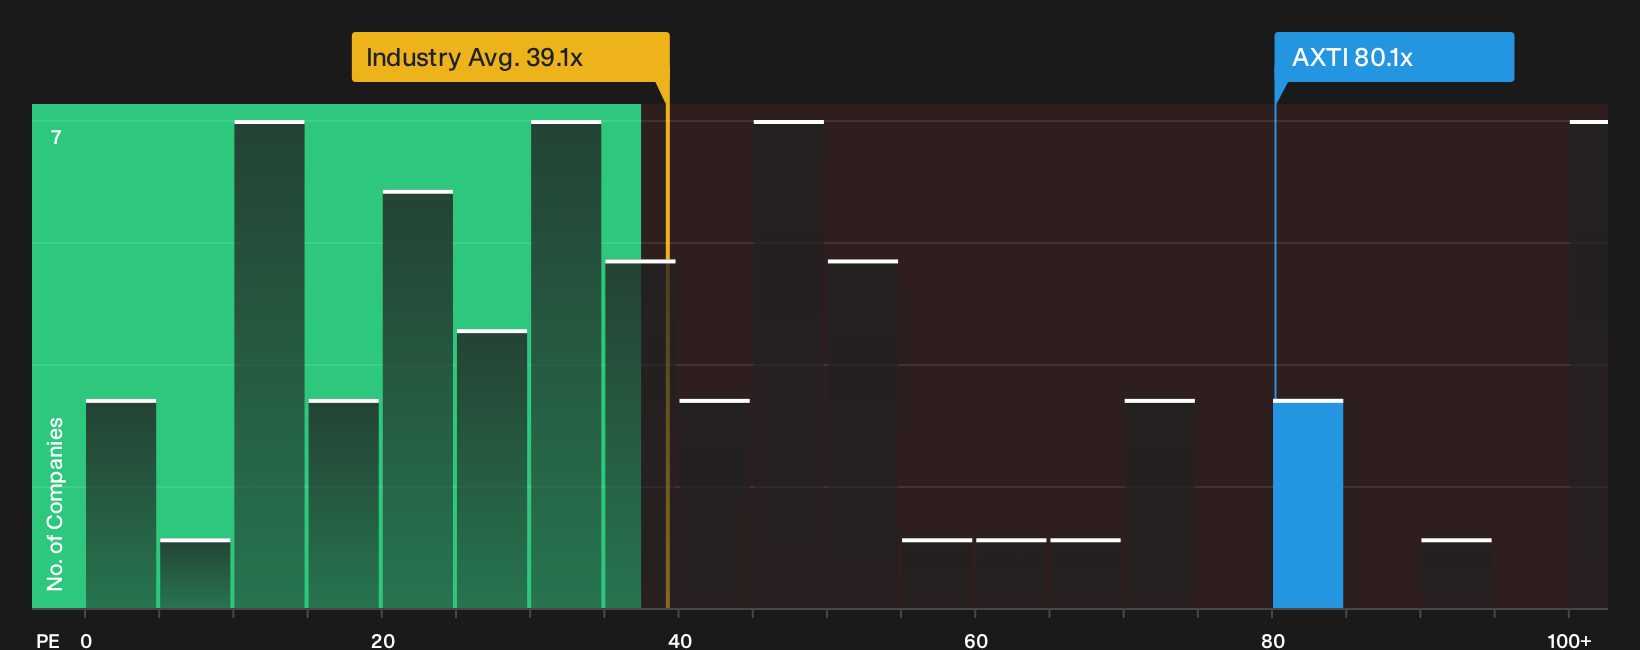
AXT looks cheap on narrative fair value at $91.60, yet the current P/E ratio of 80.1x screens as expensive. It sits above the US Semiconductor industry at 39.1x, peers at 77.5x, and the fair ratio of 77x, which raises a simple question: How comfortable are you paying more than both the sector and the fair ratio for this growth story?
That kind of premium can reward investors if analyst forecasts and cash flow assumptions land close to expectations, but it also leaves less room for error if export permits, capital spending, or margins stray from the script. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on AXT's outlook can tempt you to lean on a single story; however, the smarter move is to weigh both sides and act fast on your own judgment by reviewing the 3 key rewards and 3 important warning signs.
Looking for more AXT-like investment ideas?
If AXT has sharpened your focus on valuation and risk, widen your search now with structured shortlists that surface opportunities you might otherwise overlook.
- Target potential mispricings by scanning a 35 high quality undervalued stocks that combine strong fundamentals with attractive valuations.
- Prioritize resilience by reviewing a list of solid balance sheet and fundamentals (24 results) that can better withstand business shocks.
- Get ahead of the crowd by assessing a 20 high quality undiscovered gems before broader attention pushes prices away from your entry zone.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com