


ZIM Integrated Shipping Services (ZIM) is back on screens after recent data showed its year to date return outpacing the broader Transportation sector, with consensus EPS forecasts moving higher over the past 3 months.
Over the past year, ZIM Integrated Shipping Services has shifted from sharp short term pullbacks to a much stronger overall picture. The share price is still down 6.3% over 30 days and 4.1% over the past week, yet it is supported by an 11.2% 90 day share price gain and a 91.4% total shareholder return over 12 months that signals investors are reassessing both its earnings power and risk profile.
Scan for other Transport names that show similar earnings momentum and sector outperformance using our hand picked list of 20 high quality undiscovered gems to see what else is being quietly repriced.
The 12 month rebound in ZIM Integrated Shipping Services now collides with softer recent price action and sharp earnings swings. Does that mix still offer an appealing entry, or is the valuation already doing the heavy lifting?
Most Popular Narrative: 4% Undervalued
At a last close of $28.10 against a fair value estimate of $29.18, the analyst consensus Narrative on Simply Wall St frames ZIM Integrated Shipping Services as modestly undervalued, with that view resting squarely on how shipping capacity and trade patterns reshape future earnings.
Industry supply growth remains substantial, with global orderbook estimates of around 31% of the fleet and projected deliveries exceeding 3 million TEU in 2027. This could keep freight rates and load factors under strain and in turn cap revenue growth and EBIT for ZIM Integrated Shipping Services even if it adjusts its own operated capacity.
See why 95 investors see ZIM Integrated Shipping Services as 4% undervalued.
Result: Fair Value of $29.18 (UNDERVALUED)
Still, heavy industry wide capacity additions and regulatory scrutiny of the proposed US$35 per share Hapag Lloyd acquisition could quickly challenge that modest undervaluation narrative for ZIM Integrated Shipping Services.
Find out about the key risks to this ZIM Integrated Shipping Services narrative.
Another View: Earnings Multiple Flags A Richer Price
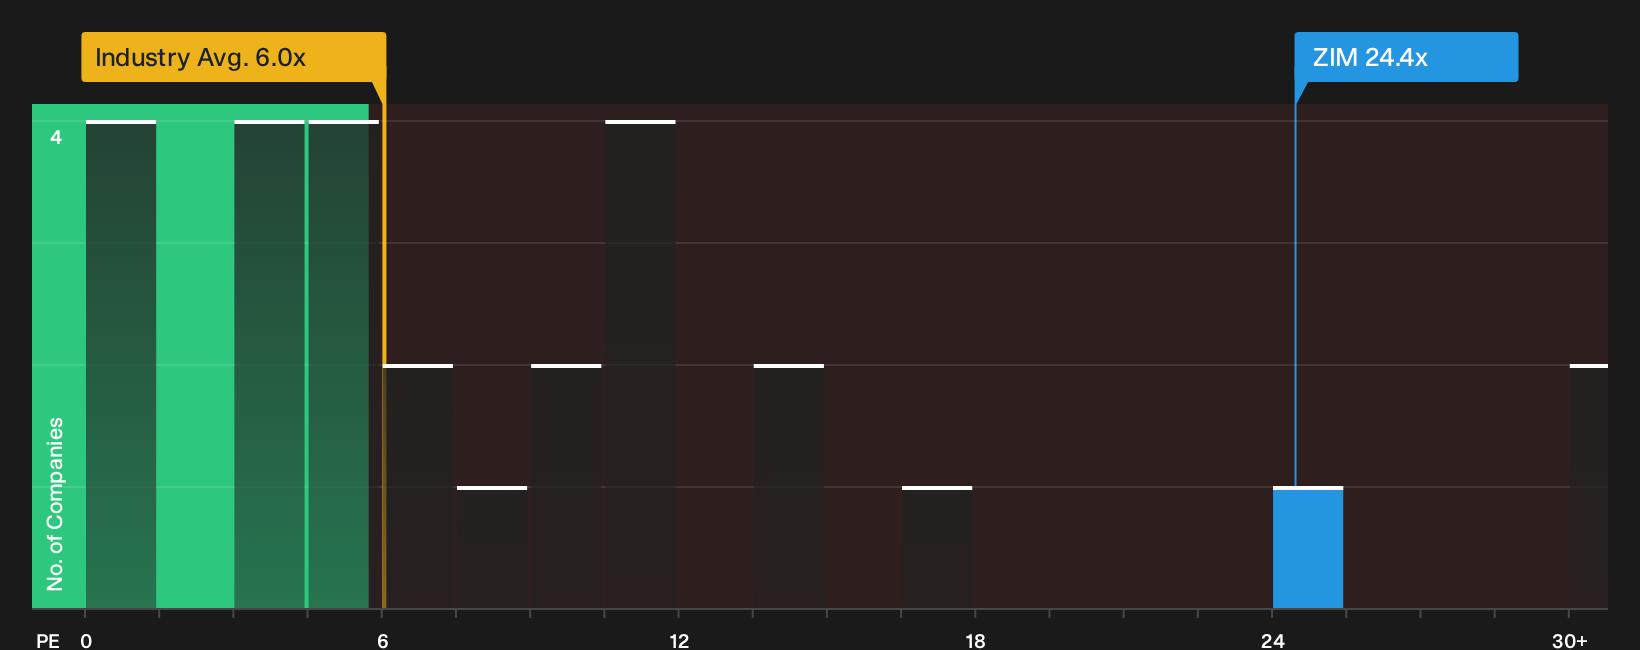
The analyst narrative frames ZIM Integrated Shipping Services as modestly undervalued, yet the simple earnings multiple paints a tougher picture. ZIM trades on a P/E of 24.4x, compared with 6x for the US Shipping industry, 7.9x for peers, and a fair ratio of just 2x. That wide gap suggests investors are already paying up heavily for future profits, which raises a sharper question. Is the market giving ZIM too much benefit of the doubt on execution and the Hapag Lloyd deal, or are analysts being too cautious on what the business can earn?
For a closer look at how this earnings multiple stacks up against sector norms and where the fair ratio sits, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in ZIM Integrated Shipping Services can either signal a warning or present an opening, so move quickly through the data and pressure test the assumptions yourself, including the 4 important warning signs.
Looking for more investment ideas beyond ZIM Integrated Shipping Services?
If you stop with ZIM, you risk missing other opportunities that fit your style, so put the Simply Wall St Screener to work for you today.
- Target potential mispricings across the market by running through our curated list of 35 high quality undervalued stocks that combine quality fundamentals with compressed expectations.
- Focus on resilience first and stress test your downside by scanning 30 resilient stocks with low risk scores that score well on financial health and volatility checks.
- Stay one step ahead of the crowd by reviewing our 20 high quality undiscovered gems before they draw wider attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com