


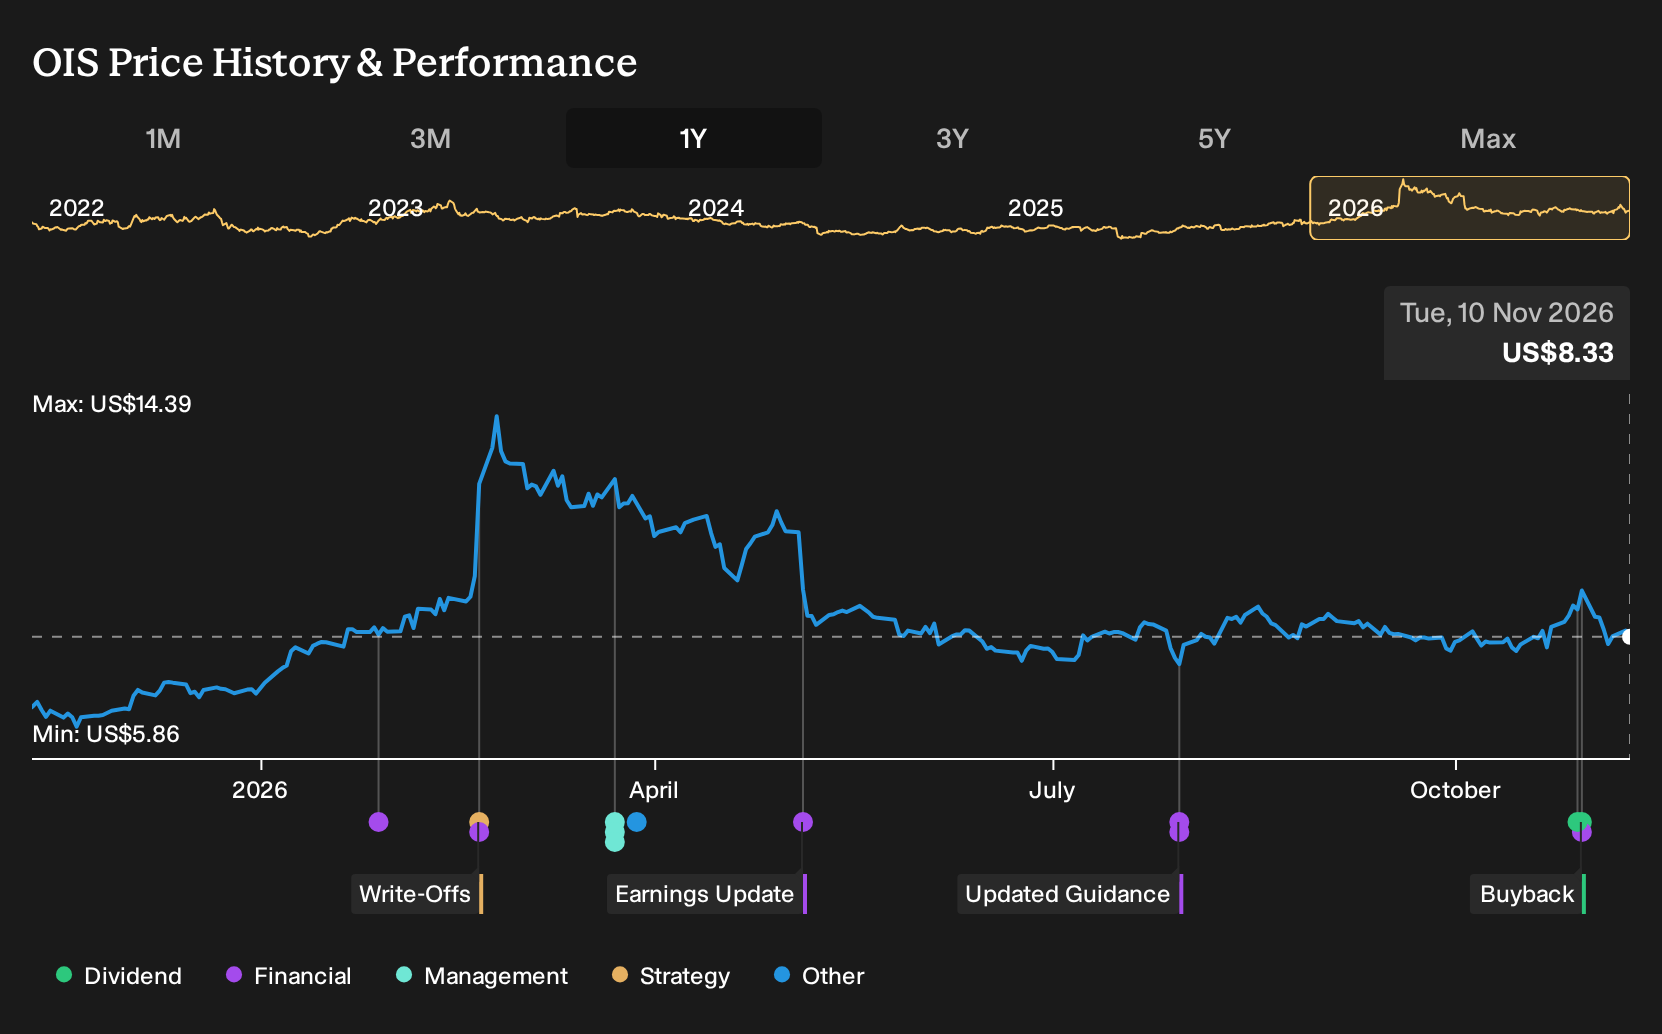
If Oil States International was on your watchlist instead of in your portfolio, the return may sting a little. Holding Oil States International over the past year would have returned 27.4%, including dividends. That outcome invites a tougher question. Back on 10 November 2025, with bulls talking about Asia-Pacific offshore megaprojects and bears warning that ESG policies could shrink oilfield demand, what business assumption about long-cycle offshore spending would have helped you spot the potential before it showed up in your account?
The useful thing about a Narrative is that the reasoning is checkable: the assumptions sit beside the argument, and together they imply an estimated Fair Value you can disagree with.
The easy part of this move is behind Oil States International. Zero in on 35 high quality undervalued stocks for companies trading below our estimates.
The Argument You Would Have Been Weighing Up On Oil States International
The shares cost US$6.42 at the start of the period, and Oil States International sat between two very different stories about long-cycle offshore work and ESG pressure.
On the positive side, the bull narrative saw a Fair Value of US$9, or 40% above the start price. It leaned heavily on offshore megaprojects, assuming revenue growth of 4.6% a year and profit margins reaching 5.3% within three years.
The bearish view anchored on a Fair Value of US$5.5, or 14% below the start price. It focused on rising ESG policies and oversupply risk, while still using the same 4.6% revenue growth assumption but pairing it with a future P/E of 9.3x.
What The Results Changed For Oil States International
Oil States International put a hard number on the thesis when Q3 2026 revenue reached US$169.764 million and net income came in at US$3.01 million. Net margin moved from 1.1% in Q3 2025 to 1.8%, which leaned toward the optimistic case on profitability, although the company was still some distance from the 5.3% margin assumption.
The useful takeaway for other stocks is clear. When a story leans on future margin expansion, treat net margin as the key checkpoint and track whether each new report is closing the gap toward the target or leaving it unchanged.
What Oil States International's Price Now Asks You To Believe
Oil States International trades at US$8.33 after a 27.4% gain over the past year, and the bullish analyst Narrative on Simply Wall St places its Fair Value above that level. The focus is on whether offshore and military backlog plus segment margins can support that view.
The same Narrative argues today's price still does not fully credit the idea that sustained offshore book to bill, higher EBITDA margins and a net cash balance can all persist together. That is the bundle of assumptions any new buyer now has to weigh.
"The main thing that has to go right is that Oil States International converts its long-cycle offshore and military backlog into margins similar to recent segment EBITDA levels while managing input cost pressures and contract timing risks. The numbers imply that the current share price treats Oil States International’s offshore pivot, military awards and net cash balance as offering limited upside compared with what a sustained book to bill of at least 1x and continued free cash flow generation could justify."
One Narrative disagrees with today's price. → See where this Narrative says Oil States International should trade
Looking One Step Beyond Oil States
Oil States gets you thinking about where all that output actually travels. One step away, another business quietly handles the heavy lifting.
Power plants, industrial users and fuel buyers still need molecules moved, stored and processed. That work does not stop just because projects change shape.
A different operator focuses on long distance gas, liquids and crude routes. It also runs the storage and handling that keep those flows usable.
As demand from utilities, power projects and data centers evolves, that network role may matter more than the headline drilling story.
It is written up in full, assumptions and all. → Explore the Narrative that puts this company 26% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com