


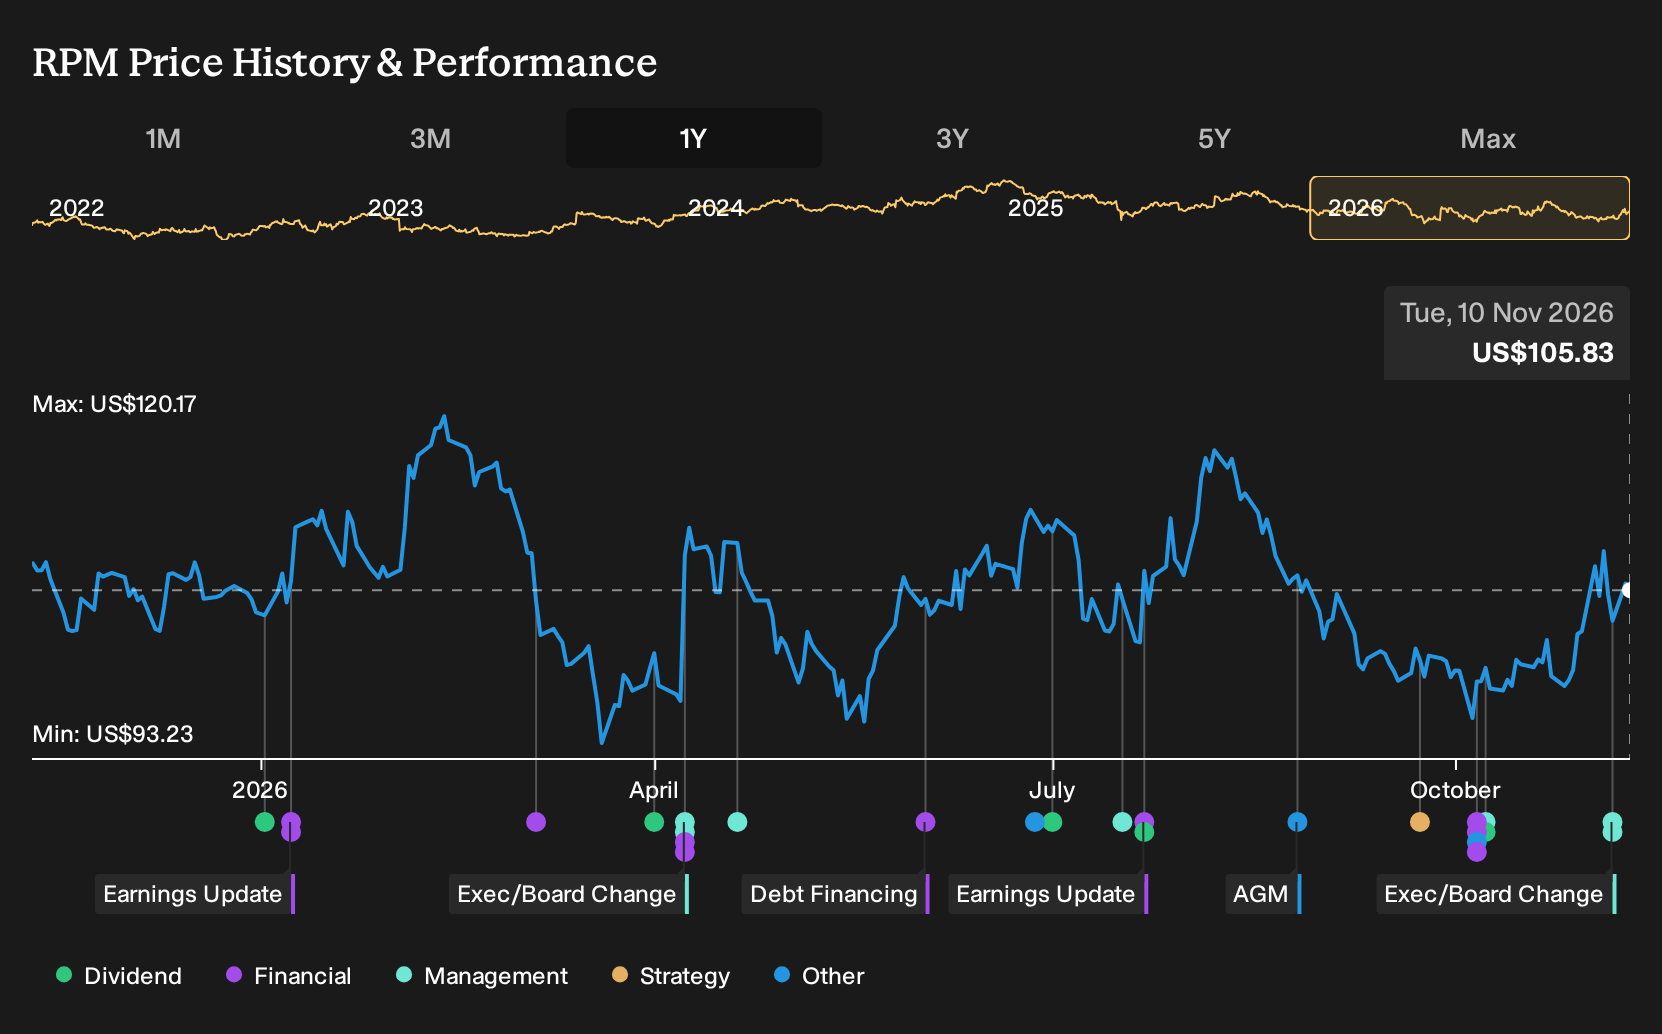
- RPM International reported that long serving Chairman and CEO Frank C. Sullivan plans to retire within the next twelve to eighteen months, with a succession process already underway and an expectation that he will remain as Chair of the Board after a new chief executive is appointed.
- The early and structured CEO transition aligns with RPM International's focus on cost programs and maintenance oriented product platforms. This approach keeps leadership continuity closely connected to execution on MAP initiatives, SG&A efficiency and system selling in high performance building and restoration markets.
- We will now look at how RPM International's planned CEO succession could influence the existing investment narrative built around cost execution.
RPM International Investment Narrative Recap
An investor in RPM International needs to believe the business can keep compounding earnings from maintenance oriented coatings and building solutions while managing costs tightly. The analyst consensus Narrative on Simply Wall St leans on MAP 2025 and MAP 3.0, SG&A optimization and system selling to high performance building customers as the operational engine. The planned CEO transition, with Frank C. Sullivan expected to stay as Chair, does not obviously change those near term levers.
The most immediate swing factor still looks operational. Recovery in the Consumer segment and execution on cost efficiency, including health care and raw material inflation, remain central. The biggest risk is that input cost inflation and structurally higher benefits spending blunt MAP driven savings, especially if DIY oriented demand stays soft while RPM International continues to run with a relatively high debt load.
The retirement timeline for Frank C. Sullivan intersects with an outlook where RPM International is expected to keep pursuing SG&A savings and capital deployment into bolt on deals and growth capex. Those levers, along with share repurchases and dividends, are central to the earnings and cash flow path that underpins analysts’ expectations and the current P/E range.
Board level data shows RPM International has added five directors over three years while still maintaining a seasoned and largely independent board. That mix of continuity and refresh, combined with Sullivan remaining as Chair, can matter for how consistently MAP programs are overseen, how capital allocation disciplines are preserved and how new leadership balances cost initiatives with investment in emerging markets and maintenance, repair and restoration offerings.
RPM International’s current analyst script points to revenues of US$8.9b and earnings of US$969.4m by 2029. This outlook is built on an assumed 3.9% yearly revenue growth rate and a move from US$687.5m of earnings today to that 2029 consensus figure, which is an increase of about US$282m.
Uncover why RPM International's fair value indicates a 17% potential upside to its current price that could close sooner than many investors expect.
Exploring Other Perspectives
Some of the most optimistic analysts anchor their view of RPM International on the idea that plant consolidation friction eases and turns into a cost tailwind. Before this CEO news, they were already pencilling in about US$9.3b of revenue and US$985.2m of earnings by 2029. You might read this and see opportunity. Others may see stretch. Treat this retirement update as a fresh prompt to compare several narratives side by side and decide which assumptions you find most realistic.
Explore 4 other RPM International fair value estimates, including one that suggests as much as 46% upside from the current price!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your RPM International research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for RPM International. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate RPM International's overall financial health at a glance.
Looking for more RPM International sized ideas?
If this leadership update has you reassessing RPM International, it can be useful to scan a wider field of opportunities and compare business quality, balance sheets and income potential side by side using the Simply Wall St Screener.
- For investors who want resilient balance sheets and steady fundamentals to anchor their portfolio, start with a curated list of solid balance sheet and fundamentals (24 results) that meet those criteria.
- If you prefer to focus on stability and lower overall risk, filter for companies in the 30 resilient stocks with low risk scores that align with your comfort level.
- Those looking for income ideas can zero in on potential cash return opportunities by reviewing a hand picked 5 dividend fortresses that already clear a 5% yield hurdle.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com