


Compass (COMP) just delivered a sharp earnings swing, moving from earlier losses to net profit while issuing fourth quarter revenue guidance that points to continued business momentum into the end of 2026.
Compass shares have been volatile around the earnings release, with the stock falling 7.41% on the day even after the swing to profit and fresh guidance. A 6.39% 30 day share price gain contrasts with a 21.52% decline over three months and a very large 3 year total shareholder return that still signals longer term momentum building from earlier lows.
Spot near term movers by comparing Compass with a hand picked 35 high quality undervalued stocks that combines earnings momentum with stronger balance sheets.Compass now has a profitable, growing real estate platform, yet the share price just dropped hard after the earnings pop. Is this still a strong business that the market values sensibly today, or not?
Most Popular Narrative: 20% Undervalued
Compass closed at $9.99 against an analyst consensus Narrative fair value of $12.46, which implies a discount that the analyst consensus Narrative on Simply Wall St ties directly to earnings power and cash generation rather than short term trading swings.
Ongoing realization of Anywhere related net cost synergies, with US$360 million already actioned on the way toward a US$500 million three year target, together with pro forma operating expenses that declined 6% year over year while revenue increased 12% in Q3 2026, points to further operating leverage that could support EBITDA and free cash flow.
See why 16 investors see Compass as 20% undervalued.
Result: Fair Value of $12.46 (UNDERVALUED)
Still, Compass depends heavily on housing transaction volumes. It also faces pressure from MLS and portal policies that could curb agent growth and limit revenue potential.
Find out about the key risks to this Compass narrative.
Another View: Compass On Earnings Multiples
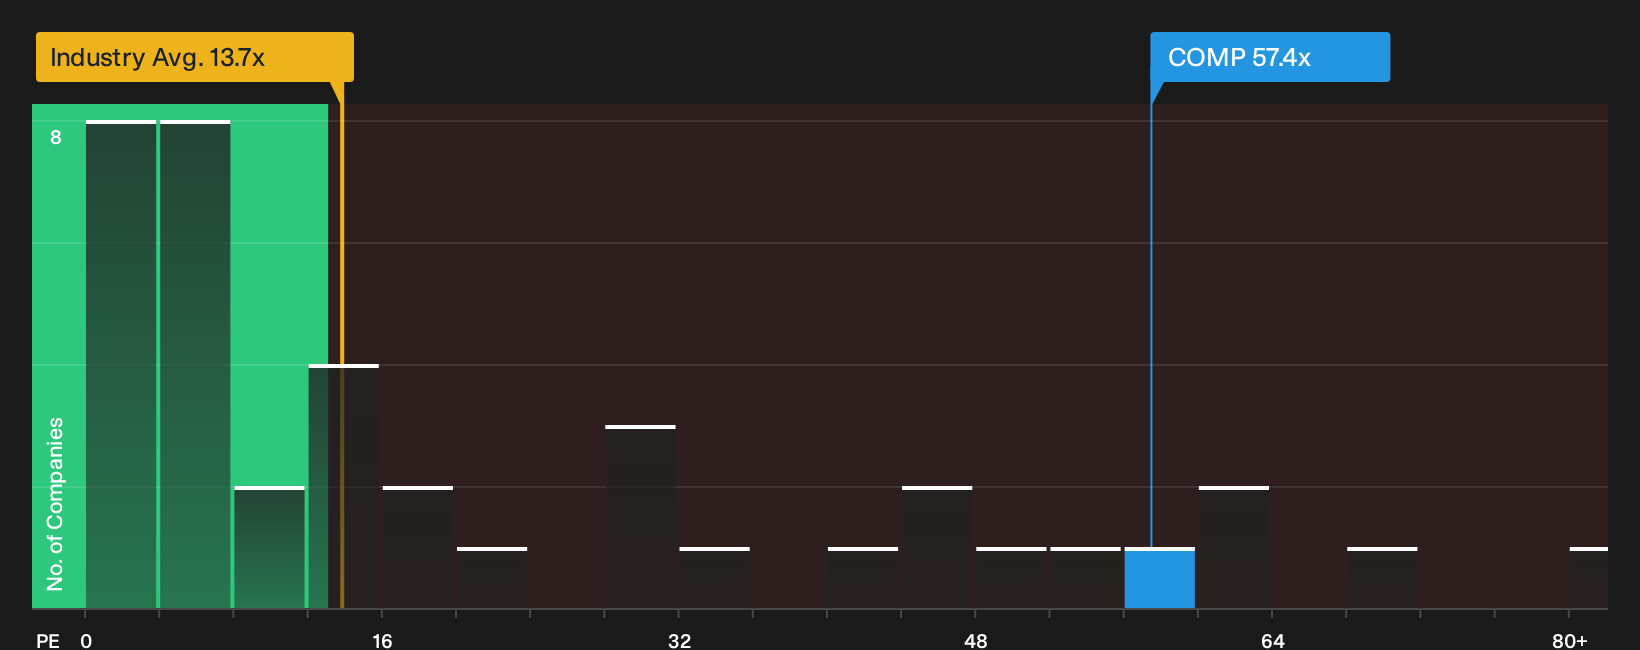
The cash flow story presents Compass as undervalued, yet the earnings multiple suggests something very different. The stock trades on a P/E of 57.4x, compared with a fair ratio of 27.7x, the US Real Estate industry on 14.1x, and peers around 36x.
Those gaps point to rich expectations baked into the current price, which raises a practical question for you as an investor: Is this a premium you are comfortable paying for Compass, given the reliance on future growth and cleaner earnings?
See what the numbers indicate about this price in our valuation breakdown See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Compass can make the story feel messy, so move quickly, review the data, and weigh both the upside and the red flags in detail through the 4 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Compass?
If Compass has you rethinking your portfolio, do not stop here. Broader opportunities sit just a few smart screening choices away, and hesitation can limit your potential results.
- Target dependable income by reviewing companies classed as 5 dividend fortresses that focus on distributing meaningful cash returns to shareholders.
- Hunt for mispriced opportunities through a 20 high quality undiscovered gems that highlights quality businesses the broader market may be overlooking.
- Strengthen your downside protection by using a 30 resilient stocks with low risk scores that filters for resilient companies with cushioning characteristics against shocks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com