


Nissan Chemical (TSE:4021) just posted half year earnings to September 30, 2026, with sales of ¥145,584 million and net income of ¥26,028 million, drawing fresh attention to its recent share performance.
The latest half year figures have landed just as Nissan Chemical’s share price has pulled back sharply, with a 7 day share price return of down 10.27% and a 30 day share price return of down 24.27% from ¥6,884.0. However, the year to date share price return of 28.70% and 1 year total shareholder return of 41.02% still point to solid longer term gains, which suggests the recent slide reflects a reset in expectations and risk appetite rather than a simple reversal in the broader story.
Scan other materials and chemicals stocks showing similar earnings traction and recent share price resets with our hand picked 21 high quality undervalued stocks.
The recent slide in Nissan Chemical raises a simple fork in the road. Does the pullback already reflect the latest results, or do the numbers argue for waiting on a clearer entry point before committing fresh capital?
Preferred Price-to-Earnings of 17.4x: Is it justified?
On valuation, Nissan Chemical trades on a P/E of 17.4x at a last close of ¥6,884, which screens as expensive against both its own fair ratio and the broader JP Chemicals industry, even though some metrics point to quality and growth.
The P/E ratio compares the current share price to earnings per share and gives a simple shorthand for how much investors are paying for each unit of profit. For a diversified chemicals and materials group like Nissan Chemical, the multiple often reflects expectations around steady earnings, return on equity and the perceived reliability of cash flows rather than rapid expansion.
In this case, the stock is described as expensive versus its estimated fair P/E of 15.4x. This implies the current tag is richer than the level some models suggest the market could gravitate toward. The same data also labels Nissan Chemical as expensive relative to the JP Chemicals industry average P/E of 11.1x, a wide gap that signals investors are already paying a premium price for these earnings and that a lot of quality and growth expectations are being priced in.
Explore the SWS fair ratio for Nissan Chemical.
Result: Price-to-Earnings of 17.4x (OVERVALUED)
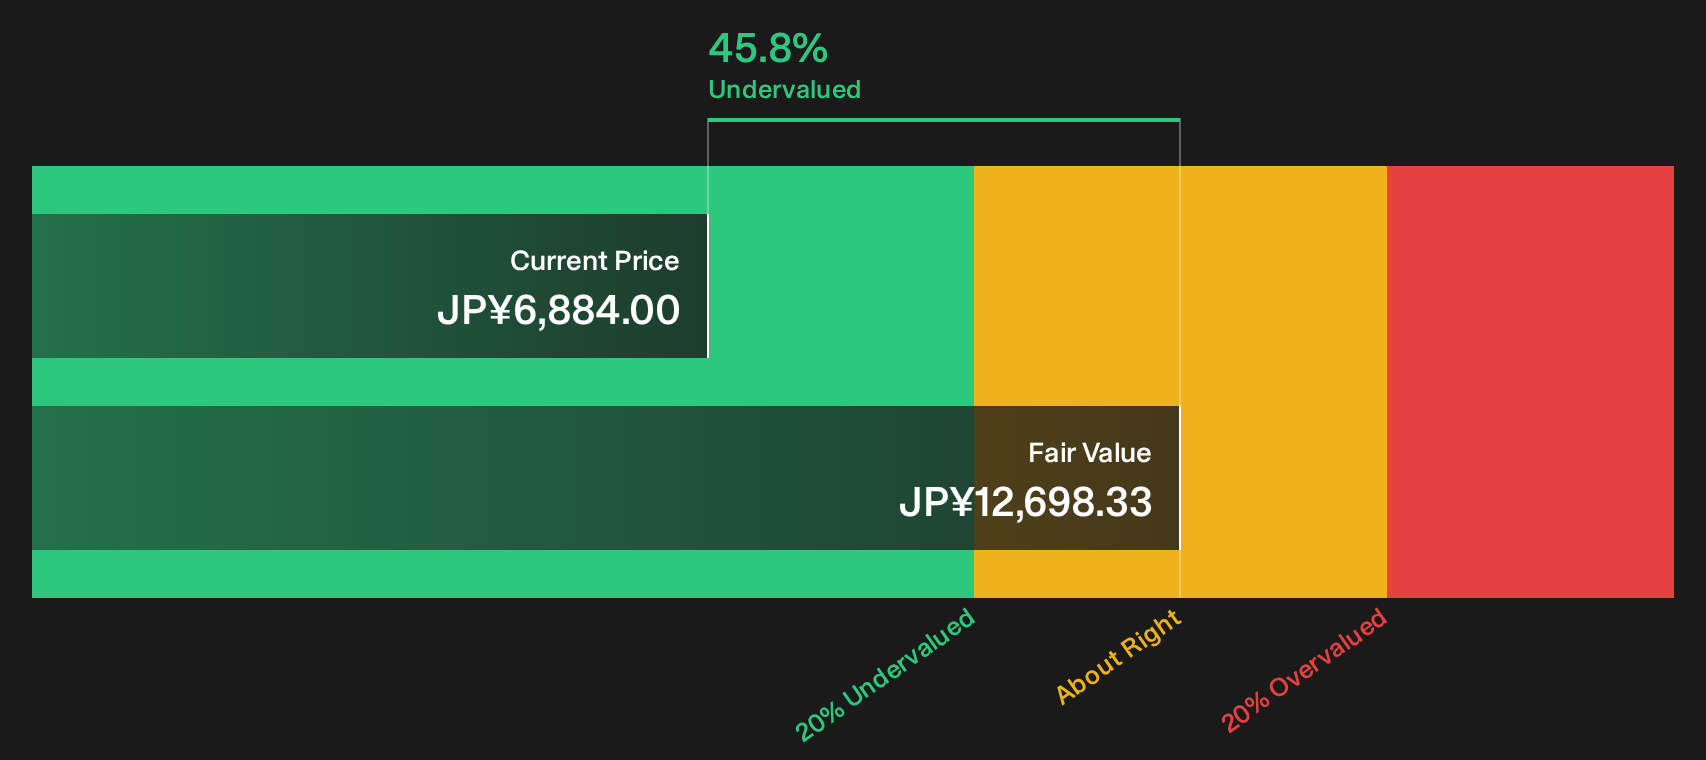
The discounted cash flow lens offers a very different read. Nissan Chemical is flagged as trading at a 45.8% discount to an estimated future cash flow value of ¥12,698.33 per share, versus the current price of ¥6,884. This points to a large gap between the SWS DCF model output and where the market is currently pricing the stock.
Our DCF model projects the business’s future free cash flows and then discounts those back to today using a required rate of return, which produces a single fair value estimate in ¥ terms. This type of framework tends to give more weight to long term cash generation and the timing of those flows, and it can produce a higher figure for a company where earnings quality is described as high, forecast revenue growth is 6.6% per year and return on equity metrics are viewed as strong.
Look into how the SWS DCF model arrives at its fair value.
Result: DCF Fair value of ¥12,698.33 (UNDERVALUED)
Still, a sharp 24.27% one month share price decline, combined with exposure to cyclical chemicals and agricultural demand, could quickly challenge the current Nissan Chemical valuation story.
Find out about the key risks to this Nissan Chemical narrative.
Another view on Nissan Chemical’s value
The earnings based P/E of 17.4x paints Nissan Chemical as expensive, yet the SWS DCF model points in the opposite direction. On that cash flow view, the shares trade at a 45.8% discount to an estimated value of ¥12,698.33 per share, which frames the recent pullback as a potential opportunity rather than a warning. Which lens do you trust more when cash flows and headline multiples disagree?
For a closer look at how that cash flow estimate is built and stress tested, check the Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Nissan Chemical for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 21 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around Nissan Chemical is mixed, with valuation signals pulling in different directions, and that is exactly when your own work matters most. Move quickly, review the underlying metrics for yourself, then pressure test the optimism by digging into the 5 key rewards
Looking for more investment ideas beyond Nissan Chemical?
Do not stop with one ticker when there are far more potential opportunities on the table.
- Target stability first by scanning a 19 resilient stocks with low risk scores that screens for resilience when volatility picks up.
- Hunt for value where quality meets a discount by reviewing a 21 high quality undervalued stocks tailored to strong fundamentals.
- Prioritise financial strength by working through a list of solid balance sheet and fundamentals (23 results) that filters for sturdier balance sheets and healthier cash generation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com