


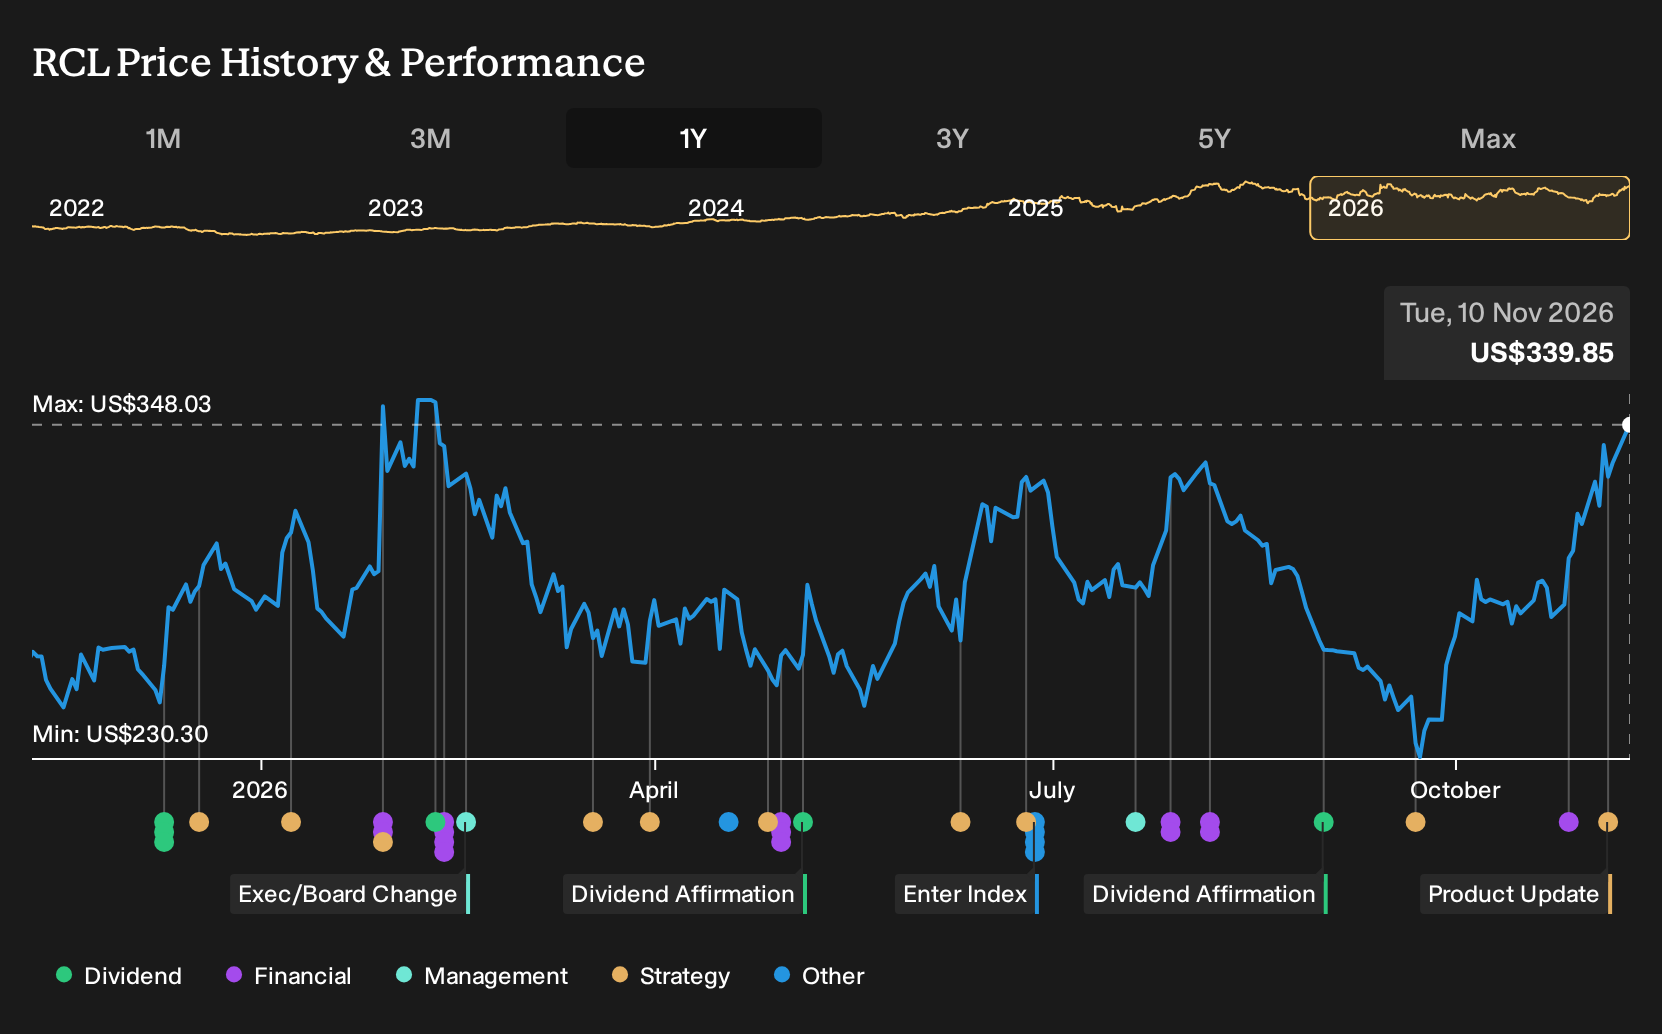
- Royal Caribbean Cruises reported third quarter revenue of US$5.6b with a 9% increase, raised full year adjusted EPS guidance to US$17.85 to US$17.95, and highlighted that falling oil prices and hedging are expected to limit fuel cost impact in the fourth quarter.
- The new 2028 Caribbean and Mexico lineup across 11 ships, including Icon Class vessels and an amplified Symphony of the Seas, deepens Royal Caribbean Cruises' focus on higher value destinations and shipboard experiences that can support onboard spending and yield resilience.
- We will look at how Royal Caribbean Cruises' higher earnings guidance, supported by lower fuel pressure, affects the longer term investment narrative.
Scan beyond Royal Caribbean Cruises and see how other travel and leisure stocks with resilient balance sheets and cash flows stack up in our curated list of solid balance sheet and fundamentals (24 results)
Royal Caribbean Cruises Investment Narrative Recap
To own Royal Caribbean Cruises, you need to believe the cruise model can keep filling a growing fleet at healthy pricing while keeping costs, especially fuel and interest expense, under control. The analyst consensus Narrative on Simply Wall St leans on yield resilience from destination investments and loyalty driven onboard spending. The recent EPS guidance increase, supported by softer fuel, helps that near term earnings story.
The key short term swing factor is still booking strength versus ongoing macro pressure and softer commentary around Mediterranean demand and near term yields. The biggest risk remains a demand or pricing wobble at the same time as fuel or financing costs move against Royal Caribbean Cruises, which would squeeze margins and slow debt reduction.
The 2028 Caribbean and Mexico deployment announcement is highly relevant because it shows where Royal Caribbean Cruises is concentrating capacity and product refresh. Icon Class ships, an upgraded Symphony of the Seas and an amplified Harmony of the Seas are all pointed at high spend itineraries and private destinations like Perfect Day CocoCay.
For you as an investor, that focus ties directly into the catalysts analysts are watching, such as yield support from new vessels, private islands and higher spending repeat guests. It also adds execution risk. Royal Caribbean Cruises needs to sell a larger, more premium heavy program into a consumer backdrop that has already raised questions about pricing power in some regions.
Royal Caribbean Cruises' narrative projects US$24.3b revenue and US$6.4b earnings by 2029. This implies 9.1% yearly revenue growth and an earnings increase of about US$2b from US$4.4b today.
Uncover how Royal Caribbean Cruises' fair value indicates a 3% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic analysts lean on a different catalyst for Royal Caribbean Cruises. They focus on loyalty and digital data. Before this 2028 deployment news, the bullish camp was already pencilling in about US$25.5b of revenue and US$7.1b of earnings by 2029. That is a much richer story than the consensus view, and it shows how far opinions can stretch. Use this new itinerary announcement as a prompt to compare those competing narratives and decide which assumptions feel closer to how you see the business.
Explore 5 other Royal Caribbean Cruises fair value estimates, including one that suggests as much as 76% upside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Royal Caribbean Cruises research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Royal Caribbean Cruises. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Royal Caribbean Cruises' overall financial health at a glance.
Looking for more investment ideas beyond Royal Caribbean Cruises?
Once you have a view on Royal Caribbean Cruises, it can help to widen the lens and compare it with other businesses that fit different risk and income profiles using the Simply Wall St Screener.
- For investors who care most about balance sheet strength and staying power through cycles, start with a list of solid balance sheet and fundamentals (24 results) that keeps financial risk in check.
- If income is the priority, look at stocks in our 5 dividend fortresses that combine higher yields with underlying fundamentals you can assess in one place.
- For those willing to put in extra research in search of less crowded opportunities, scan the 20 high quality undiscovered gems that pair quality metrics with lower profile coverage.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com