


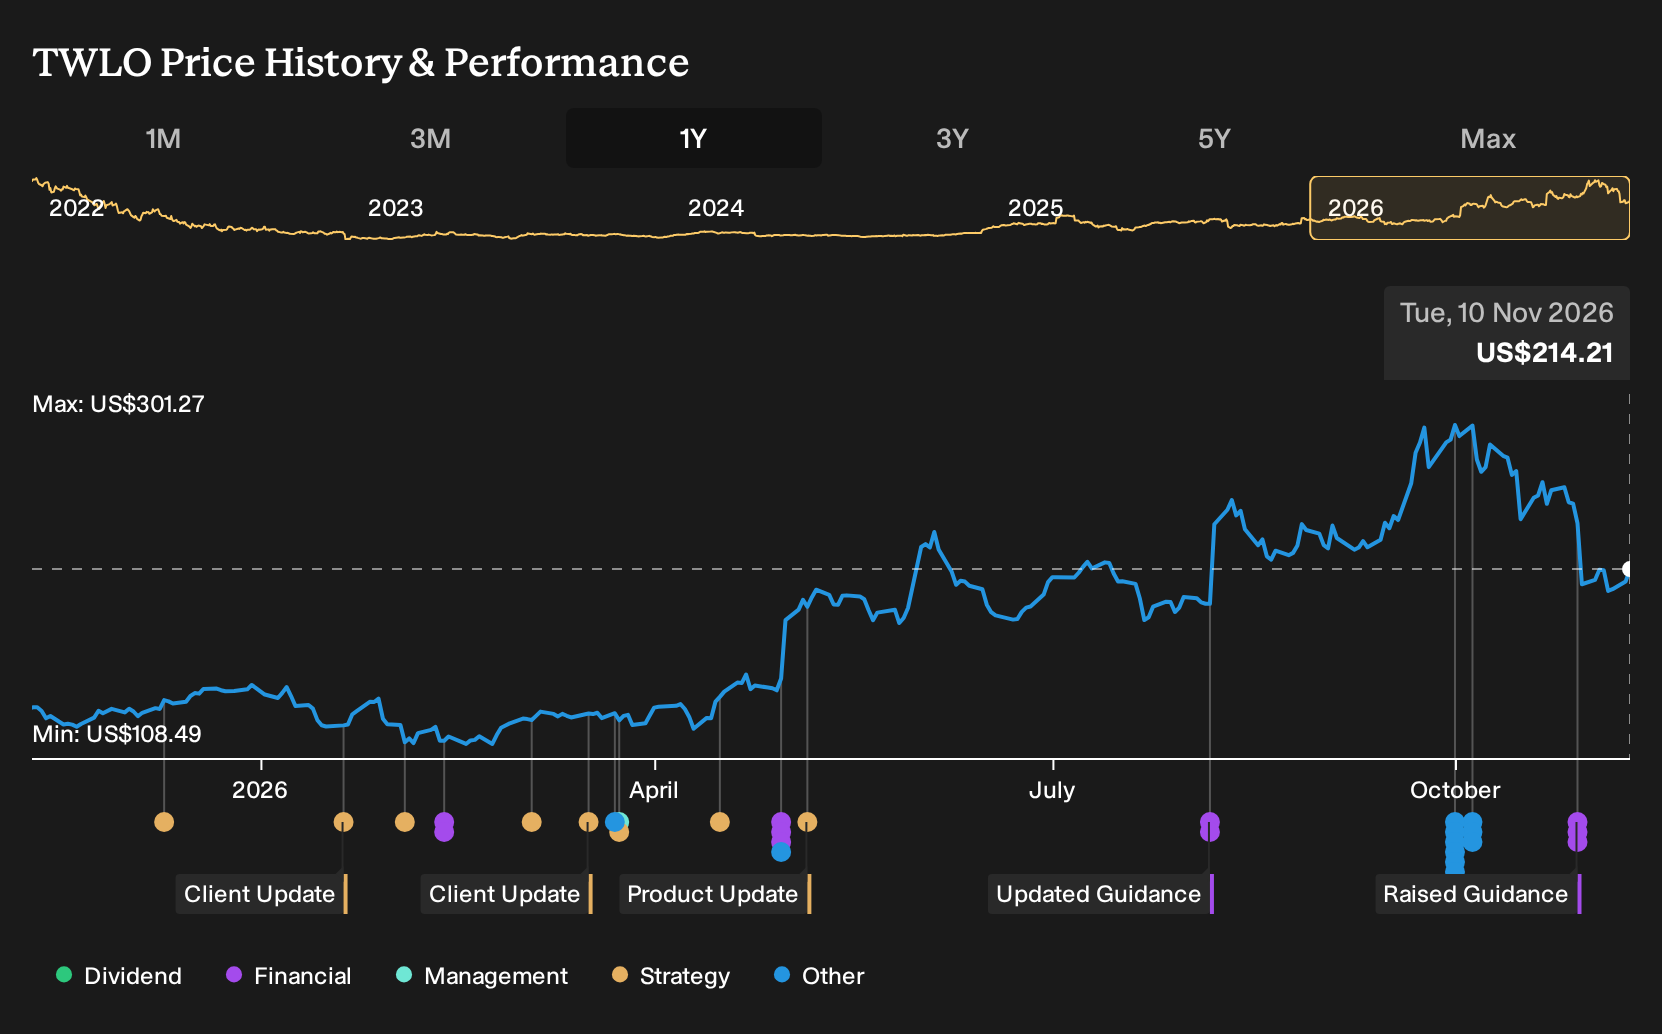
- Twilio reported third quarter 2026 sales of US$1,559.54 million and net income of US$161.16 million, and raised full year 2026 revenue growth guidance to 20% along with a fourth quarter revenue outlook of US$1.595 to US$1.605 billion, implying 17% to 17.5% growth.
- The combination of higher profit, stronger top line guidance, and an AI focused customer insights report points to Twilio leaning further into higher value customer engagement workloads rather than relying only on messaging volumes.
- We will now assess how Twilio's stronger third quarter profitability may reshape the existing investment narrative around growth and margins.
Scan how Twilio's AI driven customer engagement story compares with other potential breakout plays in 53 AI infrastructure stocks across the broader digital infrastructure space.
Twilio Investment Narrative Recap
To own Twilio, you need to be comfortable with a customer engagement platform that still leans on usage-based communications while trying to pull more activity into higher value software and AI services. The analyst consensus Narrative on Simply Wall St already flags that earnings are expected to decline over the next few years, so stronger Q3 profit and raised revenue guidance may not fully resolve that concern.
The near term catalyst is execution on higher margin AI and data driven workloads while keeping messaging costs and carrier fees under control. The biggest risk is that gross margin progress stalls if usage growth again skews toward lower margin traffic or if compliance and regulatory requirements push costs up faster than Twilio can shift its mix.
The most relevant fresh data point is Twilio lifting its 2026 reported revenue growth outlook to 20% and guiding Q4 sales to US$1.595 to US$1.605b. That sits against analyst expectations that revenue grows about 9.9% a year over the next three years, which highlights that the debate is now focused on durability versus one strong year.
For you as a shareholder, that guidance makes the quality of revenue mix and future profitability the key questions rather than headline growth alone. Analysts also expect earnings to decline on average by 33.2% per year from today’s US$1.1b, so how management handles AI customer experience gaps, margin pressures in messaging and software adoption will likely influence whether this guidance is viewed as a peak or a base.
Analysts currently frame Twilio's long term setup around revenue of US$7.6b and earnings of US$452.1m by 2029, which rests on 10.9% yearly top line growth and an earnings decline of about US$647.9m from today’s US$1.1b.
Uncover how Twilio's fair value indicates a 28% potential upside to its current price before the market closes that discount.
Exploring Other Perspectives
One alternate storyline leans on Twilio’s AI mix shift as a stronger long term catalyst than consensus implies. The most optimistic analysts were already pencilling in revenue of about US$8.5b and earnings of roughly US$768.1m by 2029 before this guidance hike. That gap in expectations is wide. It can be used as a prompt to compare several viewpoints.
Explore 3 other Twilio fair value estimates, including one that suggests as much as 52% above the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Twilio research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Twilio. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Twilio's overall financial health at a glance.
Looking for more Twilio sized investment ideas?
Once you have a handle on Twilio, it often helps to widen the lens and compare it with other opportunities that share similar quality markers or risk profiles. A focused stock screener can surface candidates that match your criteria in minutes instead of hours.
- If you care most about price and quality working together, use our tool that highlights a curated 35 high quality undervalued stocks where solid fundamentals meet compressed expectations.
- If balance sheet strength is at the top of your checklist, scan a list of solid balance sheet and fundamentals (24 results) that can help you spot businesses with room to invest through different market conditions.
- If you prefer to hunt for less crowded opportunities, filter through a 20 high quality undiscovered gems that might not yet be on every investor's radar but still show strong underlying metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com