


- Amprius Technologies reported third quarter 2026 sales of US$39.15 million and a net loss of US$3.5 million, with basic and diluted loss per share from continuing operations at US$0.02.
- Over the first nine months of 2026, Amprius Technologies recorded US$101.71 million in sales and reduced its net loss to US$11.7 million, reflecting how higher battery demand is starting to scale through the income statement.
- Investors will be watching how this stronger revenue base and narrower loss profile influences Amprius Technologies' investment narrative.
Amprius Technologies Investment Narrative Recap
To own Amprius Technologies, you need to believe its silicon anode batteries can become a standard choice for high performance aviation and mobility uses, and that production capacity can keep up with contracted demand. The latest quarter shows higher sales alongside a smaller loss, which supports that scaling story but does not change the fact the business is still loss making.
In the near term, the key catalyst is how quickly Amprius Technologies can convert existing contracts and grants into efficient, NDAA compliant output. The biggest risk remains execution against high expectations, including scrutiny from short seller allegations and a rich P/S multiple that leaves little room for missteps.
The analyst consensus Narrative on Simply Wall St points to several operational levers around this earnings print. Large drone orders, the IBAS grant for U.S. capacity and more than 2 GWh of contracted third party manufacturing are all meant to support higher volume and better unit economics as revenue builds.
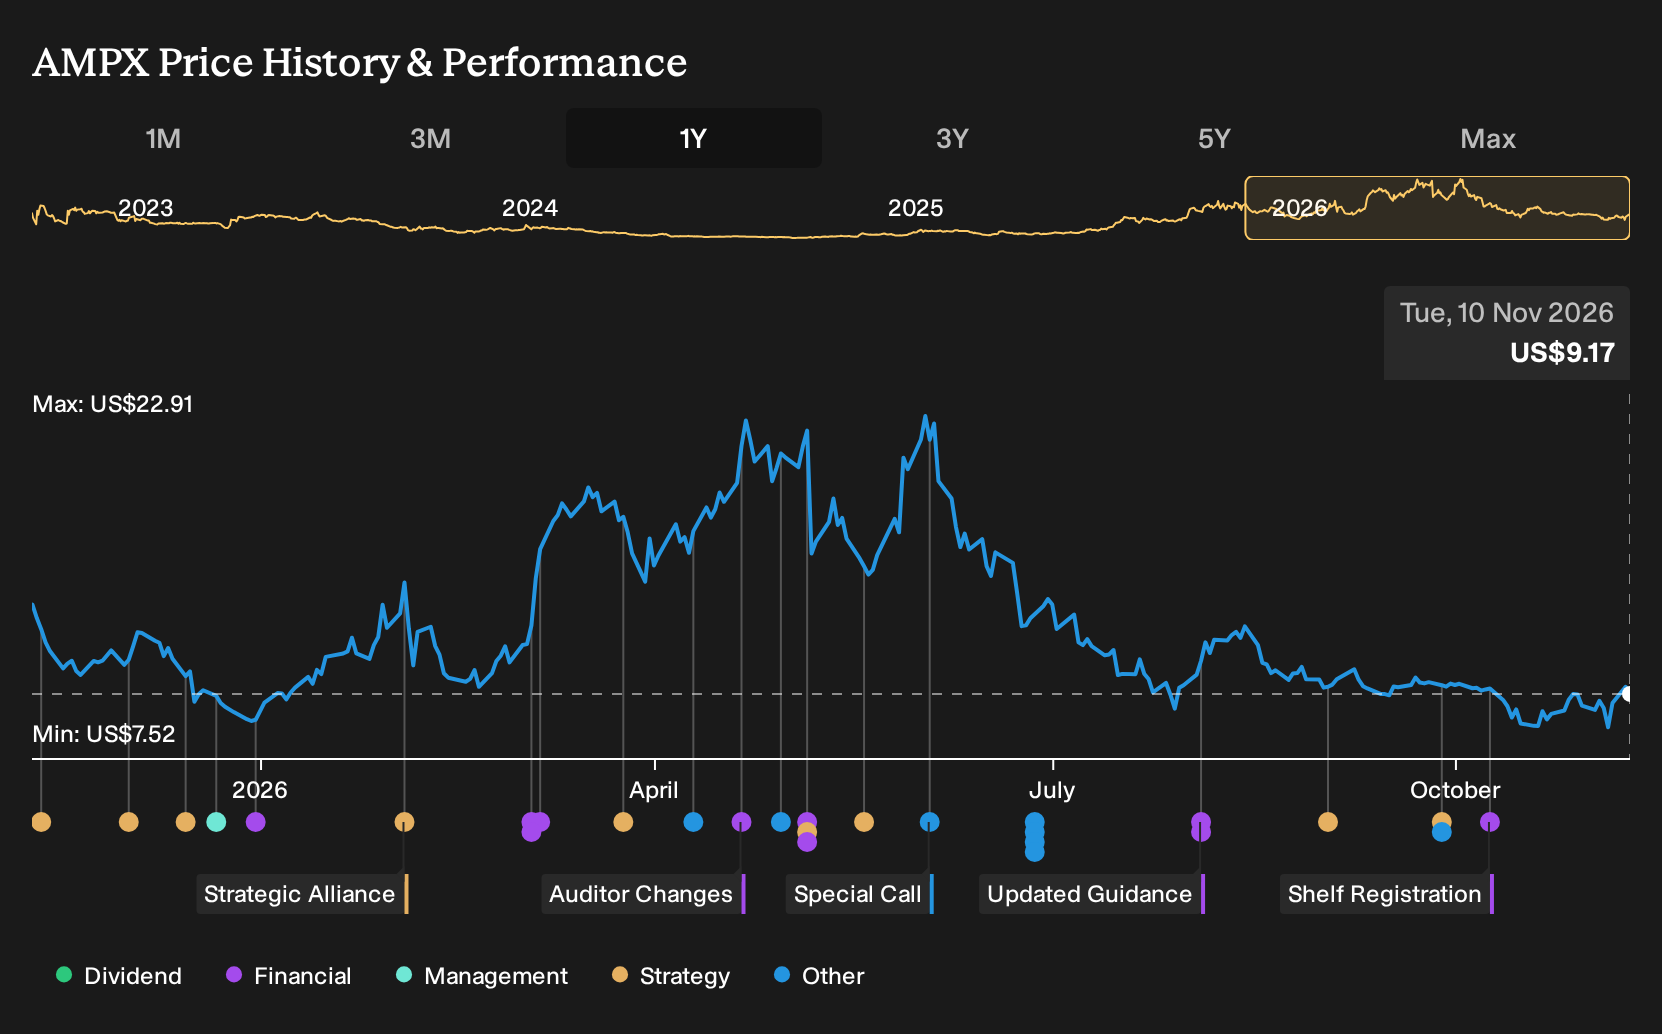
Against that backdrop, this earnings update gives you fresh data on whether Amprius Technologies is moving toward that scale story or stalling. Sales over the first nine months of 2026 reached US$101.71 million and the loss narrowed to US$11.7 million, which investors can compare to those longer term catalysts, the Stark Future agreement and new products like SiCore500 when judging execution risk.
Amprius Technologies' narrative projects US$414.4 million revenue and US$61.0 million earnings by 2029. This assumes 56.0% yearly revenue growth and an earnings increase of about US$99.4 million from current earnings of a US$38.4 million loss.
Discover how Amprius Technologies' fair value indicates a 141% potential upside to its current price, which could close faster than many investors expect.
Exploring Other Perspectives
One alternate view leans hard into Amprius Technologies' NDAA compliant buildout as the real swing factor. Bullish analysts were modelling about US$566.8 million of revenue and US$115.5 million of earnings by 2029 before this report. That is far more optimistic than the consensus path, and could shift again once this quarter is fully digested.
Explore 4 other Amprius Technologies fair value estimates, including one that suggests potential upside of up to 269% from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Amprius Technologies research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Amprius Technologies. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Amprius Technologies' overall financial health at a glance.
Looking For More Investment Ideas Beyond Amprius Technologies?
Once you have formed a view on Amprius Technologies, it can help to compare that thesis with other opportunities that share similar qualities or different risk profiles. The Simply Wall St Screener lets you move from a single story to a watchlist of candidates that match the kind of balance sheet strength, income profile or upside potential you care about most.
- If capital preservation is high on your list, focus on companies with steadier profiles by scanning a set of 30 resilient stocks with low risk scores that may better fit a cautious approach.
- If you want ideas where financial resilience and funding capacity are front and centre, filter for businesses with stronger finances using our curated list of solid balance sheet and fundamentals (24 results).
- If you are hunting for under followed opportunities with healthier fundamentals, broaden your research with a targeted sweep of 20 high quality undiscovered gems that might not yet be widely discussed.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com