


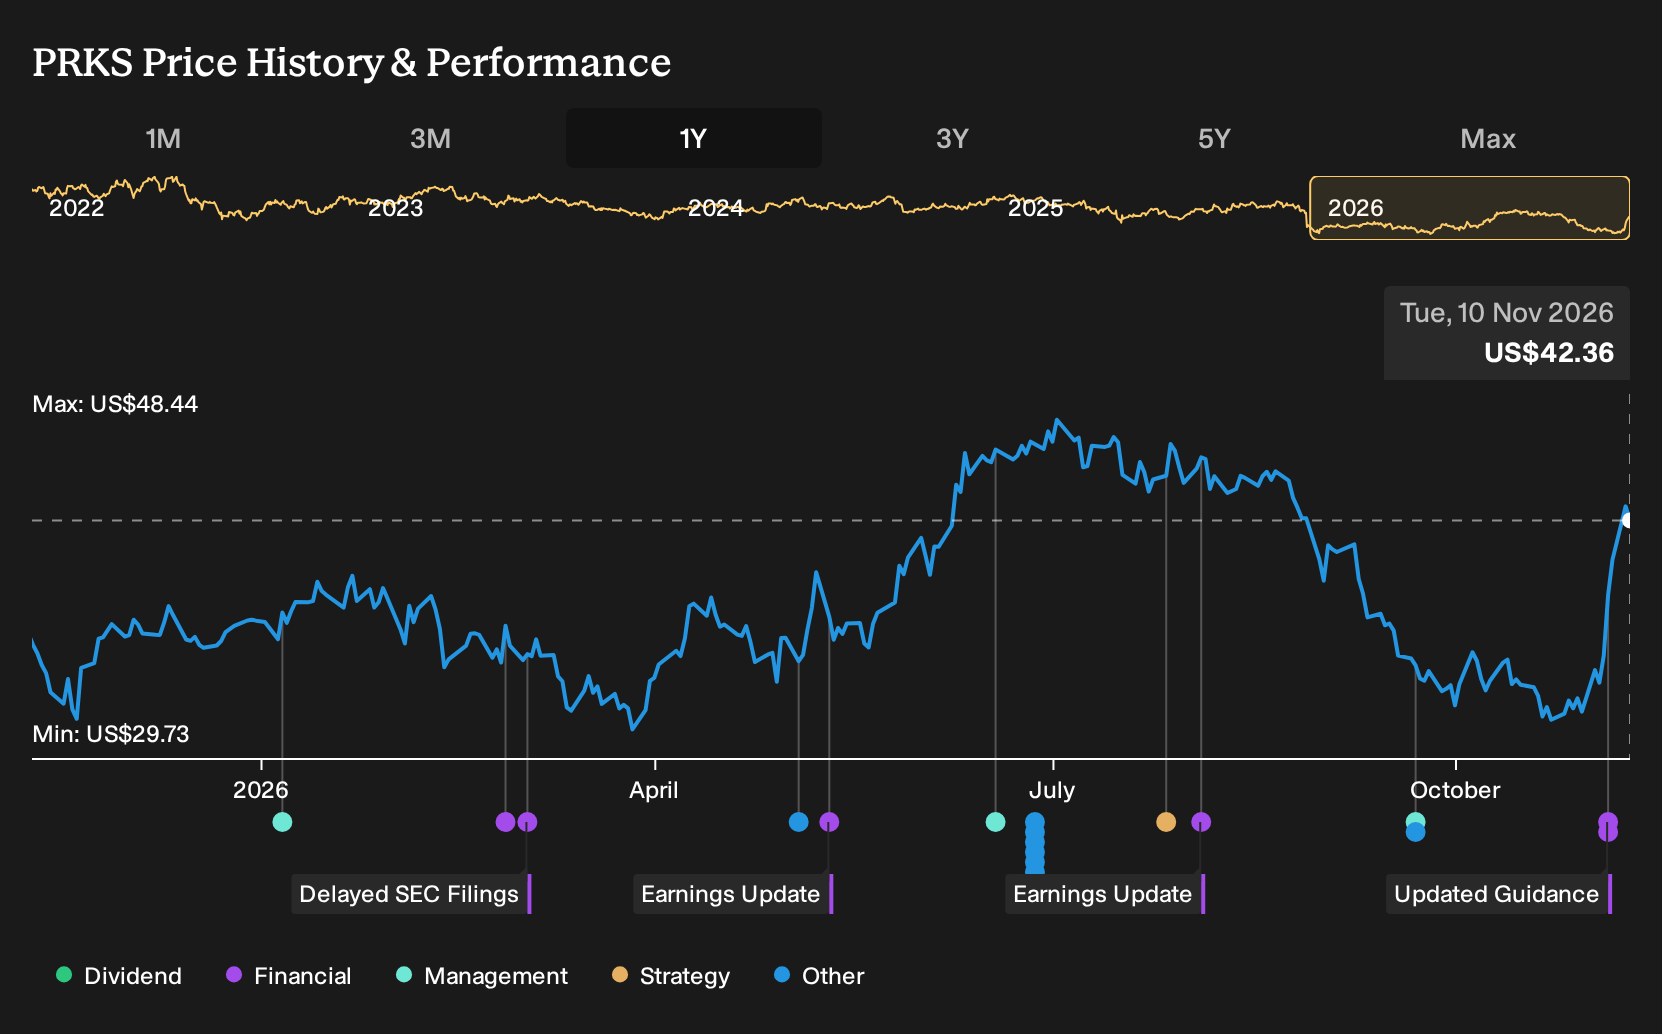
- United Parks & Resorts reported Q3 2026 revenue of US$506.46 million and net income of US$79.97 million, both lower than a year earlier, as weather disruptions and fewer promotional admissions weighed on attendance, even though earnings per share from continuing operations were higher.
- Management paired this softer quarter with 2027 guidance that outlines a clear path to significantly higher revenue. Nearly 8% growth in pass sales also suggests a shift toward more recurring, prepaid visitation.
- The focus now turns to how United Parks & Resorts' investment narrative holds up in light of weaker Q3 fundamentals and management's higher revenue ambitions.
Look beyond United Parks & Resorts' guidance and earnings miss to see how other companies with resilient cash generation and balance sheets compare in our hand picked list of solid balance sheet and fundamentals (24 results)
United Parks & Resorts Investment Narrative Recap
To own United Parks & Resorts, you need to believe the park portfolio can convert a growing base of prepaid visits into steadier cash generation, even when weather or tourism work against it. The recent Q3 softness and lower year to date profit show how quickly attendance and higher costs can squeeze margins, which the analyst consensus Narrative on Simply Wall St already flags as a key risk.
The most important near term catalyst is better execution on marketing and passholder monetization, so that the nearly 8% pass sales increase and strong forward bookings actually show up in attendance and in-park spending. The biggest current risk is that weaker visitation and rising expenses, including interest costs, keep pressuring earnings while management invests in technology and attractions.
The 2027 guidance that points to a clear path to significantly higher revenue is the disclosure that matters most for this update. Management is effectively asking investors to focus on the earnings power of a larger pass base, digital tools such as kiosks, and higher guest spending per visit rather than a single softer quarter.
For you, the key issue is execution. United Parks & Resorts has already highlighted forward bookings, record per capita spending earlier in 2026, and cost saving efforts through technology as potential supports for margins. Those are the same levers analysts mention as core to the story, so any sustained miss on attendance or operating costs would directly challenge that narrative.
United Parks & Resorts' current narrative centers on analysts expecting revenue to grow 3.1% per year, with earnings forecast to rise from US$133.6 million today to US$173.3 million by 2029. That path implies earnings need to increase by about US$39.7 million, with revenues projected to reach US$1.8 billion in the same 2029 timeframe.
Uncover why United Parks & Resorts' fair value indicates a 12% potential upside to its current price before that discount starts to close.
Exploring Other Perspectives
One alternative angle on United Parks & Resorts focuses less on the 2027 revenue path and more on the risk that attendance softness keeps earnings volatile. The most cautious analysts were only looking for about US$1.7b of revenue and US$141.8 million of profit by 2029, which is a far more pessimistic path. Those estimates were set before this Q3 miss and fresh guidance, so you may see forecasts and narratives shift. That is why it helps to compare several viewpoints rather than anchor on a single story.
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your United Parks & Resorts research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for United Parks & Resorts. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate United Parks & Resorts' overall financial health at a glance.
Looking For More Investment Ideas Beyond United Parks & Resorts?
If United Parks & Resorts has helped sharpen what you want from a business, you can use that same checklist to scan the wider market. The Simply Wall St Screener lets you filter for balance sheet strength, income potential, or mispriced quality, so you can line up a watchlist that actually matches your risk tolerance and goals.
- If you want income to do more of the heavy lifting in your returns, start with resilient payers in our 5 dividend fortresses and see which ones fit your yield and stability goals.
- If your priority is finding financially robust businesses first, then price second, narrow the universe using the list of solid balance sheet and fundamentals (24 results) and focus on companies with the strength to handle setbacks.
- If you are hunting for quality that is still under the radar, filter for smaller, fundamentally sound stocks using the 20 high quality undiscovered gems and build a list of ideas to research next.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com