


- Century Communities announced that long time executive Jim Francescon, who has led key acquisitions and corporate operations, will become President in January 2027. He will oversee homebuilding, land and related functions as part of a multiyear succession plan.
- The move hands day to day control of core building, land and M&A activity to an insider with direct experience integrating HistoryMaker Homes, Anglia Homes and Landmark Homes of Tennessee into Century Communities’ footprint.
- The focus now shifts to how Century Communities’ succession plan, which elevates Jim Francescon, could reshape the existing investment narrative.
Century Communities Investment Narrative Recap
To own Century Communities, you need to believe the analyst consensus narrative on Simply Wall St that a large lot position, a wide community footprint and shorter build times can convert into healthier earnings once affordability improves. Recent quarterly results, with revenue of US$864.47 million and net income of US$12.62 million, highlight that the near term hinges on stabilising incentives and protecting margins.
The biggest short term swing factor is whether Century Communities can keep sales volumes and pricing firm while incentives remain in the 1,100 to 1,300 basis point range. The main risk is that mortgage rate pressure keeps orders soft and forces extended discounting, which would matter more to margins than the 2027 leadership change itself.
The upcoming promotion of Jim Francescon to President appears most connected to the earlier 2026 guidance and Q3 earnings update. Management projected 2026 deliveries of 9,350 to 9,650 homes and home sales revenue of US$3.3b to US$3.4b, while reporting nine month revenue of US$2,581.37 million and net income of US$73.17 million.
Francescon has been overseeing homebuilding, land, M&A and integrations, which sit at the center of those volume and revenue targets. For you as a shareholder, the question is whether consistent execution on acquisitions, community openings and cost control under his watch can support the existing catalysts without adding to the leverage and cash flow risks already flagged.
Century Communities' current analyst storyline points to revenues of US$4.1b and earnings of US$212.6 million by 2029, built on an assumed 2.8% yearly revenue growth rate and an earnings increase of about US$103.5 million from the US$109.1 million reported today.
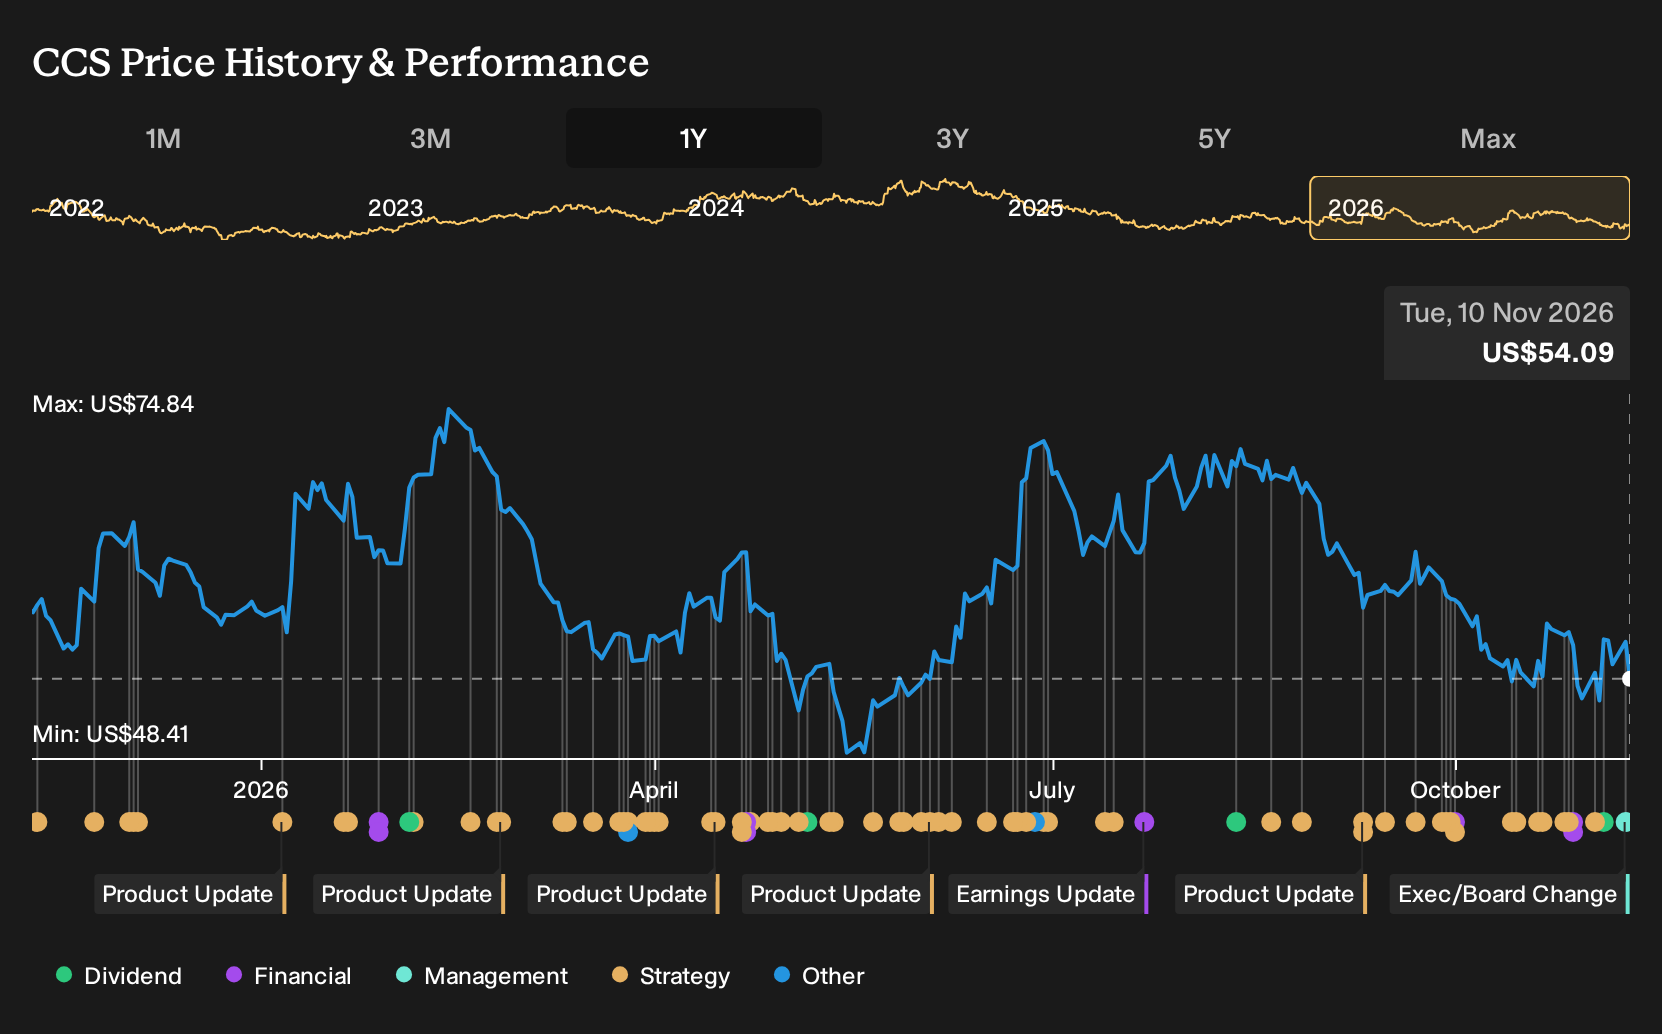
Discover why Century Communities' fair value indicates a 33% potential upside to its current price, suggesting a discount that could close sooner than anticipated.
Exploring Other Perspectives
One alternative view is that balance sheet strain, not cycle times, matters most for Century Communities. The most cautious analysts were using the same US$4.1b revenue path by 2029 but only US$179.5 million in earnings, which implies much thinner profitability. Those forecasts came before this leadership change, so the story could shift from here.
Explore 3 other Century Communities fair value estimates, including one that suggests as much as 55% downside from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and instincts.
- A great starting point for your Century Communities research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Century Communities. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Century Communities' overall financial health at a glance.
Looking For More Ideas Beyond Century Communities?
If this leadership shift at Century Communities has you reassessing where you want housing exposure in your portfolio, it can help to widen the lens and scan for other businesses with different balance sheet profiles, income streams or risk levels using the Simply Wall St Screener.
- For investors who want a focus on stability, start with a 30 resilient stocks with low risk scores that aim to keep volatility and business risk contained.
- If value is your priority, review a curated 35 high quality undervalued stocks where fundamentals and pricing may be more aligned with your margin of safety criteria.
- Income focused readers can scan a 5 dividend fortresses that put regular cash returns at the center of the investment case.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com