


- Otsuka Corporation reported earnings for the nine months ended September 30, 2026, with sales of JPY 1,094,309 million and net income of JPY 49,778 million, and basic earnings per share from continuing operations of JPY 131.27.
- The small year over year uplift in both sales and net income, alongside closely aligned basic and diluted EPS, indicates steady operational execution without heavy dilution for existing shareholders.
- We will now look at how Otsuka's higher nine month sales figure shapes the investment narrative and what it might signal.
Scan how Otsuka's steady nine month earnings compare with other cash generative businesses by reviewing the hand picked 21 high quality undervalued stocks that are already priced for caution, not perfection.
What Is Otsuka's Investment Narrative?
To own Otsuka, you need to be comfortable with a services heavy IT model that depends on consistent project work and long term support contracts. The latest nine month results, with sales of ¥1,094,309 million and net income of ¥49,778 million, reinforce a story of measured execution rather than breakneck expansion. Earnings growth has already slowed compared with the 5 year pace, and forecasts point to revenue and profit rising more slowly than the wider Japanese market, so near term catalysts look more about stability and contract quality than big upside surprises.
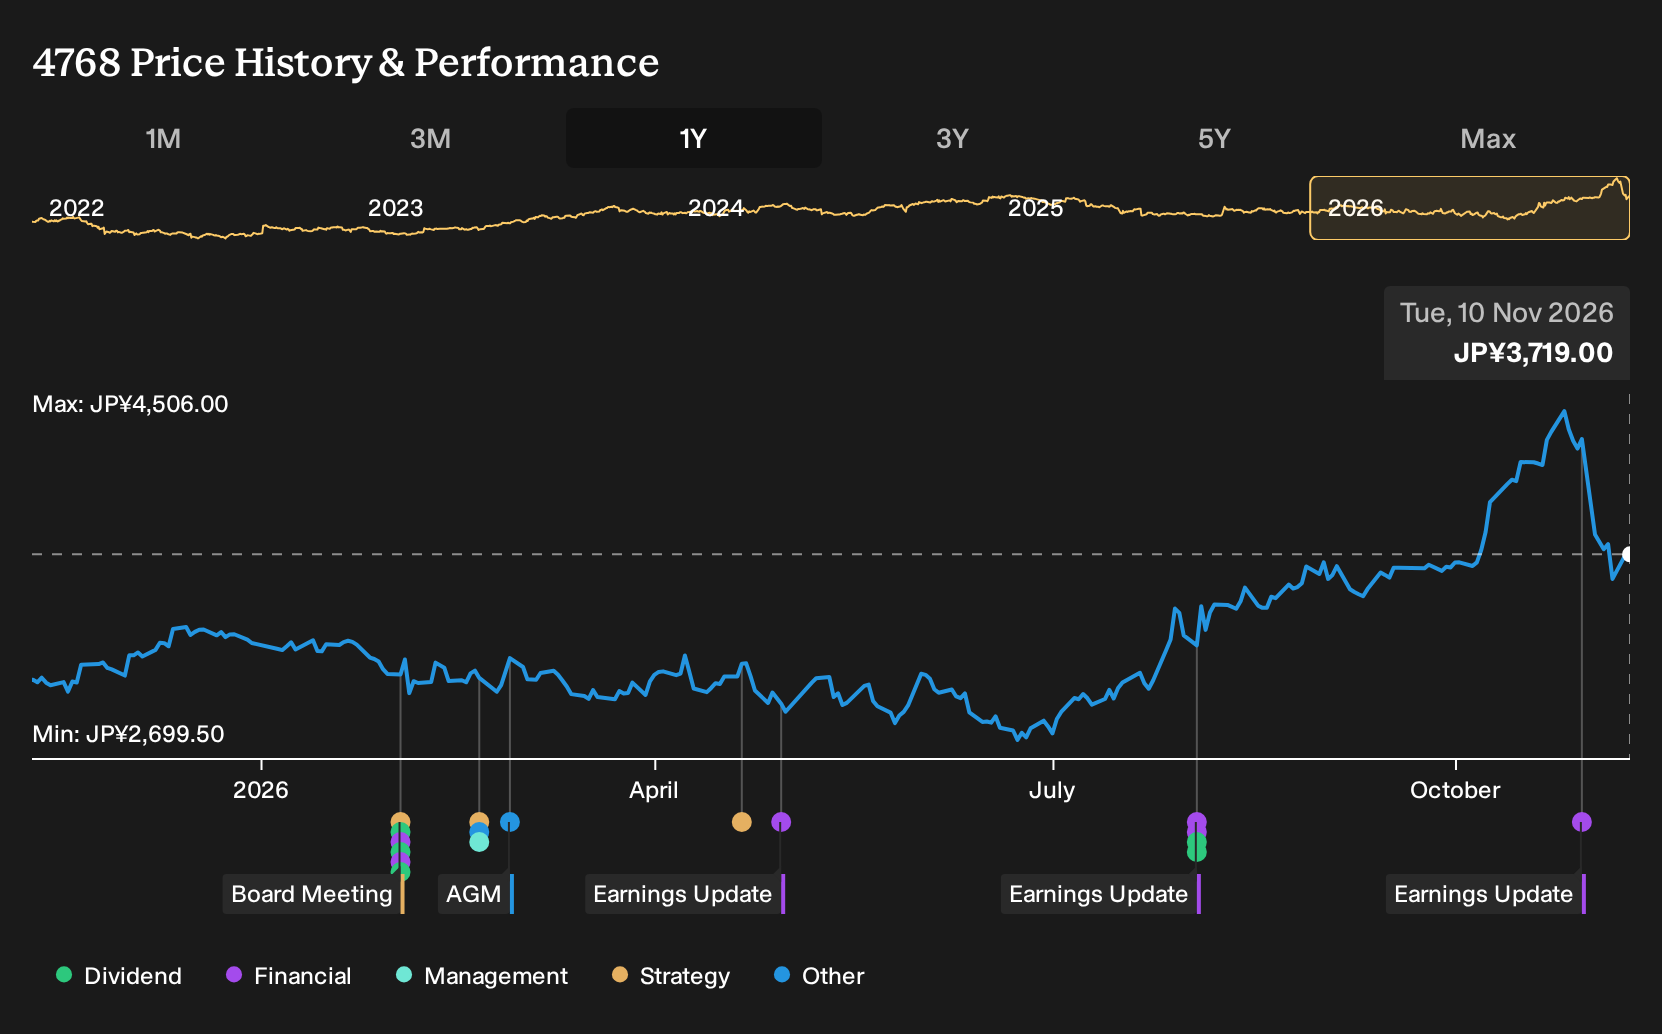
The short term swing factors are practical. Can Otsuka keep demand healthy in system integration while maintaining pricing, and can it do that without pushing capital intensity or working capital too hard? The stock currently trades on a P/E of 20.9x, above the broader JP IT industry but below peer averages and an estimated fair P/E, so expectations already bake in decent execution. One area to watch after these earnings is cash generation, given the 2.82% dividend is not well covered by free cash flow, which ties the results directly into the main risk debate.
That said, anyone focusing only on the earnings line and the recent share price performance is missing the more uncomfortable angle around...
There's only one way to know the right time to buy, sell or hold Otsuka. Head to Simply Wall St's company report for the latest analysis of Otsuka's Fair Value.
Reach Your Own Conclusion
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Otsuka research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Otsuka. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Otsuka's overall financial health at a glance.
Looking For More Ideas Beyond Otsuka?
If Otsuka has sharpened your sense of what you want from a listed business, it can help to compare it with a broader mix of opportunities that share similar financial strengths or income profiles.
- For investors who care most about valuation support and quality fundamentals, review the 21 high quality undervalued stocks already screened for resilient cash generation and disciplined balance sheets.
- If income is a key part of your plan, focus on the 27 dividend fortresses that combine elevated yields with a track record that aims to support regular payouts.
- When capital protection comes first, filter for resilience by scanning the 19 resilient stocks with low risk scores that score well on financial strength and business stability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com