


Hotter than expected US inflation has pushed up global bond yields and kept borrowing costs in focus, which puts reliable, low carbon electricity sources in the spotlight for many governments looking for long term energy security. Australian nuclear energy related stocks sit at the intersection of that policy push and the hunt for durable cash flows. This article walks through three nuclear linked opportunities from our filtered list.
The three stocks highlighted here offer a compelling starting point if you want exposure to uranium producers, enrichment providers and reactor related businesses for reliable, sustainable power. However, if you want the strongest names, these 17 nuclear renaissance stocks are at the top of the list.
Worley (ASX:WOR)
Overview: Worley is a global engineering and consulting group that designs, delivers and maintains energy, chemicals and resources projects, including nuclear infrastructure within its low carbon energy business.
Operations: Worley generates about A$6.2b of segment revenue from the Americas, A$4.5b from EMEA and A$1.3b from APAC, plus smaller unallocated items.
Market Cap: A$5.0b
For nuclear focused investors, Worley matters because its engineering and operations support help keep complex reactors and fuel cycle assets running safely. The analyst consensus Narrative on Simply Wall St sees that low carbon project pipeline feeding into a larger opportunity set.
"The accelerating global push for decarbonisation and energy transition is expanding Worley’s addressable market, and the current factored sales pipeline of future work is 24% higher year-on-year with more than $10b of recent wins in areas such as LNG, power and energy transition materials, which can support future revenue and backlog growth.
What happens to Worley’s margins and cash generation if a single key assumption about those long cycle low carbon projects breaks?
If that risk question is front of mind, the full narrative for Worley outlines how Worley’s decarbonisation pipeline, regional mix and contract profile could still accelerate value creation.

Silex Systems (ASX:SLX)
Overview: Silex Systems commercialises and licenses its SILEX laser enrichment technology to produce enriched uranium for nuclear reactors, while also pursuing quantum computing and medical isotope applications.
Operations: The group records about A$13 million of segment revenue from the Silex Systems unit and A$2 million from Translucent, with activity concentrated in the United States.
Market Cap: A$961 million
Silex Systems matters for this nuclear energy screen because its laser enrichment platform is designed to supply reactor grade uranium fuel, and the analyst consensus Narrative on Simply Wall St frames the upcoming demonstration plant as a key turning point for that role.
"Progression from the completed TRL 6 pilot to the planned full scale TRL 7 uranium enrichment demonstration in Wilmington, targeted for the end of 2027, positions Silex Systems for potential future royalty revenue growth if commercial equipment performance supports an investment decision on an 8 million SWU facility."
What happens to Silex Systems’ future margins and cash generation if a single assumption about those royalty rich enrichment volumes does not hold?
If that question is on your mind, the full narrative for Silex Systems shows how Silex Systems’ enrichment royalties could scale or stall as the Wilmington project accelerates.

Paladin Energy (ASX:PDN)
Overview: Paladin Energy is a Perth based uranium producer. Its Langer Heinrich mine and Canadian projects supply fuel for nuclear power reactors.
Operations: Paladin Energy currently derives about $361 million of revenue from its uranium mining operations in Namibia.
Market Cap: A$3.9b
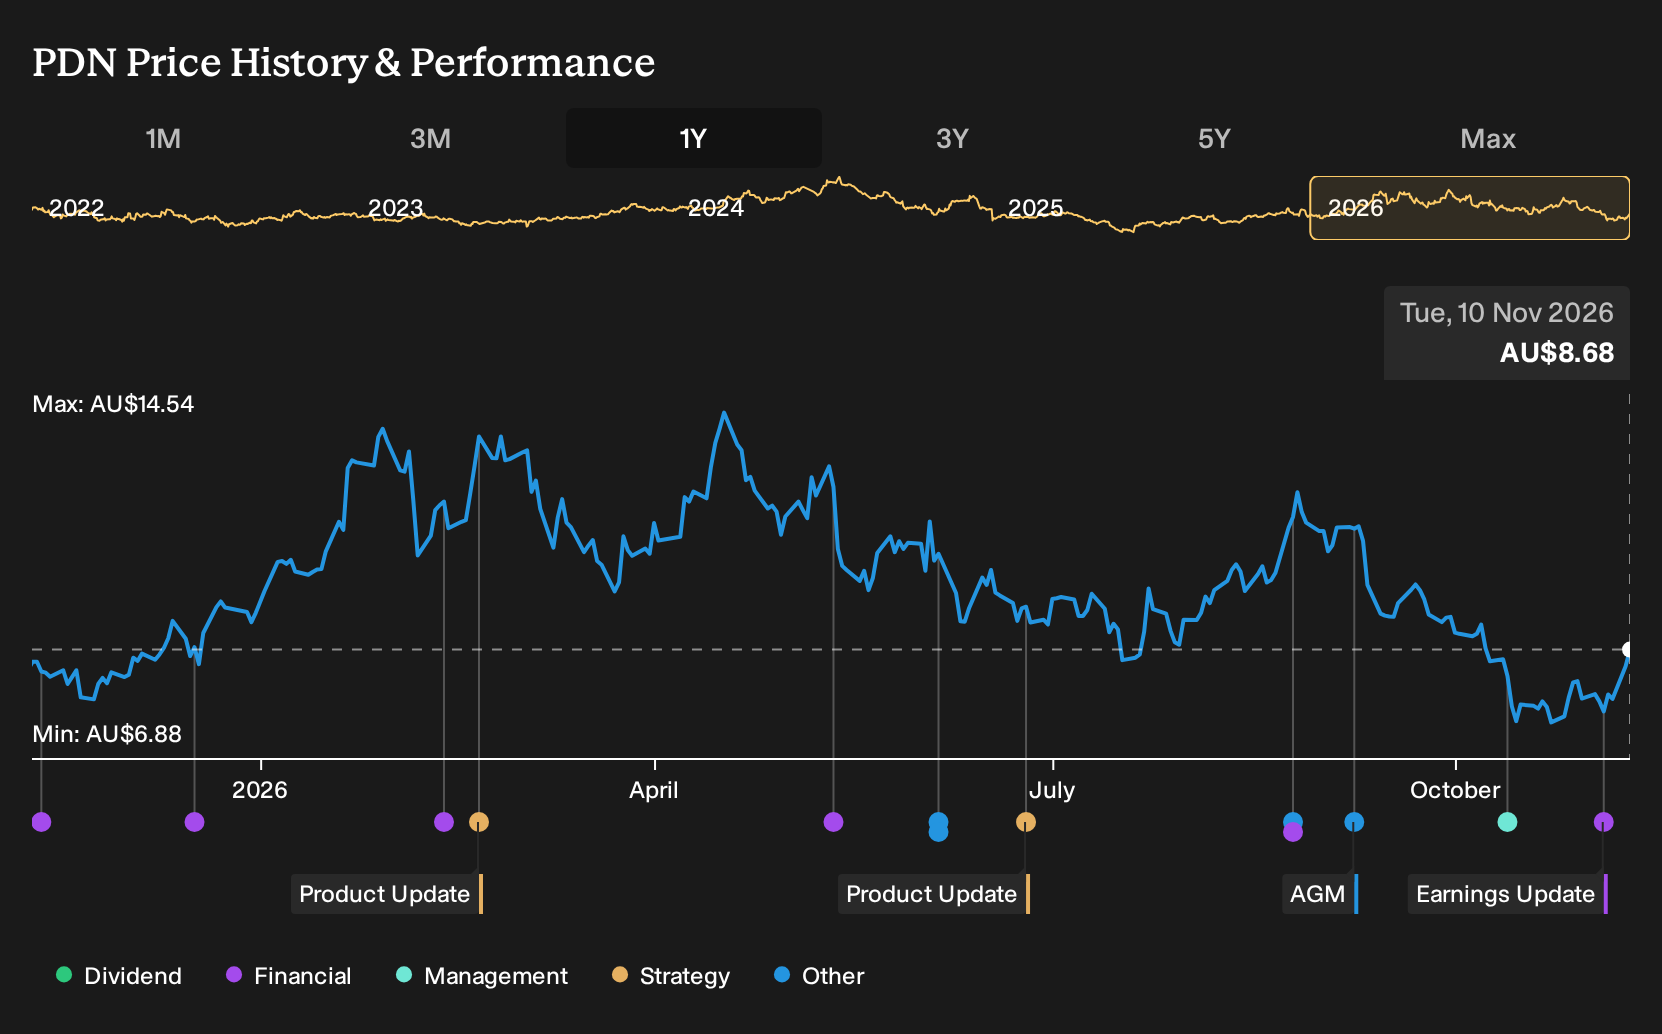
Paladin Energy matters for this nuclear energy list because its uranium output and long life assets tie directly into the fuel needs of global reactors. According to tommyt, an investor in the Simply Wall St Community, the existing contract book already tells an important part of that story.
"Paladin already has 22.3 million pounds contracted out to 2030 across 12 offtake agreements, with recent sales realised at US$69.90/lb."
What happens to Paladin Energy’s future cash generation if a single assumption about long term uranium market tightness breaks?
If you want to see how that contract book could accelerate or stall under different uranium scenarios, the full narrative for Paladin Energy maps out the moving parts behind Paladin Energy.
Curious About What You Might Be Missing?
Fresh ideas move first. By the time a breakout story hits every headline, the easy momentum can be gone. Scan under the radar for now and act now.
- Spot cash rich opportunities that the market has not fully priced by reviewing the curated list of solid balance sheet and fundamentals (12 results) before that quality gets fully recognised.
- Ride the next wave of AI infrastructure demand by checking the hand picked 53 AI infrastructure stocks while these operators are still building momentum.
- Lock in potential income streams from durable businesses by scanning the curated 5 dividend fortresses while share prices have not fully caught up.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com