


Equinor (OB:EQNR) has been in focus after reporting third quarter 2026 results, issuing updated production guidance for the year, affirming its dividend, and continuing its ongoing share buyback programme.
Despite the stronger third quarter earnings, Equinor’s recent trading has cooled, with the share price down 9.45% over the past week and 8.54% over the past month, yet still showing building momentum with a 58.20% year to date share price return and a 61.32% one year total shareholder return.
Scan how Equinor compares to other income and quality plays by reviewing our hand picked 216 dividend fortresses in today’s market.
After a sharp pullback following strong third quarter numbers and firmer guidance, Equinor now trades at a discount to both intrinsic estimates and analyst targets. The key question is whether that gap reflects justified caution or a potential mispricing that valuation work can help assess next.
Most Popular Narrative: 1% Overvalued
Equinor last closed at NOK382.20, fractionally above the analyst consensus Narrative fair value of NOK379.90, which the analyst consensus Narrative on Simply Wall St derives from detailed revenue, earnings and discount rate assumptions.
Targets for 30% international production growth towards 950,000 boe per day by 2030, backed by projects like Greater PAJ that at final investment decision are expected to generate more than US$50 per barrel in cash flow from operations, can reinforce expectations of rising group cash flow and earnings power that support a higher valuation.
See why 99 investors see Equinor as 1% overvalued.
Result: Fair Value of NOK379.90 (ABOUT RIGHT)
Still, if Equinor executes its extensive NCS 2035 drilling and tieback plan efficiently and embeds its digital tools more deeply, cash flows and margins could differ from this fair value narrative.
Find out about the key risks to this Equinor narrative.
Another View: Equinor Through The Earnings Lens
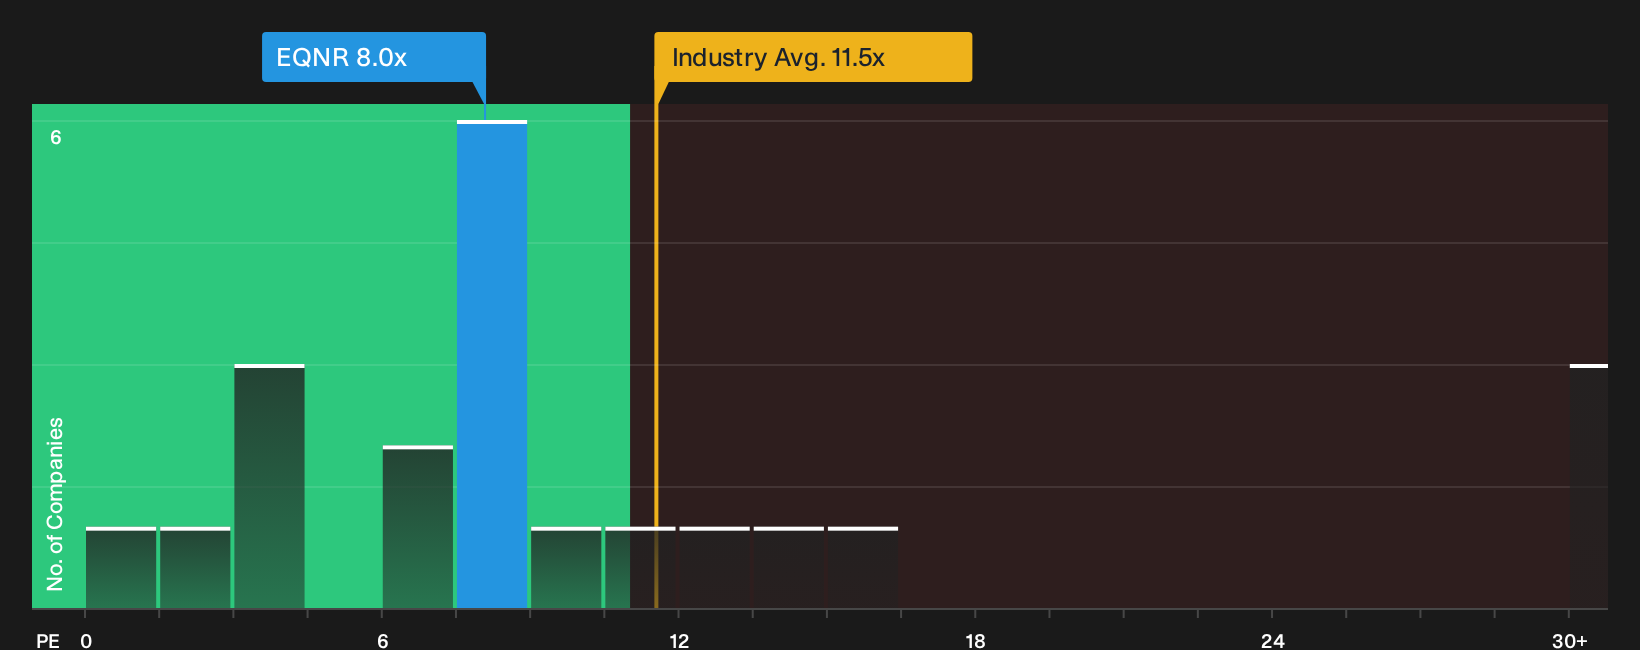
The first fair value narrative pins Equinor close to NOK380 per share. On simple earnings, the picture looks different. At a P/E of 8x versus European oil and gas peers on 11.5x and a fair ratio of 10.1x, the stock trades on a clear discount that points to valuation risk if sentiment turns, but also room for re rating if confidence holds.
See what the numbers say about this price gap in our valuation breakdown next, starting with See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Equinor so far, right, with valuation, income and sentiment all pulling in different directions while you weigh the trade off between risk and potential upside. If you want to pressure test that view against the underlying data and sentiment, start with the 2 key rewards and 2 important warning signs
Looking for more Equinor sized investment ideas?
If Equinor has sharpened your focus on valuation and risk, use the Simply Wall St Screener to widen your opportunity set before the next move passes you by.
- Target potential mispricing early by scanning a curated set of quality candidates through the 199 high quality undervalued stocks.
- Protect your downside first by filtering for companies with stronger finances using the list of solid balance sheet and fundamentals (194 results).
- Hunt for tomorrow’s potential standouts by checking companies the market may be missing via the 567 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com