


Hotter than expected US inflation and the risk of higher interest rates are keeping pressure on growth assets, which puts steady Australian dividend payers firmly back in the spotlight. Reliable cash payouts can help smooth returns when markets feel jumpy. This article walks through three high yielding companies from a screen that looks for dividends above 3% that appear well covered, growing and relatively consistent.
The three stocks highlighted here offer a compelling starting point if you want exposure to high yielding dividend powerhouses with payouts above 3% that aim to be well covered, growing and stable. However, if you want the strongest names, these 5 dividend aristocrats stocks are the top of the list.
BHP Group (ASX:BHP)
BHP Group is a global resources heavyweight. Its iron ore and copper operations are key to the Dividend Powerhouses theme, with these cash generative mines funding its high, well covered payouts. It generated about US$29.0b from copper, US$23.9b from iron ore and US$5.6b from coal, and has a market value around A$304.3b.
The analyst consensus Narrative on Simply Wall St highlights why income focused investors keep coming back to BHP for dependable cash generation linked to long life assets and a growing pipeline of future facing commodities.
"A strong pipeline of copper and potash projects positions BHP Group to benefit from a global surge in decarbonization efforts and electrification initiatives, with rising demand for critical minerals expected to influence future revenues."
The real swing factor for future dividend strength is how one pressure on project delivery ultimately flows through to cash margins and payout decisions.
That pressure point is exactly what the full narrative for BHP Group unpacks, revealing how BHP Group could balance accelerating future facing projects with disciplined dividends and emerging capital allocation trade offs.

Fortescue (ASX:FMG)
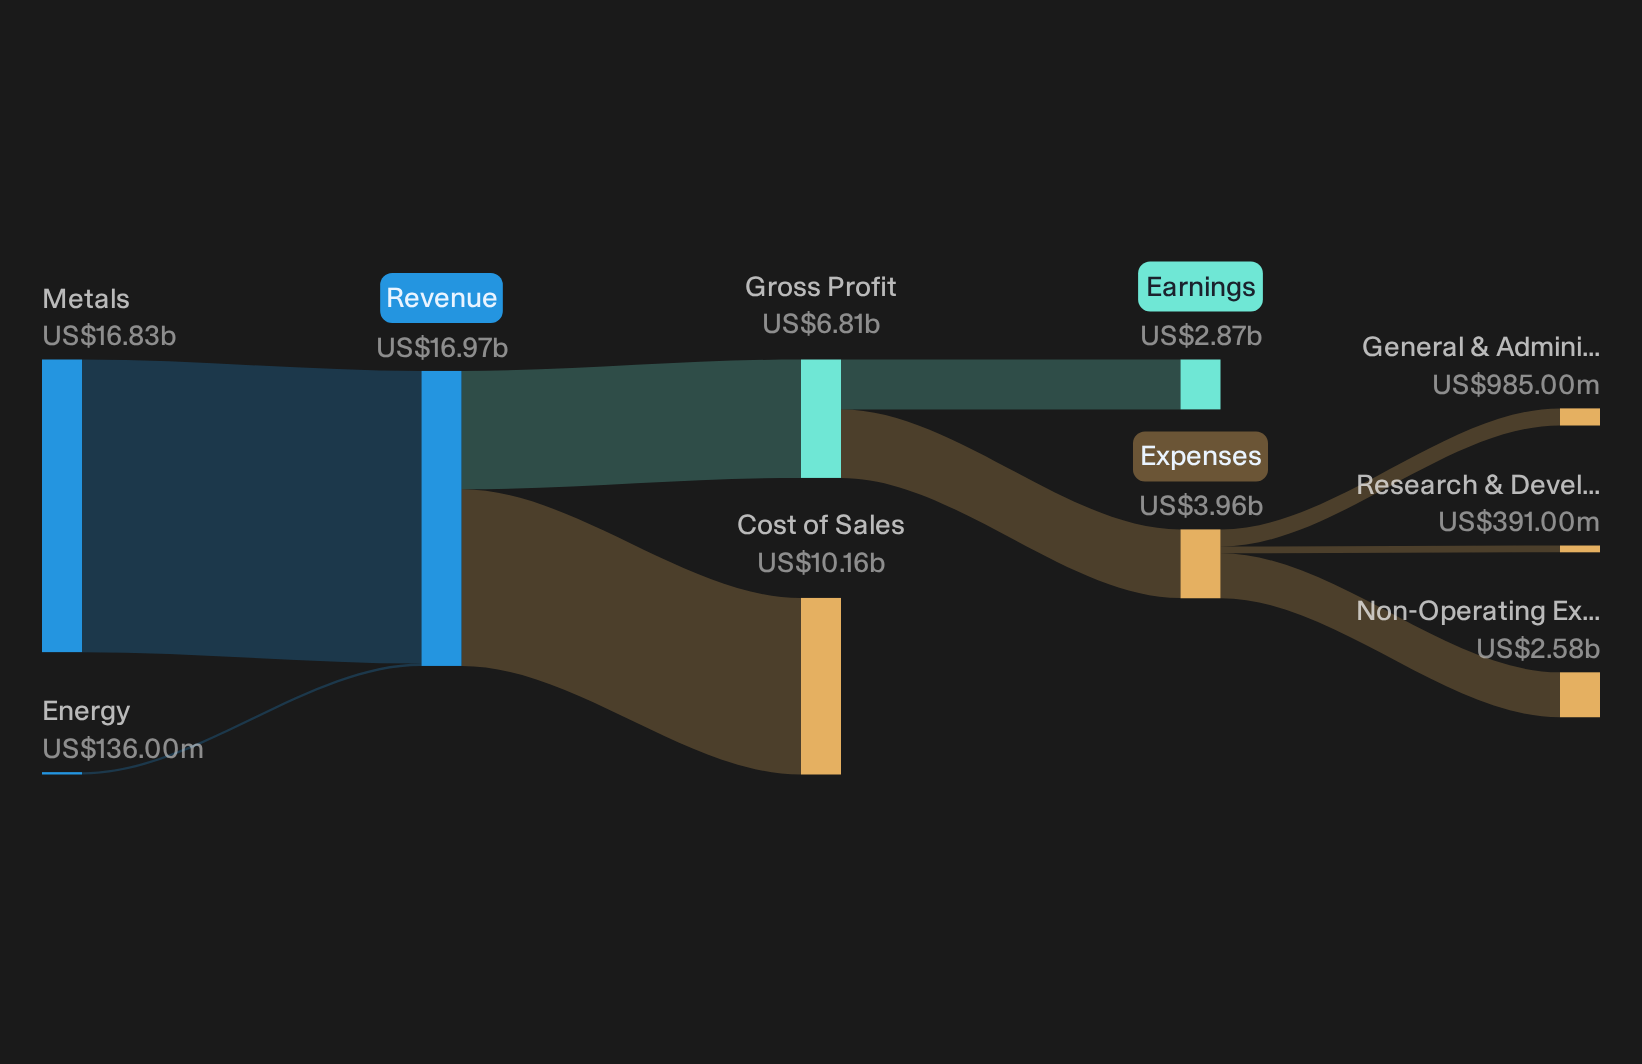
Fortescue runs a large iron ore mining and infrastructure operation that funds its dividend focus, with about US$16.8b from Metals and US$136 million from Energy, and an equity value near A$47.2b.
Fortescue matters for this Dividend Powerhouses theme because its iron ore engine has historically generated the cash that backs its high payout. The analyst consensus Narrative on Simply Wall St also highlights how its decarbonisation plans aim to support that income stream over time.
"Accelerating rollout of Fortescue’s Real Zero by 2030 program, including large scale renewables, storage and electric mobile equipment, is already cutting power costs at Eliwana and Iron Bridge and can further support net margins as diesel use is reduced and fuel savings accumulate."
What happens to dividend strength from here largely hinges on how one unresolved cost and pricing pressure in the iron ore business plays out.
That unresolved pressure is exactly what the full narrative for Fortescue breaks down, revealing how Fortescue could continue accelerating decarbonisation while still pursuing resilient dividend capacity.
QBE Insurance Group (ASX:QBE)
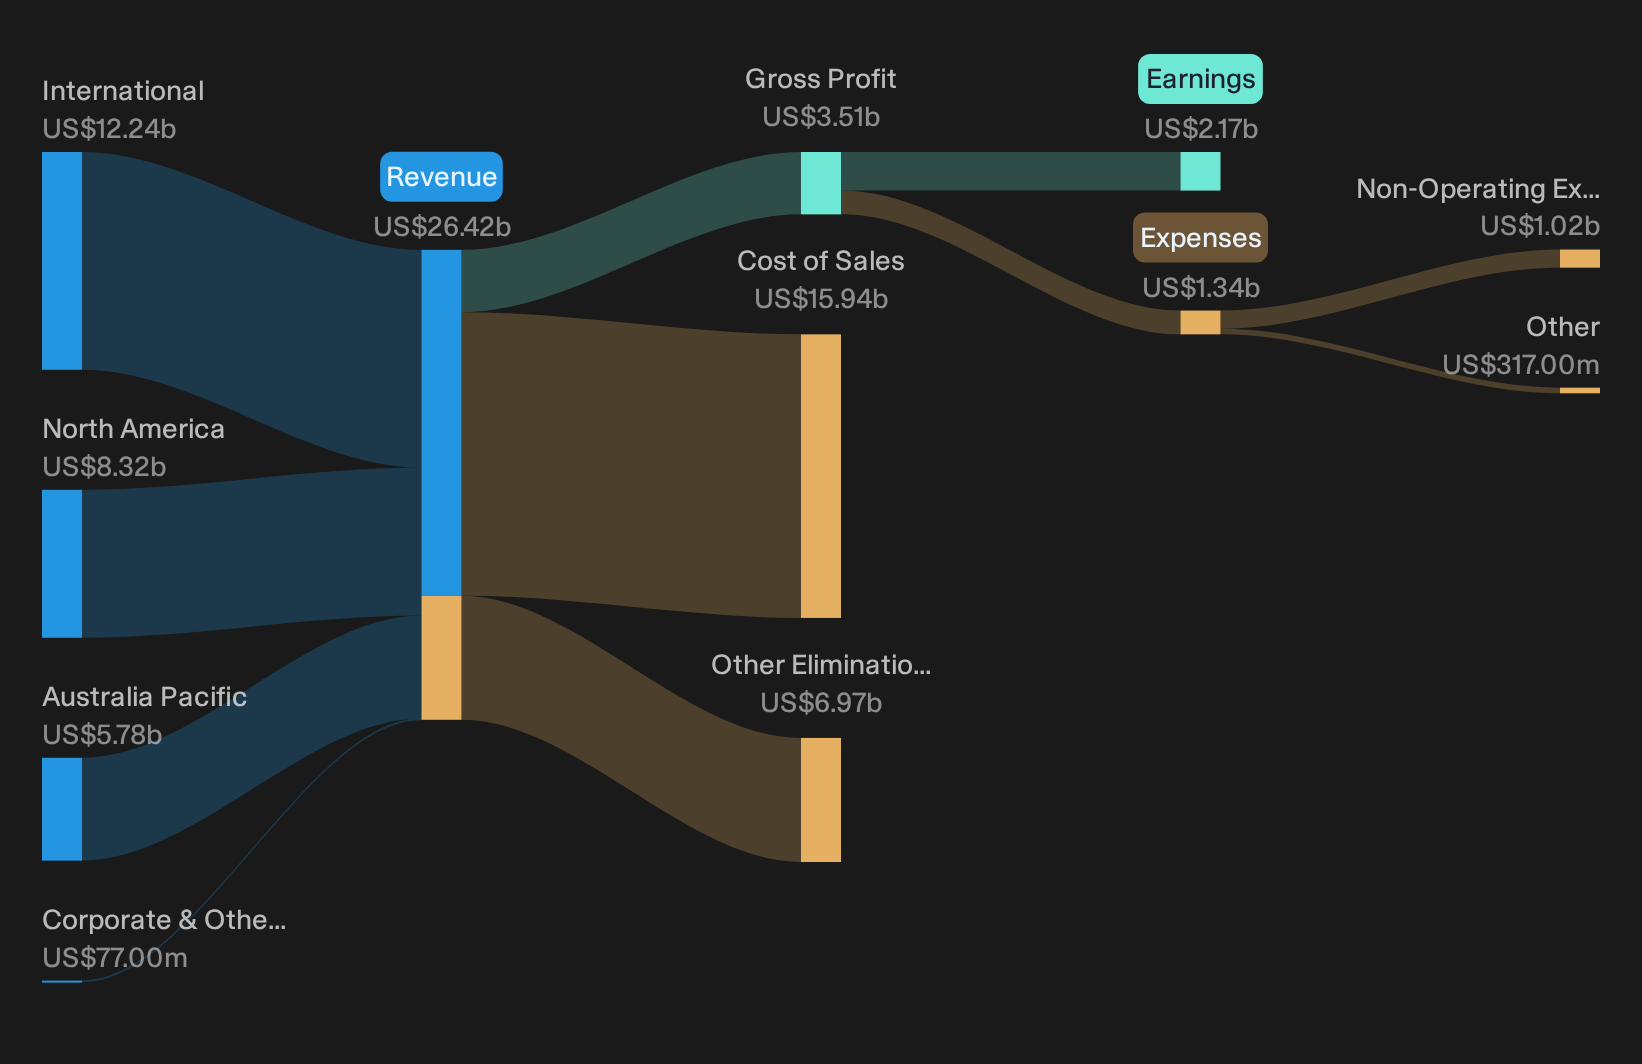
QBE Insurance Group underwrites general and reinsurance policies across commercial and personal lines, using earnings from these operations and its investment portfolio to fund its dividend focus, with around US$12.2b from International, US$8.3b from North America, US$5.8b from Australia Pacific and a market value near A$39.4b.
For QBE Insurance Group, the appeal in a Dividend Powerhouses context is that its broad underwriting and investment engine is geared toward supporting ongoing cash payouts, and the analyst consensus Narrative on Simply Wall St now frames that dividend story through the lens of technology driven efficiency.
"Ongoing transformation through cloud, AI and automation, including a plan to at least double production AI agents after early gains such as faster marine and motor claims handling, is aimed at structurally lowering the expense ratio and supporting a more stable combined ratio and earnings base over time."
What happens to dividend reliability from here hinges on how one emerging pressure on underwriting profitability and capital costs eventually filters through to payout decisions.
To see how that pressure could reshape QBE Insurance Group’s payout story, read the full narrative for QBE Insurance Group and see how underwriting, capital and technology are really interacting.
Seeking Alternatives Before Momentum Flies
Fresh dividend ideas can move from quiet to crowded quickly. Screen for potential breakouts while they are still under the radar for now, then act now.
- Spot income workhorses built to keep paying by scanning a curated 5 dividend fortresses before yield hunters rush in and compress the opportunity.
- Track capital light operators with fortress style funding using the hand picked list of solid balance sheet and fundamentals (12 results) while balance sheets still separate the survivors from the rest.
- Follow the builders behind AI capacity expansion using the focused 53 AI infrastructure stocks before infrastructure spending momentum is fully reflected in broader market coverage.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com