


Murphy USA (MUSA) just posted its third quarter and nine month results, with revenue of US$6.9b and quarterly net income of US$176m, drawing fresh attention to the stock’s earnings profile.
Murphy USA shares closed at US$519.44 after the results, with a 1-day share price return of 1.89% and a 7-day gain of 1.98%. This contrasts with a 90-day share price decline of 5.03%, while the 1-year total shareholder return of 46.13% and 5-year total shareholder return of 193.68% indicate strong long-run momentum despite recent short-term cooling.
Spot opportunities with a similar earnings momentum profile by scanning our hand-picked list of 20 high quality undiscovered gems that have strong fundamentals yet still fly under most investors' radar.Murphy USA has the earnings power to justify attention. After this latest jump and a strong multi year run, the real question is whether the stock already reflects that strength or still offers valuation upside.
Most Popular Narrative: 16% Undervalued
On the analyst consensus Narrative on Simply Wall St, Murphy USA screens as undervalued, with a fair value of $617.80 against a last close of $519.44. This puts the focus squarely on whether the current earnings power is fully recognised in the price.
Structurally higher all in fuel margins, supported by guidance of about $0.35 per gallon for the back half of 2026 and evidence of rational pricing and higher breakeven levels for marginal retailers, could keep Murphy USA’s gross profit and net margins above prior cycles.
See why 12 investors see Murphy USA as 16% undervalued.
Result: Fair Value of $617.80 (UNDERVALUED)
Still, the bullish Murphy USA story can unravel quickly if structurally higher fuel margins fade faster than expected, or if insider selling keeps pressure on the valuation multiple.
Find out about the key risks to this Murphy USA narrative.
Another View: Cash Flows Paint A Tougher Picture
Murphy USA looks attractive on analyst fair value estimates, yet the Simply Wall St DCF model tells a different story. On that cash flow view, the shares trade above an estimated value of $436.19, which points to potential overvaluation if those longer term assumptions prove closer to reality.
This kind of gap between earnings based targets and discounted cash flow outcomes is where many investors do their deepest homework. It is therefore worth understanding how that model is built before you lean on it too heavily. Look into how the SWS DCF model arrives at its fair value.
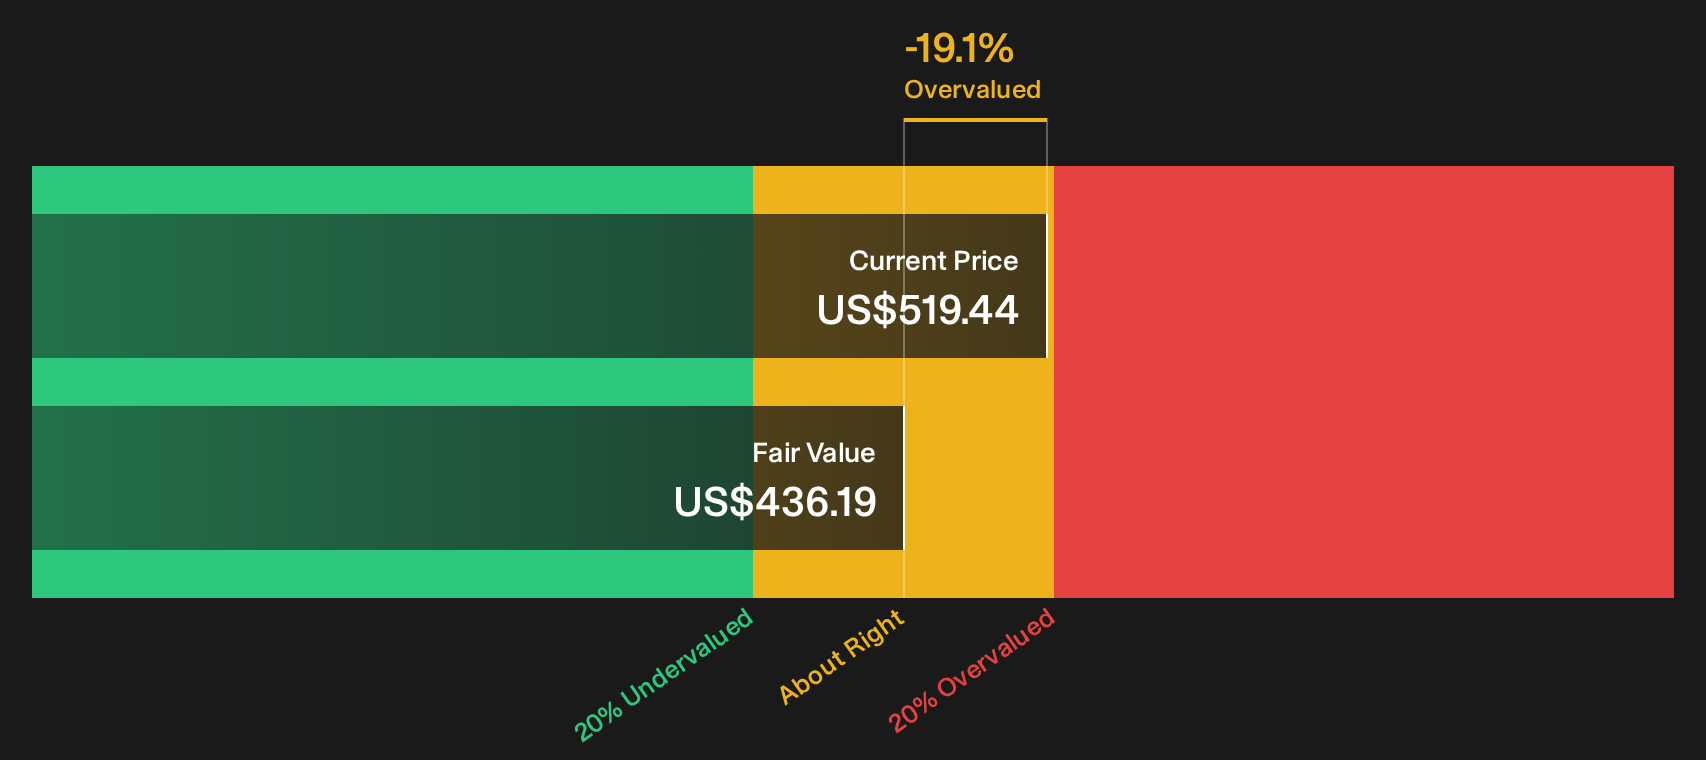
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Murphy USA for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 35 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
With sentiment on Murphy USA split between upside potential and valuation questions, you may want to act promptly and test the assumptions yourself using the full breakdown of 2 key rewards and 3 important warning signs
Looking for more investment ideas beyond Murphy USA?
If Murphy USA has sharpened your focus on quality, do not stop here. Broaden your watchlist now and give yourself more options when the next move matters.
- Target potential upside with a curated pool of companies trading below estimated worth using the 35 high quality undervalued stocks.
- Prioritise resilience by scanning a 30 resilient stocks with low risk scores that highlights businesses with sturdier risk profiles.
- Strengthen your core holdings by reviewing a list of solid balance sheet and fundamentals (24 results) so you can focus on enterprises with financial foundations that may better handle shocks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com