


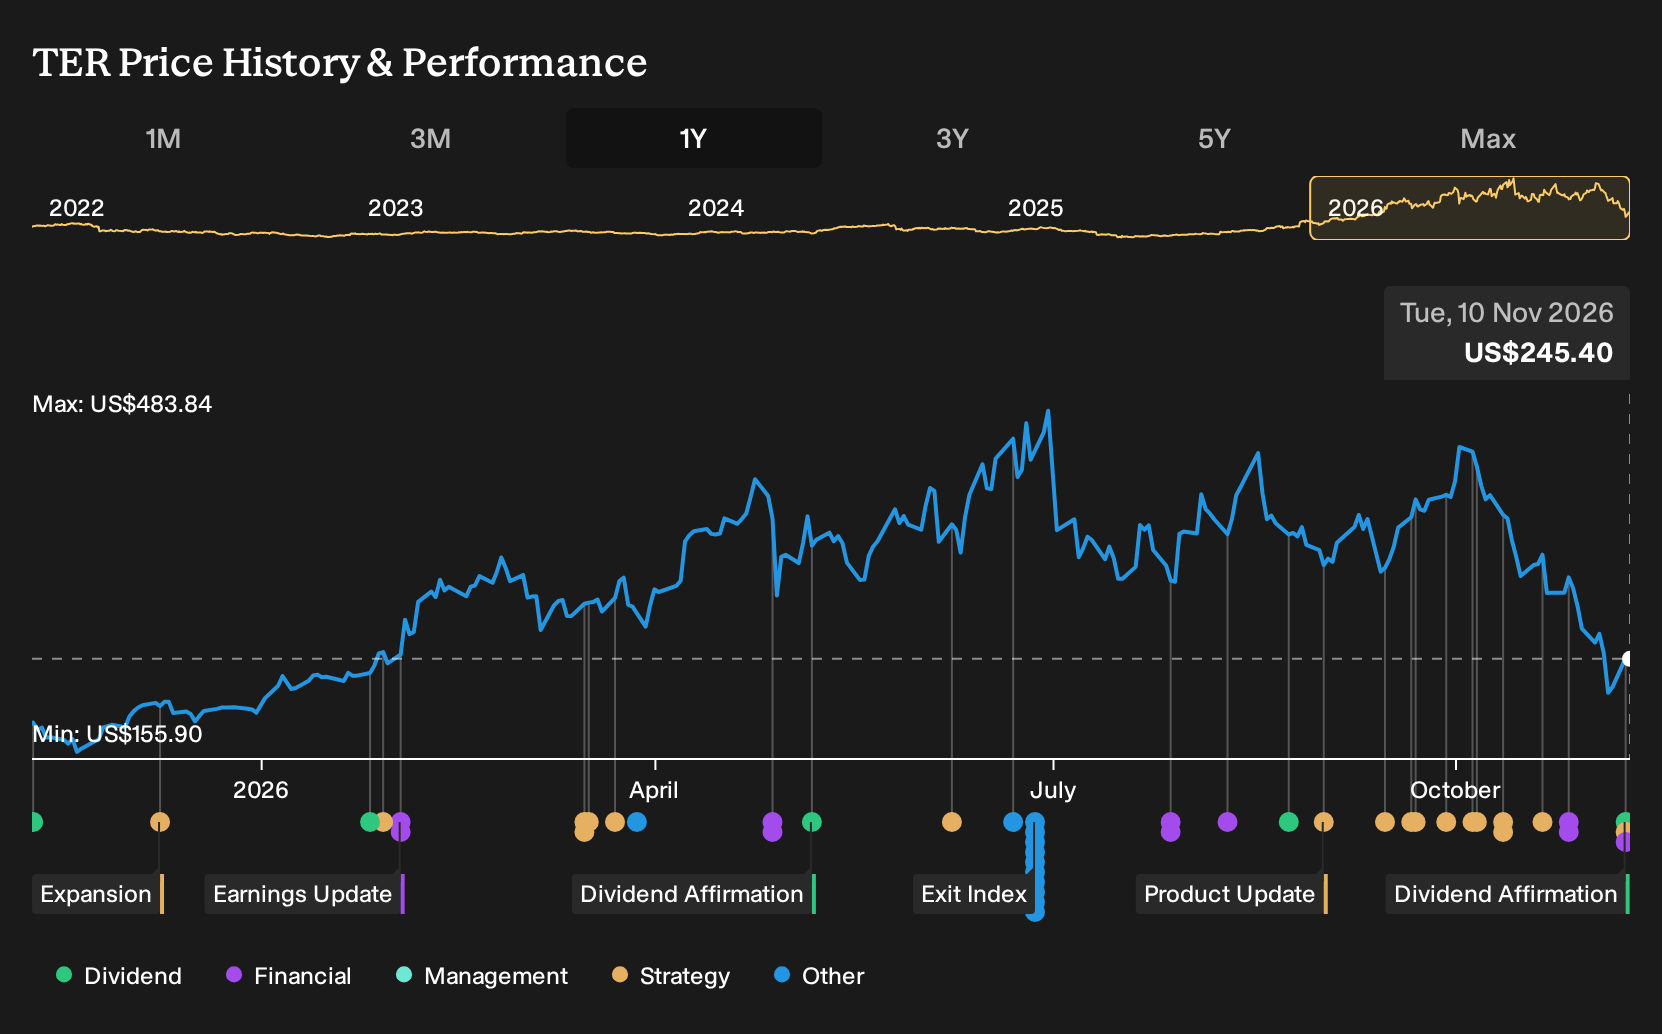
- Teradyne declared a quarterly cash dividend of US$0.13 per share, payable on December 16, 2026, to investors recorded as shareholders on November 23, 2026, and simultaneously rolled out Omnyx Edge, an inline test platform aimed at physical and edge AI hardware across intelligence, sensing, and motion boards.
- The Omnyx Edge launch points to Teradyne pushing deeper into test coverage for AI compute, sensor, and motion control hardware, which ties directly into its focus on physical AI and robotics as new demand engines alongside traditional semiconductor test systems.
- This article examines how Teradyne's broader AI test and robotics investment narrative is shaped by the introduction of the Omnyx Edge platform.
Teradyne Investment Narrative Recap
To own Teradyne, you really need to believe that AI driven test and robotics demand stay strong enough to support both semiconductor test and physical AI automation over time. The analyst consensus narrative on Simply Wall St leans on that view, with earnings forecast to grow about 22% a year and return on equity expected to remain high.
Right now, the key near term swing factor is how mix, AI CapEx timing and new product costs affect margins. Omnyx Edge speaks to long run positioning rather than an immediate fix for Q3 guidance pressure. The fresh US$0.13 dividend matters more for income preferences than for the operating story.
The Omnyx Edge platform is the clearest operational link to the physical AI and robotics catalyst analysts are watching. It targets board test across intelligence, sensing and motion layers in edge and robotic systems, which lines up with management tying more than 60% of revenue to AI focused demand and pushing into factory automation.
If Omnyx Edge gains traction in high volume lines, it could help Teradyne balance exposure between data center compute test and on the floor physical AI hardware, including automotive and logistics. Execution risk remains, especially if AI related capital spending slows or mix shifts further away from compute heavy products and keeps near term gross margins under pressure.
Teradyne's current analyst narrative points to forecast revenues of US$8.9b and earnings of US$2.9b by 2029. These projections are built on an assumed 21.2% yearly revenue growth rate and an earnings increase of about US$1.5b from US$1.4b today.
Uncover why Teradyne's fair value indicates a 73% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One bullish twist in the alternate Teradyne story is how strongly some analysts lean into Omnyx style AI demand. Before this news, the most optimistic group was modeling Teradyne toward about US$10.7b of revenue and US$3.6b of earnings by 2029, far above consensus. These views were set before the dividend and Omnyx Edge launch, so you should expect opinions to shift as fresh information filters through and it is important to explore several angles rather than rely on a single narrative.
Explore 4 other Teradyne fair value estimates, including one that suggests as much as 115% upside from the current price!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Teradyne research is our analysis highlighting 5 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Teradyne. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Teradyne's overall financial health at a glance.
Looking for more investment ideas beyond Teradyne?
If the Teradyne story has you thinking about where physical AI, automation, and steady fundamentals might intersect next, the Simply Wall St Screener can help you cast a wider net without losing focus on quality.
- If you prefer to keep downside risk in check while still hunting for opportunity, start with a group of 30 resilient stocks with low risk scores that score well on resilience and business stability.
- If you want ideas where balance sheets are built to withstand tougher conditions, you can scan a list of solid balance sheet and fundamentals (24 results) and quickly spot companies with stronger financial footing.
- If you are looking for potential mispriced situations with quality fundamentals, filter for 20 high quality undiscovered gems and see which businesses the market might not fully be paying attention to yet.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com