


- HSBC Holdings has been active in debt markets, redeeming legacy 7.39% senior notes due 2028 while issuing new fixed to floating rate senior bonds maturing in 2032 and 2037, alongside fresh perpetual instruments with variable coupons.
- Behind these moves, the bank is reshaping its funding mix with a blend of senior and subordinated, perpetual and dated, fixed and floating instruments that affect interest costs, loss absorbing capital and flexibility through different credit cycles.
- Next, the focus turns to how HSBC Holdings' evolving earnings mix, especially softer wealth management and net interest income, feeds into the broader investment narrative.
Compare HSBC Holdings' reshaping of its funding stack with other large banks by scanning our curated list of list of solid balance sheet and fundamentals (9 results) that could handle tougher credit conditions.
What Is HSBC Holdings' Investment Narrative?
To own HSBC Holdings, you need to be comfortable with a global lender that leans heavily on Hong Kong, the UK and institutional banking while trying to revive wealth and fee income. The recent redemption of high coupon 7.39% notes and issuance of fresh fixed to floating senior and Additional Tier 1 style perpetual paper looks more like balance sheet housekeeping than a reset of the story. It tidies funding costs and capital structure at the margin, but the real near term swing factors still sit in net interest income resilience, wealth management demand and credit quality.
The share price has fallen about 15% over three months even as earnings have been growing. This suggests investors are already wrestling with those issues. New callable, variable rate instruments and longer dated senior bonds give HSBC Holdings more levers through different rate paths. They also underline that this is a capital intensive model that constantly refinances itself. In the short term, the big watchpoints remain how deposit pricing pressure, bad loan charges and a softer wealth backdrop meet that funding plan, rather than the mechanics of this one refinancing round.
That said, the picture becomes less comfortable once you overlay this funding rebuild onto ...
There's only one way to know the right time to buy, sell or hold HSBC Holdings. Head to Simply Wall St's company report for the latest analysis of HSBC Holdings's Fair Value.
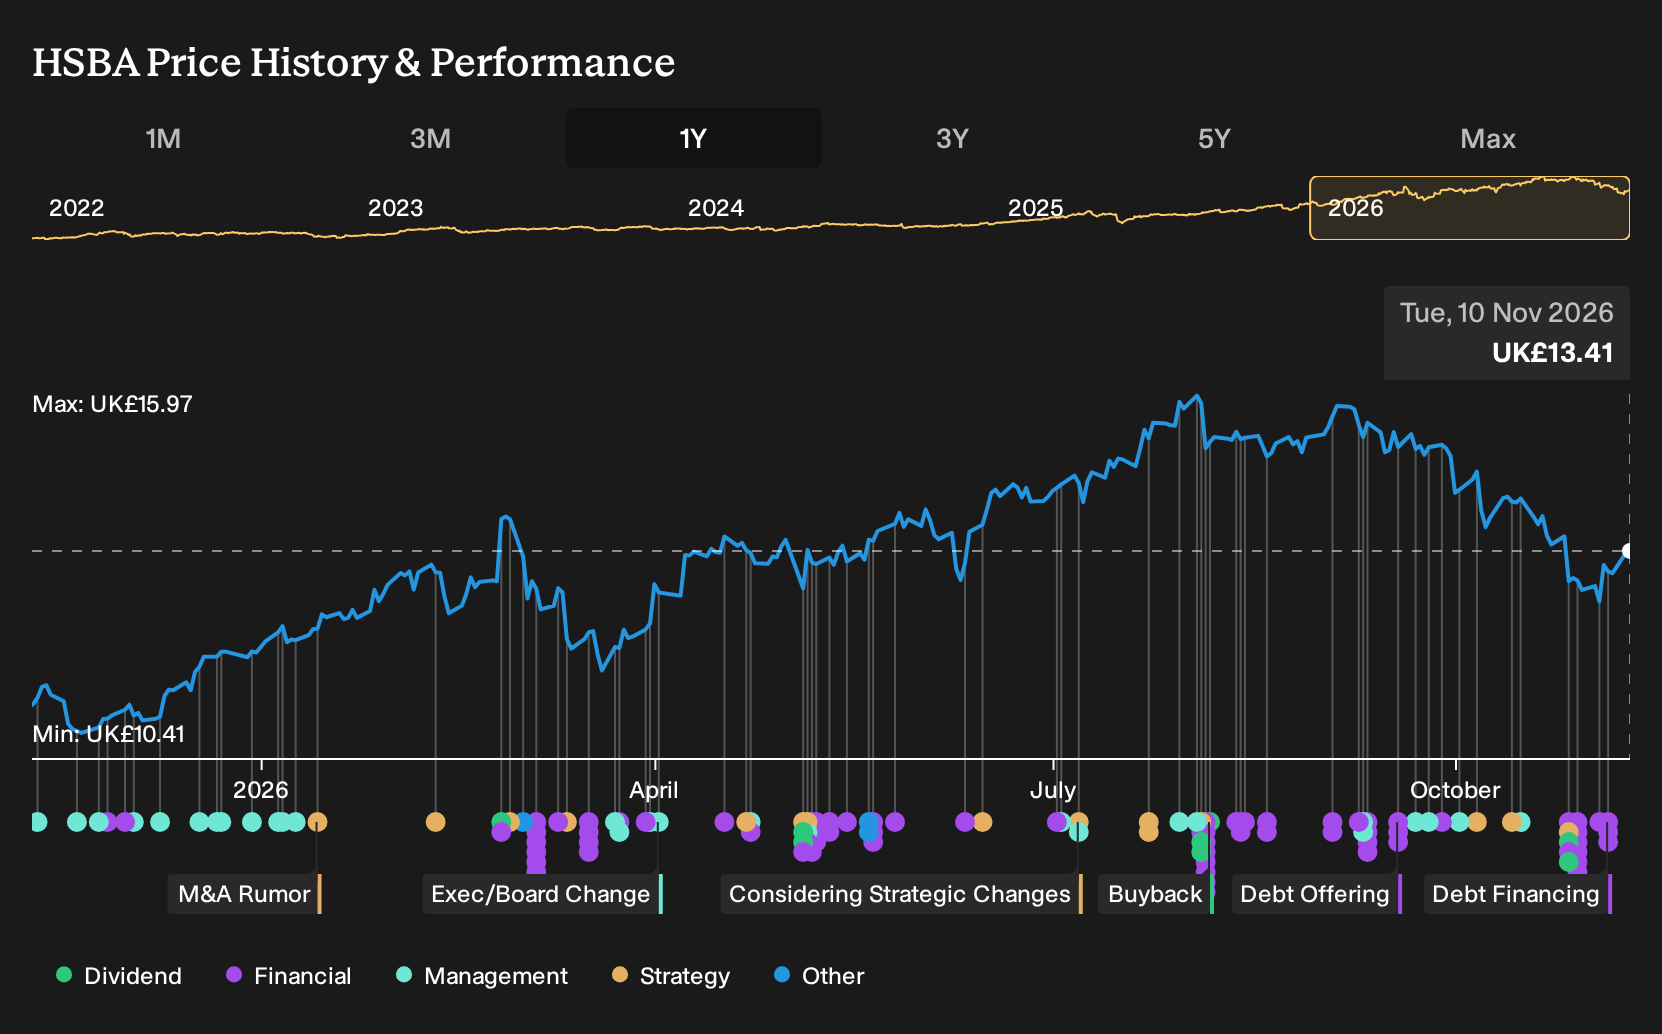
Exploring Other Perspectives
There is a very different story from the most optimistic analysts, who focus on earnings power rather than funding risk. Before this refinancing news, some were modelling HSBC Holdings revenue at about $90.6b and earnings of $37.3b by 2029. You should treat that as one possible path and compare it with your own expectations.
Explore 11 other HSBC Holdings fair value estimates, including one that suggests up to 72% upside from the current price.
Reach Your Own Conclusion
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so trust your own analysis.
- A great starting point for your HSBC Holdings research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for HSBC Holdings. This report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easier to evaluate HSBC Holdings' overall financial standing at a glance.
Looking For More Investment Ideas Beyond HSBC Holdings?
Once you have formed a view on HSBC Holdings, it can help to widen the lens and compare it with other businesses that fit different risk and return profiles. The Simply Wall St Screener gives you a quick way to scan for stocks that line up with the type of balance sheet strength, income profile or upside potential you want to research next.
- If capital preservation sits high on your list, you could start with companies that show steadier fundamentals and relatively modest risk by checking out our 4 resilient stocks with low risk scores.
- If you want ideas that combine quality with a potentially attractive entry point, you might look over a curated 16 high quality undervalued stocks that may warrant deeper research.
- If portfolio income is your focus, you can scan for higher yielding candidates by heading to a set of 6 dividend fortresses that could support a regular payout stream.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com