


McKesson (MCK) has reported its second quarter earnings, with sales of US$110.957b and net income of US$1.218b. Earnings per share from continuing operations also increased compared with a year earlier.
McKesson’s recent earnings release lands after a strong run in the share price, with a 30-day share price return of 15.31% and a 90-day gain of 23.20%. The 1-year total shareholder return of 26.90% and a very large 5-year total shareholder return suggest momentum has been building over both shorter and longer horizons.
Scan how McKesson’s earnings-fuelled momentum compares with other healthcare distributors by reviewing our hand picked list of solid balance sheet and fundamentals (24 results).
For McKesson, a double digit share price jump alongside rising quarterly earnings raises a simple puzzle. Are investors just paying up for better fundamentals, or has sentiment moved ahead of what the business delivers today?
Most Popular Narrative: 6% Overvalued
McKesson closed at $1,082.59 compared with an analyst consensus Narrative fair value of $1,026.07. The analyst consensus Narrative on Simply Wall St ties that gap to how the market is weighing future oncology, specialty and technology earnings against today’s figures at a 7.24% discount rate.
The current valuation and raised analyst price targets indicate that the share price already reflects confidence in McKesson's oncology and biopharma strategy, earnings guidance, and planned shareholder returns. Even so, this narrative maintains that McKesson is still undervalued and that the outlook remains positive.
See why 66 investors see McKesson as 6% overvalued.
Result: Fair Value of $1,026.07 (OVERVALUED)
Still, regulatory pressure on drug pricing and fallout from McKesson’s recent cyber incident could challenge margins and test the bullish oncology and technology expansion narrative.
Find out about the key risks to this McKesson narrative.
Another View on McKesson’s Valuation
Analyst fair value pegs McKesson at $1,026.07, which points to the shares being 5.5% above that mark at $1,082.59. The SWS DCF model tells a very different story, with an estimated future cash flow value of $1,980.95. That gap frames an obvious question: Which lens do you trust more for such a wide spread?
Look into how the SWS DCF model arrives at its fair value.
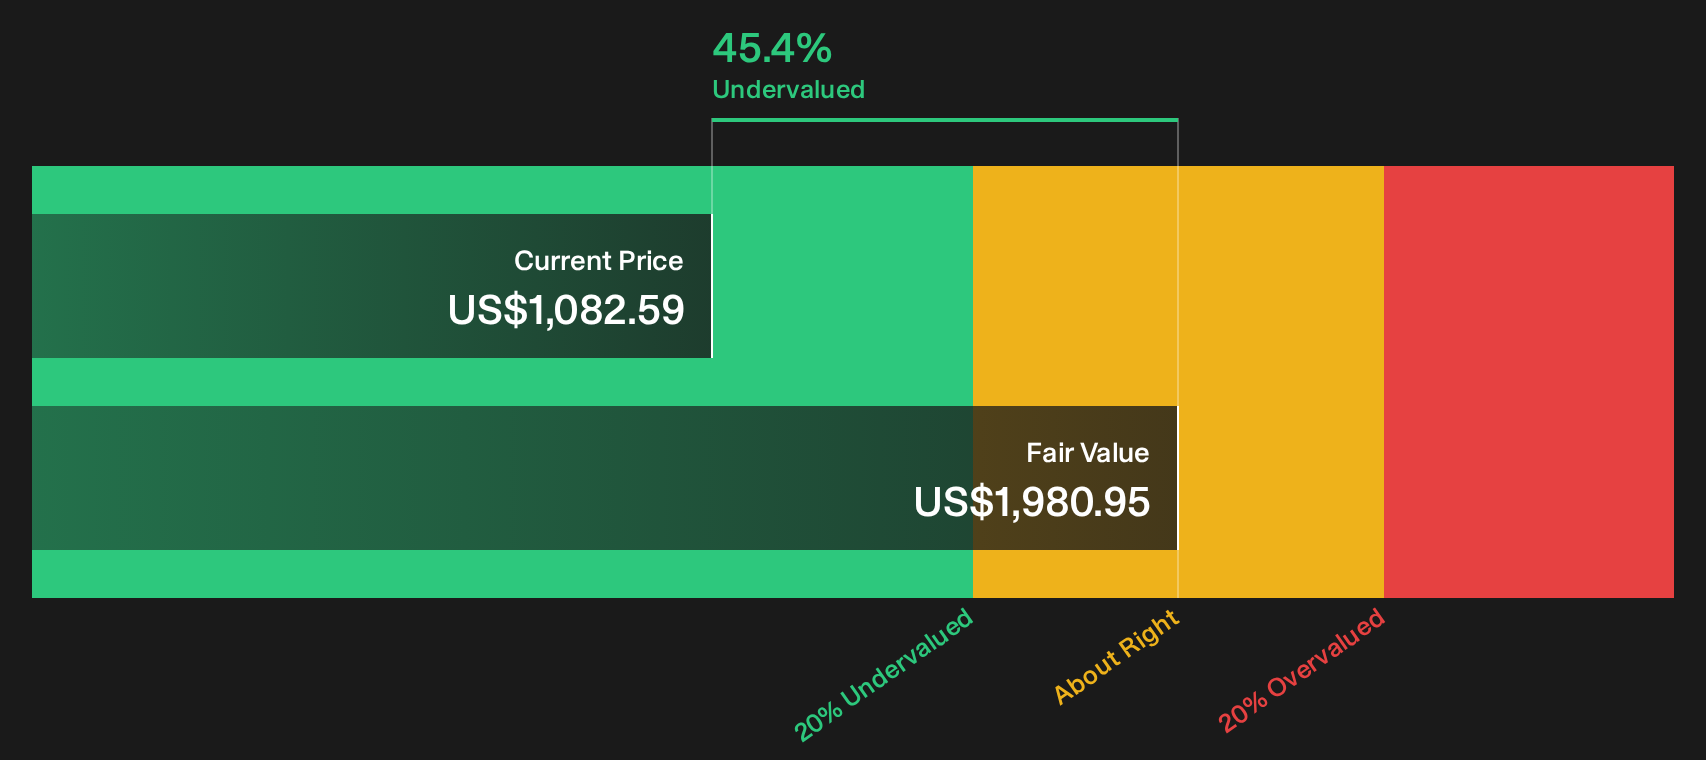
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out McKesson for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 35 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment across McKesson’s story is mixed, with clear upside drivers but also flagged concerns that could matter for your capital. Act while the data is fresh and weigh both sides for yourself by reviewing the 3 key rewards and 1 important warning sign
Looking for more McKesson sized investment ideas?
If you stop with McKesson, you risk missing other opportunities that line up better with your goals, risk tolerance, and income needs across the market.
- Target stronger value for every dollar you invest by scanning companies in the 35 high quality undervalued stocks that pair quality fundamentals with discounted prices.
- Strengthen portfolio resilience by focusing on businesses in the 30 resilient stocks with low risk scores that carry lower overall risk scores.
- Build a watchlist of potential outperformers early by reviewing the 20 high quality undiscovered gems before attention and liquidity move elsewhere.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com