


Arm Holdings (NasdaqGS:ARM) moved back into focus after its latest quarterly report, where sales reached US$1,443 million while net income dropped to US$130 million, sharpening questions about earnings quality and future royalty momentum.
Arm Holdings has seen momentum cool sharply in recent weeks, with the share price falling 31.8% over the past month and 33.2% across the last quarter. This comes even after a 58.2% year-to-date share price gain and a 3-year total shareholder return of about 2.4x that still points to a very strong longer-term run for early backers.
Scan how other AI infrastructure and chip designers are reacting to the same pressures hitting Arm Holdings by zeroing in on 53 AI infrastructure stocks as potential beneficiaries or laggards in this shakeout.
Arm Holdings still looks like a heavyweight in chip design, even after a sharp share price reset. The real tension now is simple: Is this powerful licensing and royalty machine already fully priced, or has the pullback opened a fair entry point on the numbers?
Most Popular Narrative: 58% Undervalued
Arm Holdings closed at $181.49, while the most followed narrative pegs fair value at about $430. The debate is whether the current reset already prices in enough execution risk on AGI CPU and royalties. According to HedgeY, an investor in the Simply Wall St Community, the real argument is how much of Arm’s AI ambitions investors should be willing to prepay for today.
The catch is valuation. Arm is now being valued less like a normal semiconductor company and more like a future monopoly-like infrastructure layer for AI compute. The stock recently traded above $400 after a huge run, though it pulled back with the broader semiconductor selloff on July 13, when Arm fell 7.6% alongside other chip leaders.
See why 47 investors see Arm Holdings as 58% undervalued.
HedgeY’s narrative assumes Arm eventually reaches about $25b in yearly revenue and roughly $9 of EPS, with AGI CPU accounting for a large new stream of chip-level sales on top of the existing licensing and royalty base. That framework lines up with the long-term management ambitions cited in the narrative and uses a discount rate of 11.97% to bring those future cash flows back to today.
The implied outcome is a fair value of roughly $430 per share, which is very close to the narrative’s optimistic valuation anchor of around $430 and roughly 58% above the last close. That gap reflects a belief that Arm’s architecture position in smartphones, data centers and AI compute justifies paying upfront for a long runway of forecast revenue and earnings growth.
Readers should remember that this is just one interpretation of Arm Holdings, built on specific expectations for execution on AGI CPU, continued royalty expansion and regulatory outcomes. If those pillars evolve differently from the assumptions that HedgeY lays out, the fair value estimate implied by the narrative would likely shift as well.
Result: Fair Value of $430 (UNDERVALUED)
Still, the Arm Holdings narrative could be knocked off course if AGI CPU execution disappoints, or if regulatory scrutiny around architecture leverage tightens meaningfully.
Find out about the key risks to this Arm Holdings narrative.
Another View on Arm Holdings: Market Pricing vs Fair Ratio
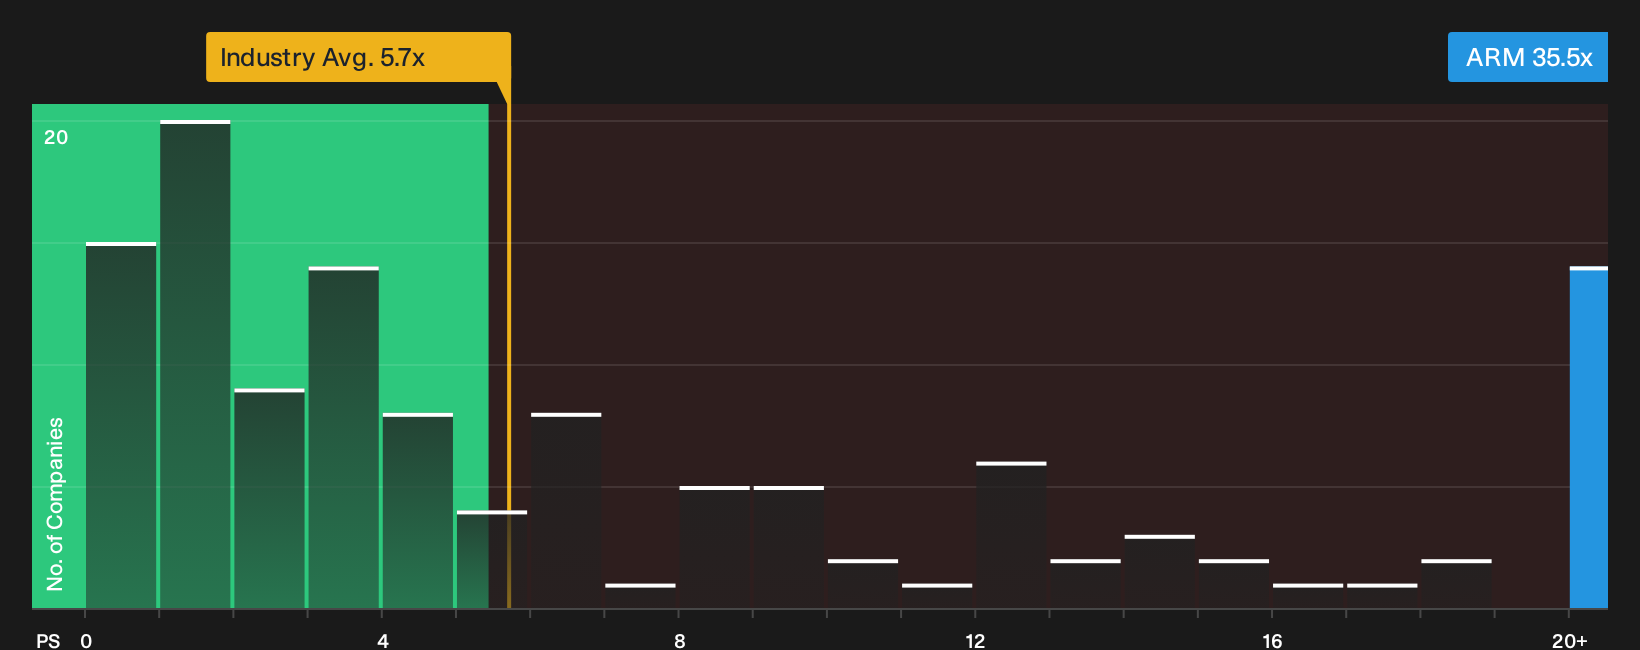
Arm Holdings may look attractive against the community fair value of $430, yet the current P/S of 35.5x tells a different story. It is far above the US semiconductor sector on 5.7x and peers on 11.4x, even though the fair ratio sits higher again at 43.6x. That spread suggests real valuation risk if sentiment cools before fundamentals catch up. Where does that leave investors weighing entry timing?
For a more numbers heavy breakdown of how this price stacks up against fundamentals and peers, take a look at the valuation breakdown, then pressure test whether the current premium still feels comfortable See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Arm Holdings valuation can feel confusing, so move quickly on the data, consider both the potential upside and the red flags, and then decide whether the story adds up for you using the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Arm Holdings?
If Arm Holdings has your attention, do not stop here. Broaden your watchlist with fresh ideas that fit different risk levels, income needs and quality filters.
- Target potential mispricing by scanning a focused set of quality opportunities using the 35 high quality undervalued stocks.
- Strengthen your income stream by reviewing companies that aim to pay out reliable cash returns through the 5 dividend fortresses.
- Protect your downside by filtering for sturdier businesses with cleaner balance sheets through the list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com