


Beam Therapeutics (BEAM) just cleared a major clinical hurdle, reporting that its investigational sickle cell therapy risto-cel met all primary and secondary endpoints in the BEACON Phase 1/2 trial and is supporting plans for an FDA filing.
Even with the positive risto-cel headline, Beam Therapeutics shares have been under pressure in the short term, with the 1-day, 7-day and 90-day share price returns all declining. The 1-year total shareholder return of 11.88% and 3-year total shareholder return of 2.44% point to mixed but still positive longer term momentum off a much weaker 5-year total shareholder return of 72.06%.
Spot fresh biotech stories at a similar inflection point by scanning our hand-picked 36 healthcare AI stocks, which pair clinical progress with compelling equity setups.Bulls see Beam Therapeutics as a derisked gene editing platform after risto-cel, while bears focus on ongoing losses and past share price damage. Which story does the current valuation actually echo?
Most Popular Narrative: 49% Undervalued
Beam Therapeutics last closed at $25.15, while the analyst consensus Narrative on Simply Wall St points to a fair value of $49.38. This frames the current debate around whether recent clinical progress is fully reflected in the price.
The accelerated approval design for BEAM-302 in alpha-1 antitrypsin deficiency, built around an approximately 50-patient pivotal Part C cohort at 60 mg with 12-month biomarker endpoints and a planned functional-outcome confirmatory trial, positions a second potential product that could add to revenue and earnings if approval is achieved.
See why 63 investors see Beam Therapeutics as 49% undervalued.
Result: Fair Value of $49.38 (UNDERVALUED)
Still, the bullish Beam Therapeutics story depends on trial data holding up at scale and on legal disputes around alpha-1 antitrypsin deficiency not eroding economics.
Find out about the key risks to this Beam Therapeutics narrative.
Another View: What Beam Therapeutics’ Price To Sales Is Saying
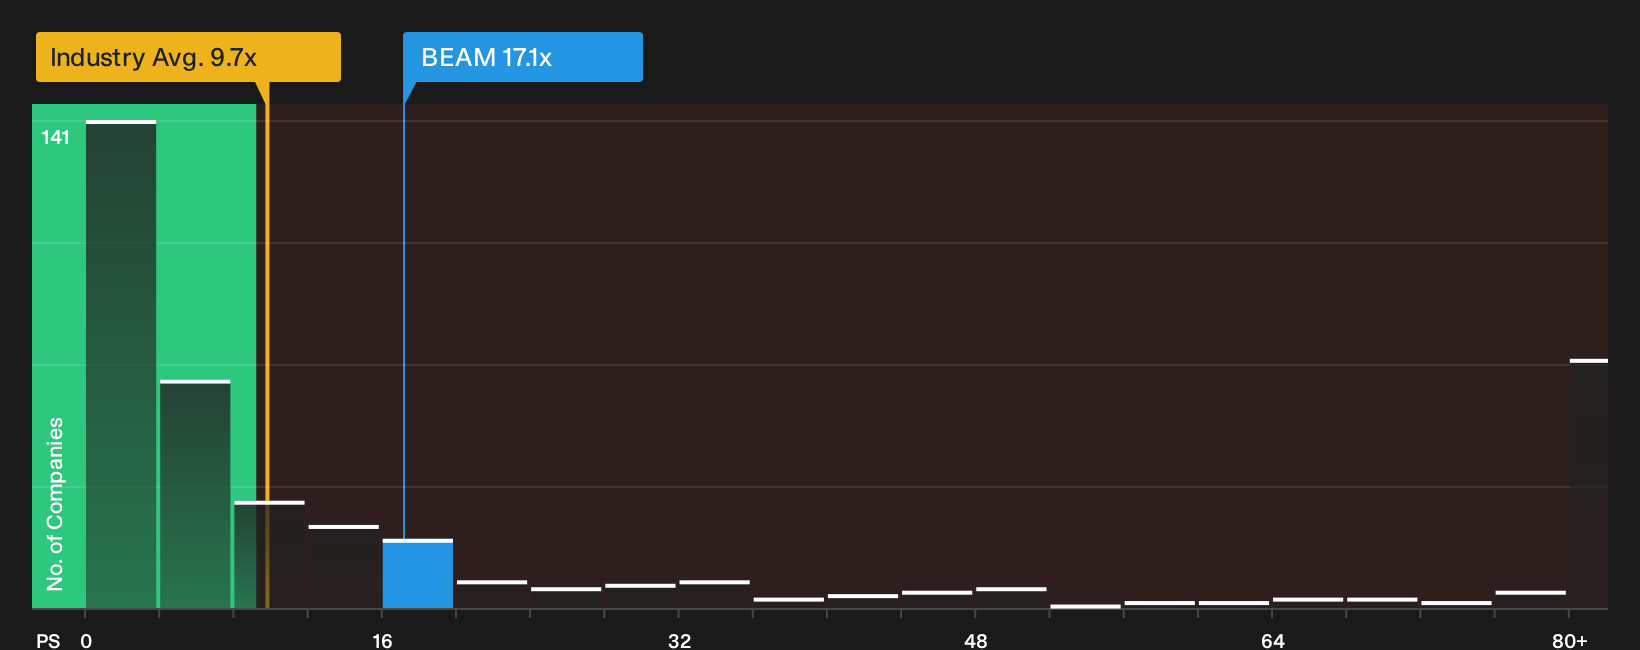
The analyst fair value points to upside, yet Beam Therapeutics currently trades on a P/S of 17.1x. That is richer than both the US Biotechs average at 10x and peers at 13.5x, and far above a fair ratio of 0.8x, which signals meaningful valuation risk if sentiment cools.
Those gaps raise a simple question for investors: Is the current price more anchored to future optimism than to today’s fundamentals, and how comfortable are you with that trade off when better aligned peers may exist nearby?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment on Beam Therapeutics is split, and the window to decide how you feel about that gap does not stay open forever. Weigh both sides carefully with the 2 key rewards and 2 important warning signs.
Looking for more Beam Therapeutics style investment ideas?
Do not stop with Beam Therapeutics. Broaden your watchlist with a few targeted sets of opportunities that could sharpen your next move and help you stay prepared.
- Target resilient potential by scanning a 30 resilient stocks with low risk scores that can help you focus on businesses with steadier risk profiles when markets turn choppy.
- Hunt for real value by checking a 35 high quality undervalued stocks that highlights companies where price and fundamentals may be pulling in different directions.
- Build staying power through income by reviewing a 5 dividend fortresses that concentrates on higher yielding payers with income-focused characteristics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com