


- Dow Inc. has advanced its cost and productivity program, completed the shutdown of a higher cost upstream siloxanes unit, and is putting more capital into specialty silicones capacity in key regions including the U.S., China, and Japan.
- The shift away from a less competitive siloxanes facility toward higher margin, more stable specialty silicones suggests Dow is leaning more into products tied to resilient demand such as data center and advanced industrial applications.
- We will examine how Dow's investment narrative is shaped by this push into higher margin specialty silicones and portfolio streamlining.
Scan how other materials stocks are repositioning toward higher margin niches by reviewing the hand picked 35 high quality undervalued stocks alongside Dow's shift into specialty silicones.
Dow Investment Narrative Recap
To own Dow, you need to be comfortable with a materials heavyweight that is leaning hard on self help rather than a strong macro backdrop. The analyst consensus narrative on Simply Wall St focuses on cost, productivity and portfolio work to reset earnings power while the business manages softer polyethylene demand and margin pressure from feedstock and energy costs.
The short term swing factor is execution on that US$1.3b plus 2026 self help target and the broader US$3b program into 2029. The biggest near term risk is that weak pricing, higher input costs and any legal or chlorpyrifos related outflows keep EBITDA closer to guidance cuts, which would blunt the benefit of the recent silicones mix shift.
The most relevant update for this silicones story is Dow closing the higher cost Barry upstream unit in Europe and committing over US$100m to specialty silicones in the U.S., China and Japan. That move aligns directly with the shift already highlighted in the recent news toward higher margin, more resilient end uses.
For you as a shareholder, this is an execution test. The more Dow focuses on specialty silicones and data center related materials while maintaining capital discipline, the more it supports the analysts' view that self help could raise the earnings base. Any stumble in project delivery or a deeper macro slowdown would limit the extent to which that catalyst comes through.
Dow's narrative projects US$46.4b revenue and US$2.1b earnings by 2029. This assumes 2.9% yearly revenue growth and an earnings increase of about US$3.0b from a loss of US$905.0m today.
Uncover how Dow's fair value indicates a 10% potential upside to its current price that may not last much longer.
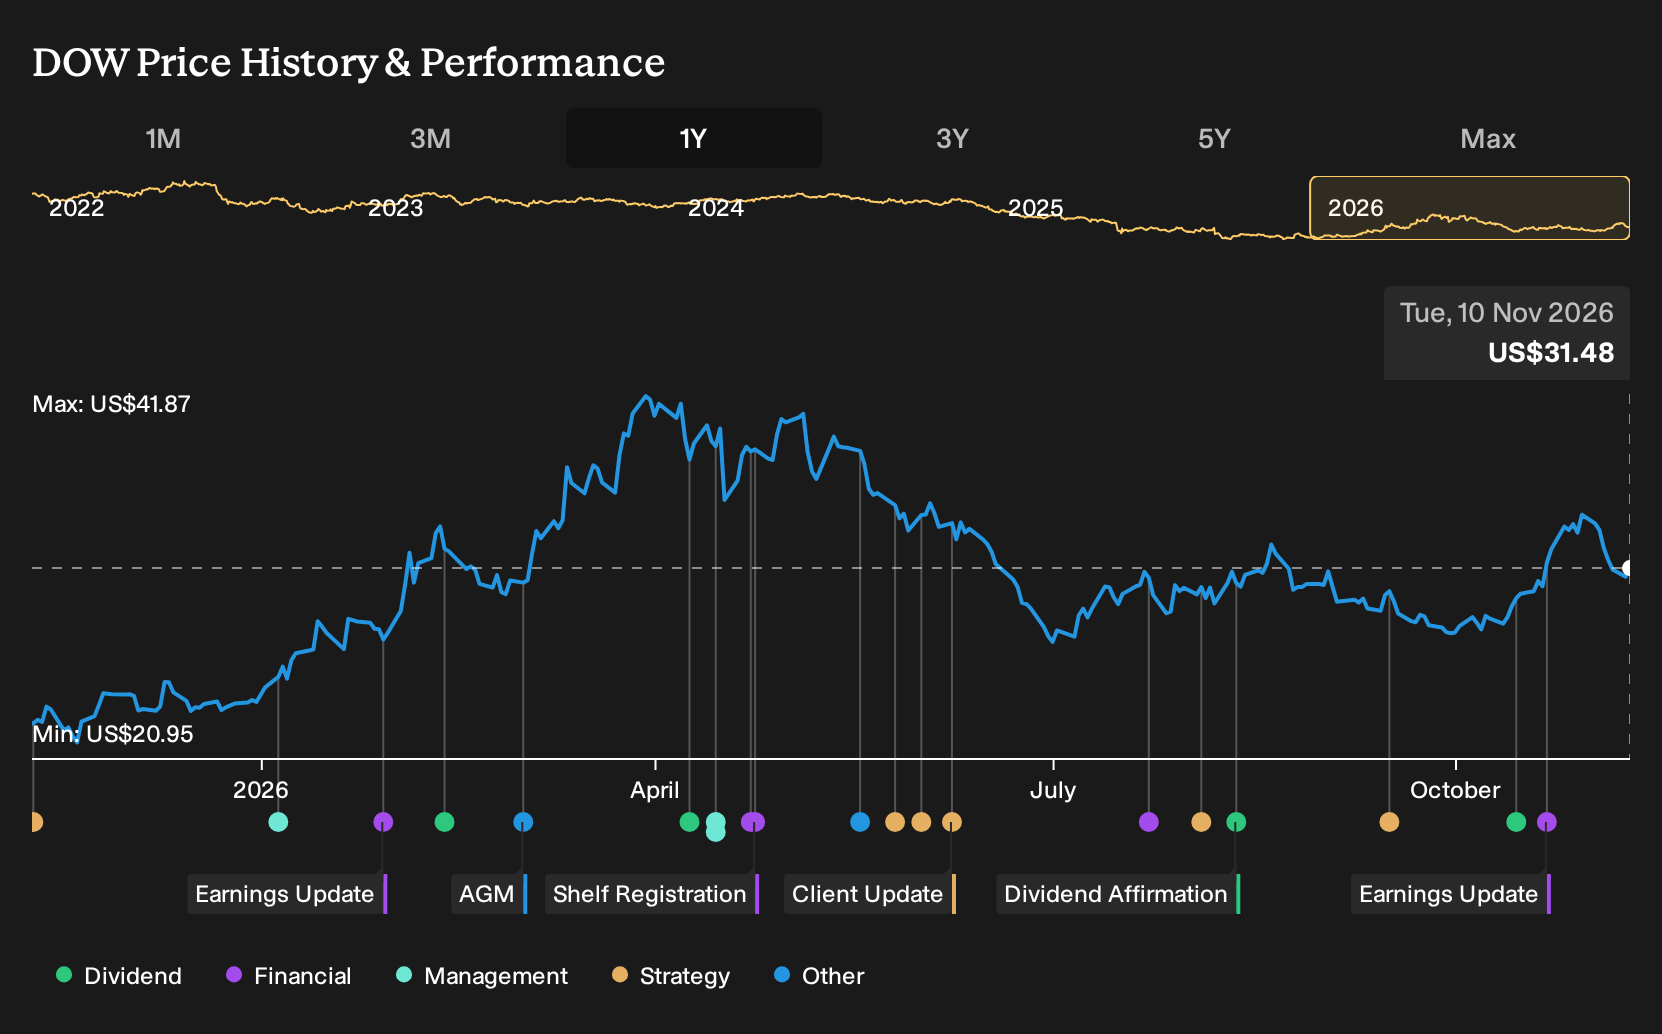
Exploring Other Perspectives
Some of the most optimistic analysts lean heavily on Dow’s access to cheaper feedstocks as the real swing factor, rather than just the specialty silicones push. Before this news, that group was penciling in revenue of about US$47.4b and earnings near US$2.3b by 2029. You can treat this as one possible storyline and compare it with more cautious views as the silicones shift plays through future updates.
Explore 4 other Dow fair value estimates, including one that suggests potential upside of as much as 128% from the current price!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view.
- A great starting point for your Dow research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Dow. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Dow's overall financial health at a glance.
Looking For More Ideas Beyond Dow?
If you want to pressure test your view on Dow next to other opportunities, use the Simply Wall St Screener to compare different types of businesses by quality, valuation and resilience, then see where Dow truly fits in your watchlist.
- For investors who care most about quality at a reasonable entry point, scan a curated 35 high quality undervalued stocks that combine stronger fundamentals with room for sentiment to catch up.
- If capital preservation sits high on your priority list, review a 30 resilient stocks with low risk scores that score well on financial resilience and lower risk signals.
- When you want sturdier balance sheets to anchor a portfolio around more cyclical holdings like Dow, start with a list of solid balance sheet and fundamentals (24 results) that already clear basic strength checks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com