


Elevance Health has posted a 39.0% return over the past year, which puts a fresh spotlight on whether the current share price lines up with what its earnings can reasonably support. With the stock recently closing at US$429.65, the key issue for you is whether that kind of move is grounded in the underlying profit engine of the business or more in changing sentiment around large health insurers.
- The 39.0% gain over the past 12 months raises a simple question for holders and potential buyers alike: are Elevance Health's earnings doing enough work to carry that higher valuation?
- Management has talked about an improved long term earnings outlook, including expectations for better Medicaid margins and at least 12% adjusted earnings per share growth in 2027 from a 2026 baseline, which can shape how durable the current earnings profile appears.
- Your read on Elevance Health is one view; the desks covering it have another. See what analysts think Elevance Health's shares could be worth.
The issue now is whether Elevance Health's current US$429.65 share price is adequately explained by its earnings when set against the Fair Ratio benchmark.
If you want more context around whether Elevance Health's recent 39.0% one year return feels stretched or reasonable, it can help to line it up against 30 resilient stocks with low risk scores.
Does Elevance Health Look Undervalued on Earnings?
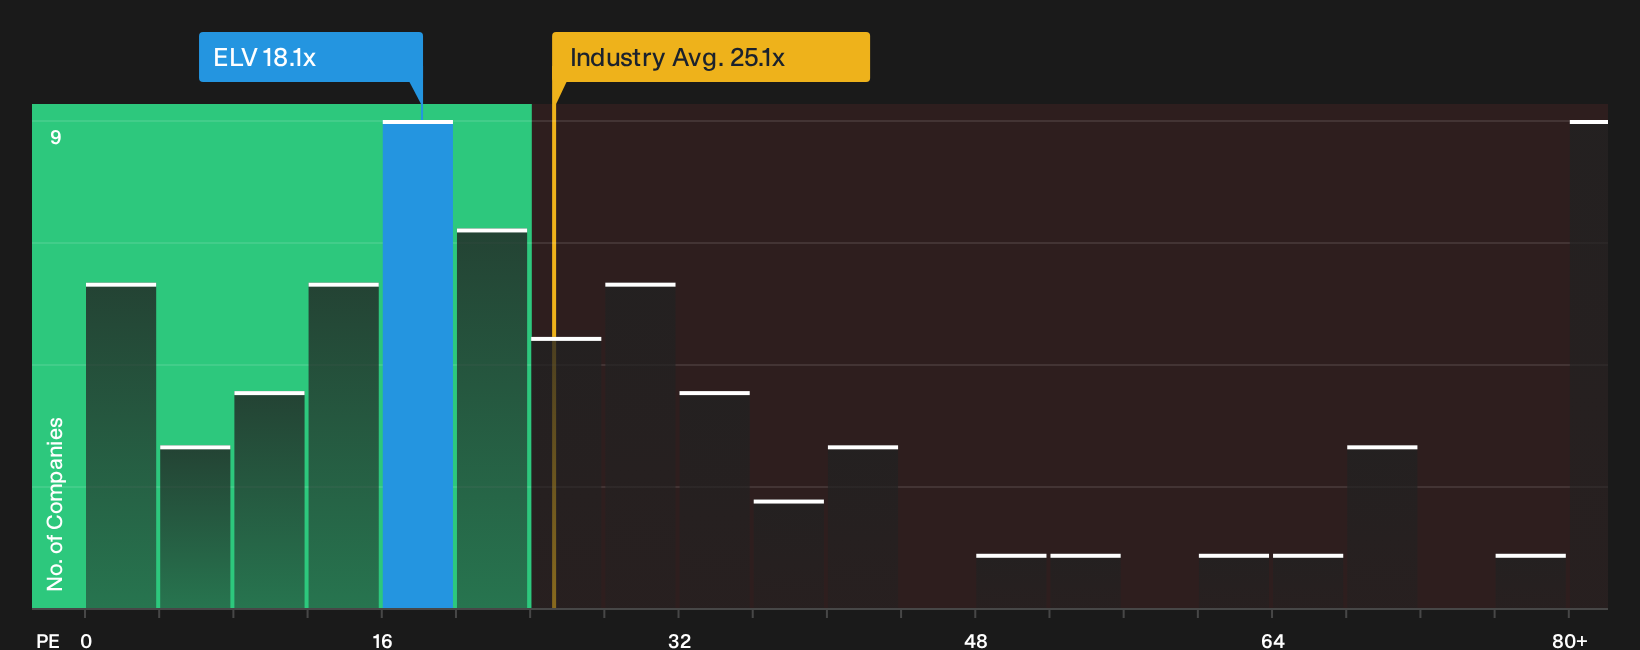
The P/E ratio fits Elevance Health well because earnings remain the main driver of how investors frame large health insurers. On this yardstick, Elevance Health trades at roughly 18.1x earnings, which comes in below the Healthcare sector average of about 25.1x and sits even further under the peer group near 31.3x. Based on a Fair Ratio that blends the company’s growth profile, profitability, size and risk, that gap points to the shares screening as undervalued on earnings.
Because management is talking about at least 12% adjusted EPS growth in 2027 and better Medicaid margins after a 2026 trough, the current discount on the P/E line suggests the market is pricing Elevance Health more cautiously than those aspirations might imply. Despite the lawsuit over alleged fraudulent billing by The Perfect Child ABA drawing attention to operational and legal risks, the multiple still leaves Elevance Health trading below what this earnings based framework would suggest. Explore the numbers behind Elevance Health's P/E valuation.
The Elevance Health Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Elevance Health valuation puzzle leaves off and spell out which future paths for growth, margins and earnings would need to hold for the stock to be worth materially more or materially less than today’s price on the Community page. Each narrative ties its number to a specific view on how Elevance Health's growth, profitability and risk profile could evolve, giving you a reference point to revisit as fresh information emerges.
Bulls see Elevance Health getting more credit for its tech and care platforms than bears are willing to give it right now.
Bull case: 9% undervalued
This view comes from the analyst consensus Narrative on Simply Wall St, which leans on Street forecasts and targets.
"Ongoing deployment of Elevance Health’s AI, analytics and digital platforms such as HealthOS and Sydney Health, including automated prior authorization and earlier visibility into medical cost trends, is expected to tighten medical cost management and support more stable net margins and earnings over time…"
Discover why this Narrative puts Elevance Health at 9% undervalued.
Bear case: roughly fairly valued
The cautious side is drawn from the bearish analyst Narrative on Simply Wall St, which builds off the lowest implied targets.
"Although Elevance Health reports that CareBridge and other Carelon programs are producing double digit medical cost savings in targeted groups, persistent elevated utilization in behavioral health, specialty pharmacy and emergency departments suggests these savings may not scale fast enough across the wider book…"
Explore why this Narrative puts Elevance Health at roughly fairly valued.
One more Elevance Health angle worth checking before you decide
There is one piece of Elevance Health that sits outside the valuation story so far, which is the specific risk checks our research has triggered and how they might affect your comfort level as a holder. Take a closer look at 1 warning sign before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com