


- Trip.com Group reported that global aurora-viewing tour bookings rose 225% year-on-year and Northern Lights searches increased 132%, with heightened demand across Finland, Norway, Sweden, Iceland, Canada and China's Mohe city.
- The company is tying this surge in interest to its TripGenie AI trip planner, which is now helping travellers turn aurora searches into concrete bookings.
- We will look at how Trip.com Group's investment narrative is influenced by surging aurora-tour demand and TripGenie driven booking activity.
Scan 41 profitable AI stocks that aren't just burning cash that are already turning AI travel assistants and real booking demand into cash flow, just as Trip.com Group is using TripGenie to capture aurora tourism interest.
Trip.com Group Investment Narrative Recap
To own Trip.com Group, you need to believe the travel platform can keep turning product usage like TripGenie and niche demand such as aurora tours into repeat, monetizable bookings across accommodation, transport and in-destination services. In the short term, the key swing factor remains how effectively this AI layer converts curiosity into orders without letting customer acquisition costs or service quality drift.
The biggest risk, highlighted by LunaRodas, a Simply Wall St Community investor who wrote the Narrative, is that earnings are forecast to decline over the next 3 years while recent results still contain large one off items. The aurora surge looks supportive for near term activity but does not, on its own, change that earnings quality debate.
The upcoming Trip.com Group presentation at Citi's 2026 China Conference in Shenzhen appears to be the key near dated disclosure tied to this story. Management now has fresh, concrete data on aurora bookings and TripGenie usage, so investors can watch how much airtime Jie Sun gives these themes and what extra numbers are shared around AI assisted orders.
Conference commentary will also sit against existing flags in the data, such as earnings growth that recently slowed relative to the 5 year pace and forecasts that point to declining profits despite current P/E and cash flow based value metrics that look undemanding. If the talk track at Citi leans into unit economics, AI driven conversion and post regulation partner terms, it may help readers judge whether the aurora boom is a one season spike or part of a broader execution story.
LunaRodas sets the narrative’s fair value for Trip.com Group at US$46.83, based on the view that a clearer regulatory outcome and quantifiable TripGenie usage data now give investors a more measurable picture of how the business is executing on its stated commitments.
Uncover why Trip.com Group's fair value indicates a 6% potential upside to its current price that could narrow quickly.
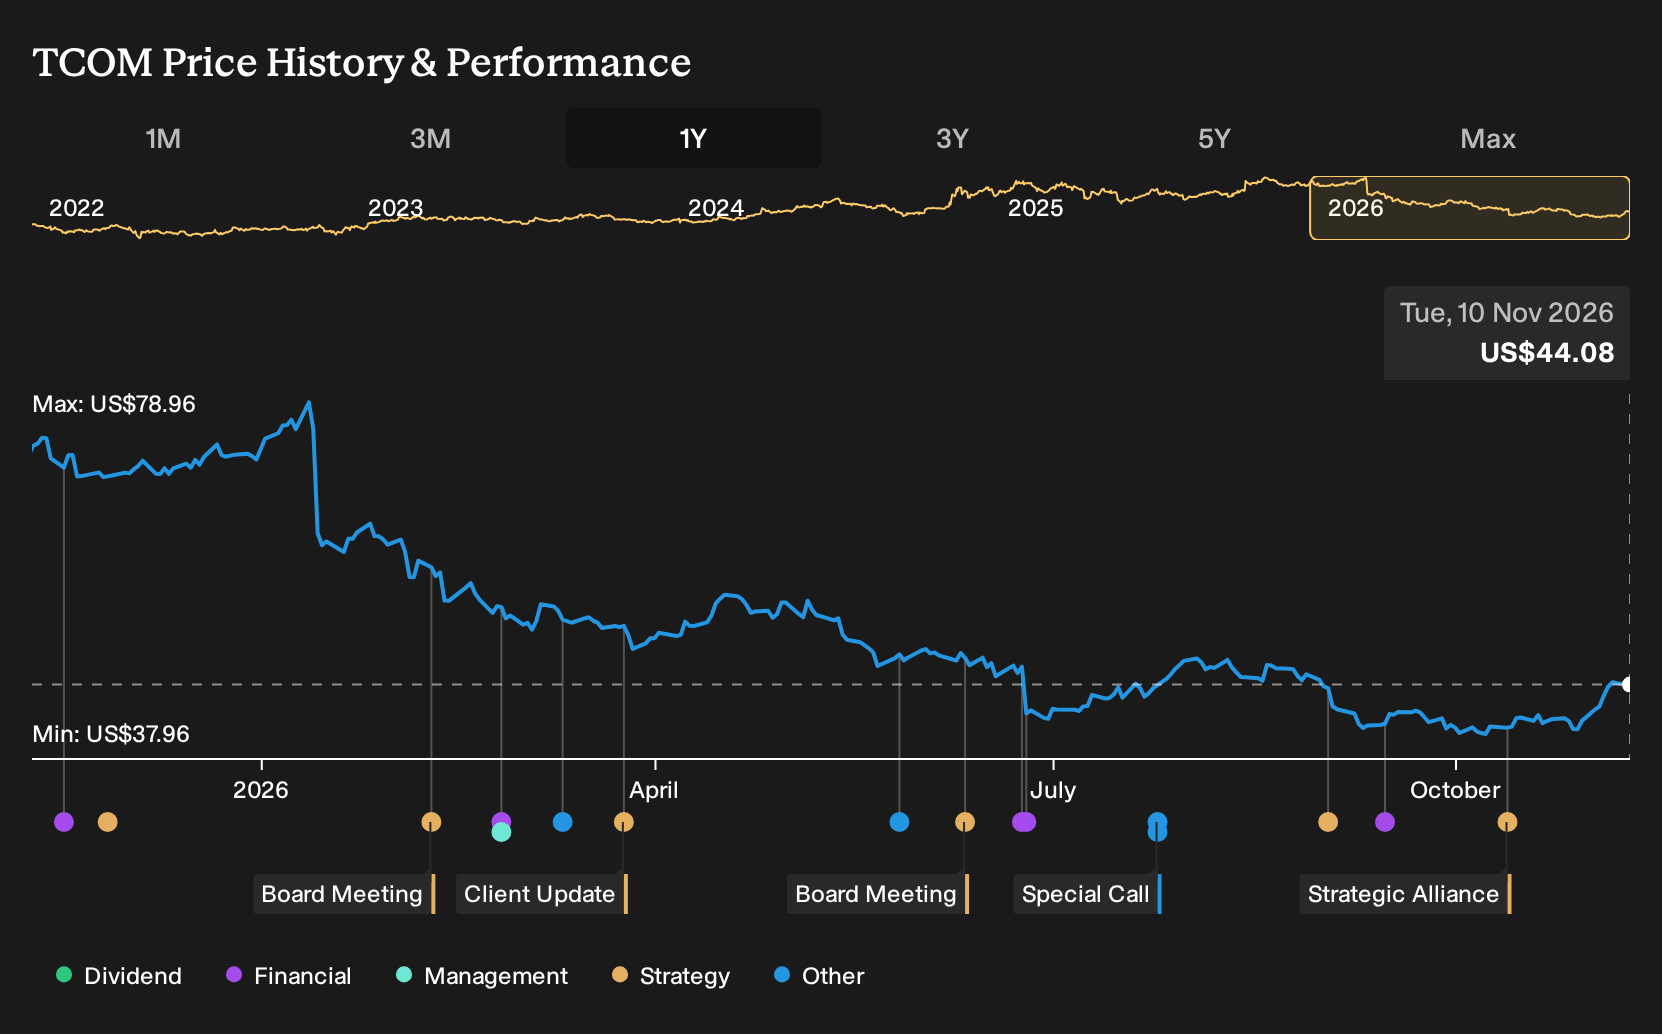
Exploring Other Perspectives
One alternate Trip.com Group story focuses on its large cash position and earlier bullish forecasts. Before this aurora spike, the most optimistic analysts were modeling revenue of CN¥91.1b and earnings of CN¥18.8b by around 2029. That group sounds far more upbeat. Use those assumptions as a reference point and consider how they might shift now.
Explore 4 other Trip.com Group fair value estimates, including one that suggests as much as 231% upside from the current price.
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Trip.com Group research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Trip.com Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Trip.com Group's overall financial health at a glance.
Looking For More Ideas Beyond Trip.com Group?
Once you have a view on Trip.com Group, it can help to set it alongside other opportunities and see how it stacks up on income, value and balance sheet strength. The Simply Wall St Screener lets you do that quickly by filtering the market down to companies that match the kind of risk and return profile you actually want.
- If you want income to play a bigger role in your returns, take a look at 5 dividend fortresses that focus on higher yield potential with an eye on resilience.
- For readers who care most about paying a reasonable price, there is a curated 35 high quality undervalued stocks that combine quality fundamentals with more modest market expectations.
- If capital protection matters to you as much as upside, consider a 30 resilient stocks with low risk scores that have been filtered for more durable financial profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com