


Why InterDigital’s latest earnings matter for investors
InterDigital (IDCC) has drawn attention after reporting third quarter 2026 results that showed higher sales and net income year over year, while also lifting full year guidance based on revenue already under contract.
InterDigital’s latest earnings drop into a choppy year for the stock, with the share price down 16.76% over the past 90 days and 11.71% over the last month, even as management raised full year guidance and highlighted contracted revenue support. At a share price of US$292.52, short term momentum has cooled; however, the three year total shareholder return of about 223% and five year total shareholder return of roughly 331% still point to a long run story that has rewarded patient holders even through this recent pullback.
Scan how InterDigital’s earnings reset compares with peers by lining it up against 41 profitable AI stocks that aren't just burning cash that already pair real cash generation with AI exposure.
InterDigital’s price has slipped while analyst estimates and intrinsic value models still sit much higher. Is that gap a warning signal or an opening as the valuation work begins?
Most Popular Narrative: 37% Undervalued
InterDigital’s analyst consensus Narrative on Simply Wall St points to a fair value of about $462.67 per share, which sits well above the last close at $292.52 and anchors a valuation view built on recurring licensing and cash on hand.
The shift in InterDigital’s licensing mix toward streaming and cloud video services, supported by the Amazon agreement that currently recognizes revenue on a conservative estimate during arbitration, leaves scope for higher recurring revenue and earnings if the final award comes in above the booked level.
See why 19 investors see InterDigital as 37% undervalued.
Result: Fair Value of $462.67 (UNDERVALUED)
Still, two pressure points could flip that undervalued InterDigital story: an unfavorable Amazon arbitration outcome and higher lasting enforcement costs that squeeze margins.
Find out about the key risks to this InterDigital narrative.
Another view on InterDigital’s valuation
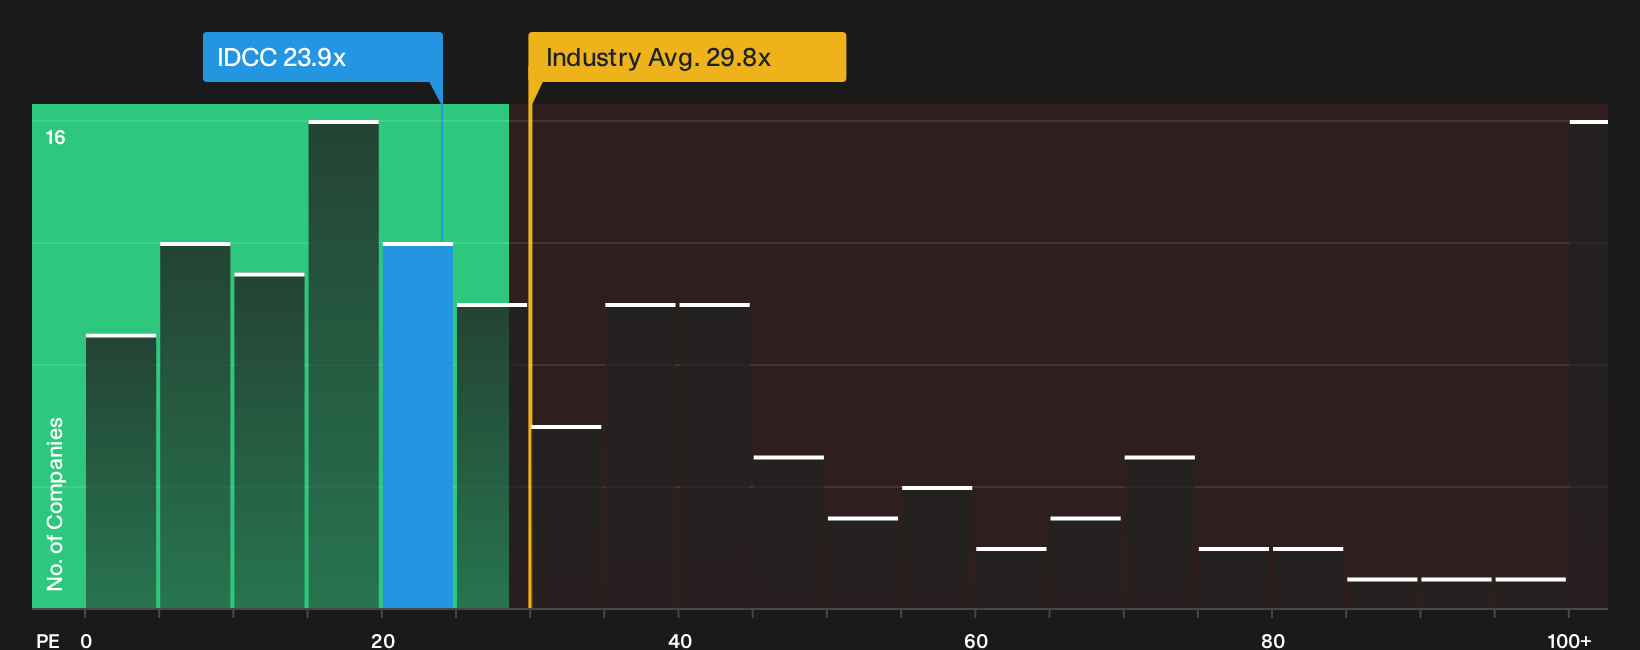
InterDigital looks cheap against the US Software industry on a simple P/E yardstick, trading at 23.9x compared with the sector on 30.3x and peers at 28.2x. Yet it trades above a fair ratio of 19.7x, which flags less room for error if earnings forecasts prove optimistic.
That split between relative value and the lower fair ratio leaves you weighing whether the discount to peers is a cushion or whether the multiple could drift closer to 19.7x if expectations reset. This may be particularly relevant with revenue and earnings both forecast to decline over the next 3 years.
To see how that P/E gap lines up with the underlying numbers and where the market could shift next, take a closer look at the valuation breakdown in See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on InterDigital’s value story can make it hard to know which way to lean, so move quickly to test the data and pressure test your own thesis against the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond InterDigital?
If InterDigital’s story has your attention, do not stop there. Use the same disciplined lens across a wider watchlist so you are not relying on a single opportunity.
- Target value opportunities early by scanning a curated 20 high quality undiscovered gems that pair strong fundamentals with less crowded attention.
- Shield your capital from surprise shocks and focus on stability by filtering for 30 resilient stocks with low risk scores that score well on resilience.
- Anchor your portfolio with reliable balance sheets by reviewing a list of solid balance sheet and fundamentals (24 results) before the rest of the market catches up.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com