


- Ford Motor (NYSE:F) appointed former General Motors executive Marissa West as vice president of vehicle programs.
- West will oversee development across Ford's global vehicle portfolio as it readies a broad product refresh through 2029.
- The hire places a veteran GM leader at the center of Ford's next wave of electric and internal combustion model launches.
- The appointment of Marissa West to lead vehicle programs is a key leadership shift to weigh against our other findings. Take a look at 2 warning signs (1 major) we have identified for Ford Motor.
For readers looking beyond Ford to other ways to play the auto technology buildout, start with 53 AI infrastructure stocks.
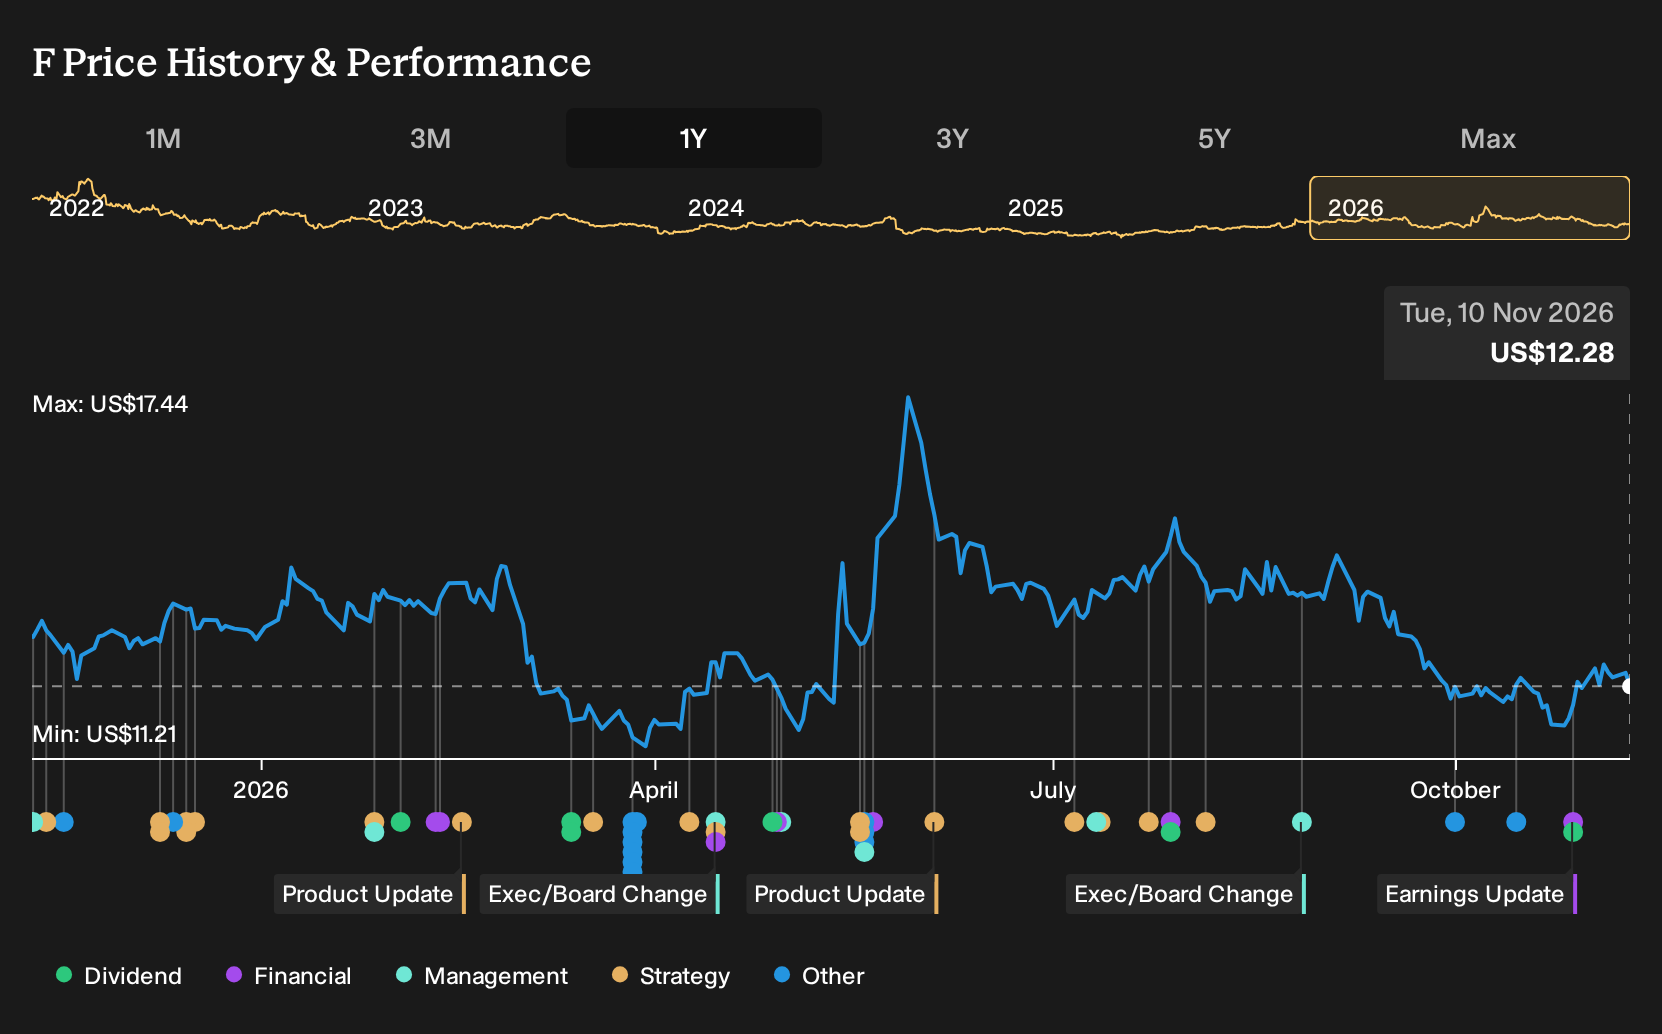
Ford Motor runs a broad auto business that designs, builds, and services trucks, SUVs, commercial vans, passenger cars, and Lincoln luxury models across the US, UK, Mexico, Canada, and other markets. As a result, shifting who oversees vehicle programs directly affects a large, global product slate.
Why does bringing in a former GM executive matter for Ford Motor now?
Ford is in the middle of refreshing roughly three quarters of its global portfolio by 2029, including new EVs and midsize pickups, so who owns the product pipeline matters for execution risk. Marissa West arrives with long experience in high volume model programs, which can help Ford align engineering, cost targets and launch timing across both Ford Blue and Model e projects.
Does this leadership move change the Ford Motor Narrative?
The current Narrative leans on Ford hitting an 8% EBIT margin by 2029 through quality gains, lower recall and warranty costs, and a shift to a Universal EV platform plus Ford Energy. Putting West over vehicle programs goes straight at that goal, because consistent product development is needed to support those cost cuts and to commercialise the new EV and energy platforms at scale.
See how these catalysts shape Ford Motor's path to a $15.28 fair value.
What should investors watch to see if this hire is paying off?
The cleaner signal will be whether Ford’s recalls and material and warranty costs track towards the US$1b reduction the company has targeted for 2026 while it rolls out new trucks and EVs. If major launches stay on schedule and quality metrics hold up through 2027, that would suggest the new vehicle programs leadership structure is working.
What question about Ford Motor’s destination a few years from now is still unanswered?
Short news hits the headline events, but the longer story sits in where the multi year projections say Ford Motor could end up and how different that picture looks from today. See where analysts expect Ford Motor to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com