


Karman Holdings (KRMN) drew fresh attention after its third quarter 2026 earnings call, where management highlighted ongoing acquisition plans, raised full year revenue guidance, and outlined capacity to fund deals with an untapped US$150 million credit facility.
Karman Holdings’ share price has been volatile, with a 1 month share price return of 34.73% and a 7 day gain of 11.14%. However, the stock remains down 29.07% over 3 months, and the 1 year total shareholder return is lower by 36.71%, which suggests recent momentum has picked up again after a tougher stretch for longer term holders.
Scan other space and defense contractors with similar acquisition activity and earnings trends by zeroing in on our hand picked list of solid balance sheet and fundamentals (24 results).
After a sharp rebound in Karman Holdings on the back of stronger guidance and active M&A plans, the key question is straightforward: Do current expectations already incorporate most of the potential upside, or does the valuation still leave room for buyers?
Most Popular Narrative: 58% Undervalued
Karman Holdings last closed at $43.91, while the leading narrative on the stock pegs fair value at $105.60. This frames a wide valuation gap for investors to interrogate according to FundamentalFlow, an investor in the Simply Wall St Community who authored the narrative.
"By January 2026, it was trading at $118. Today, it is at $49.50, a 58% collapse from peak, yet the underlying business just posted its best quarter in company history. That kind of divergence between price and fundamentals is worth examining very carefully."
See why 47 investors see Karman Holdings as 58% undervalued.
The narrative applies an 8.22% discount rate to arrive at that $105.60 figure, and leans heavily on rapid revenue and earnings growth expectations plus a sizeable order backlog to argue that the current share price undervalues Karman Holdings.
It also treats the sharp share price pullback, volatile recent returns and heavy use of debt as risks that might be obscuring the growth story rather than disproving it, while still flagging leverage and integration as issues that could limit how quickly sentiment improves.
Result: Fair Value of $105.60 (UNDERVALUED)
Still, Karman Holdings faces two clear swing factors: high leverage tied to floating rates and the risk that recent acquisitions integrate more slowly than hoped.
Find out about the key risks to this Karman Holdings narrative.
Another View: What Karman Holdings’ P/E Ratio Signals
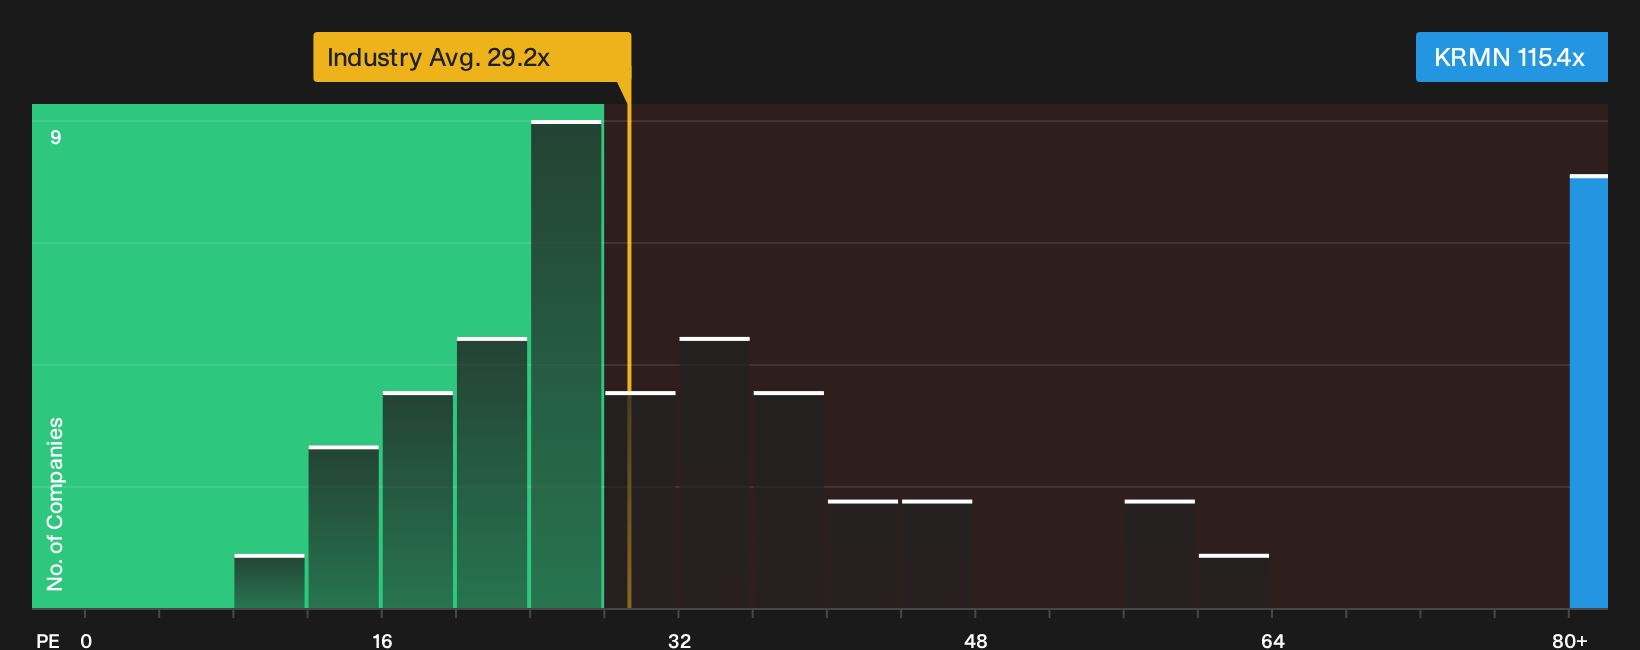
Karman Holdings screens very differently when the focus shifts to its P/E ratio. The stock trades at 115.4x earnings, compared with 29.2x for the broader US Aerospace & Defense group and a 57.6x peer average. The fair ratio is 67.2x, which points to valuation risk if sentiment cools.
If the share price eventually tracks closer to that fair ratio instead of the higher current level, it raises the question of how much confidence investors can place in the optimistic growth assumptions reflected in today’s multiple.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed on Karman Holdings after all this? Act while the information is fresh and review the full set of concerns and positives in our 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Karman Holdings?
Do not stop your research with Karman Holdings. Fresh opportunities keep surfacing, and it can help to use a focused screener to explore them.
- Target resilient wealth builders by reviewing companies that combine income with staying power through the 5 dividend fortresses.
- Spot potential value setups early by scanning the 20 high quality undiscovered gems before attention and liquidity crowd in.
- Prioritise sleep at night holdings by filtering for businesses that score well on stability and financial strength using the 30 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com