


- Astera Labs reported third quarter 2026 sales of US$584.9 million and net income of US$182.94 million, and guided fourth quarter revenue to a range of US$730 million to US$750 million, while also announcing the past resignation of board member Michael Hurlston effective November 3, 2026, with no stated disagreements.
- The combination of strong third quarter profitability, a projected 27% sequential revenue increase for the fourth quarter, and confirmation of stable governance appears to highlight Astera Labs' operating momentum and execution around AI data center connectivity demand.
- We will now look at how Astera Labs' higher fourth quarter revenue outlook could reshape the investment narrative built around AI connectivity.
Scan how Astera Labs’ AI connectivity story compares with other potential breakout infrastructure plays by reviewing the hand-picked 53 AI infrastructure stocks in this space.
Astera Labs Investment Narrative Recap
To own Astera Labs, an investor needs to believe that high speed connectivity inside AI data centers remains a bottleneck and that this business can keep solving those problems across new standards. The latest third quarter revenue of US$584.9 million and net income of US$182.94 million, paired with guided fourth quarter revenue of US$730 million to US$750 million, keeps that operating story intact.
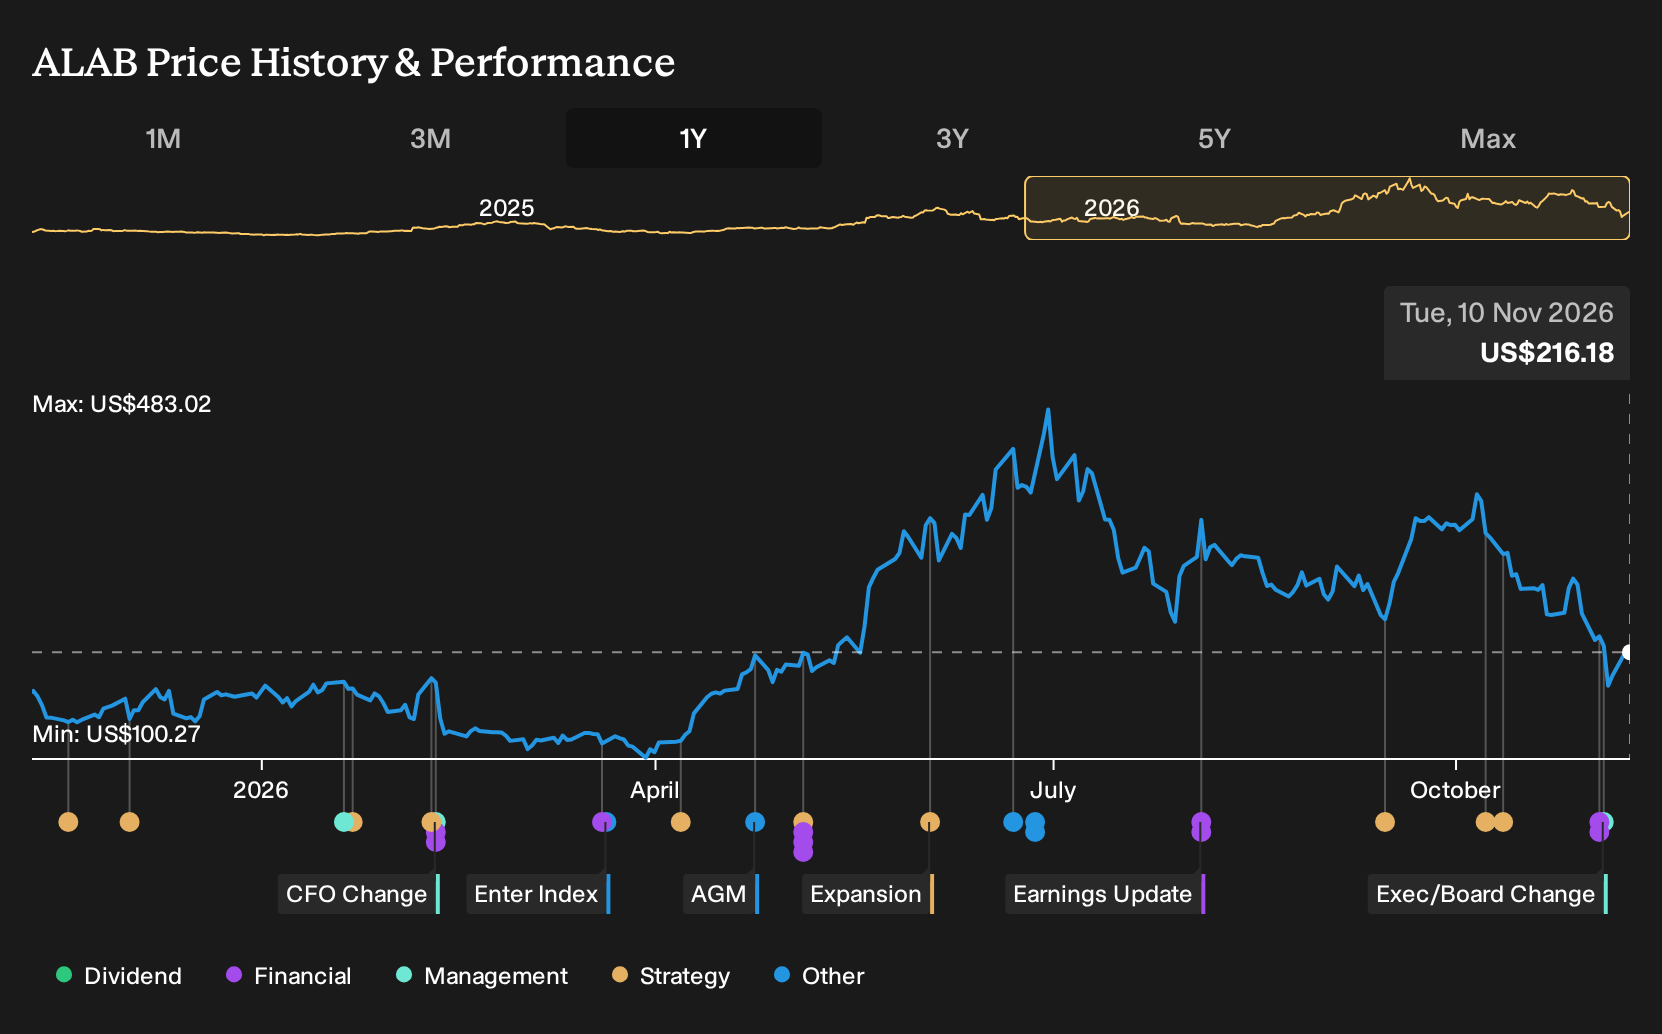
The near term catalyst still sits in continued AI rack deployments and content per accelerator, which recent guidance directly relates to. The biggest risk remains concentration in AI infrastructure spending and a rich P/E of 81.9x, which can amplify volatility if hyperscaler ordering patterns soften or expectations reset.
The most relevant update here is the fourth quarter 2026 revenue outlook. Management is guiding to US$730 million to US$750 million, with the midpoint implying 27% sequential growth. For readers focused on catalysts, that range ties directly to how quickly AI data center projects convert into orders for Astera Labs hardware and software.
This forecast matters more than short term ETF flows or board changes when thinking about execution. Stronger near term activity could support the view from isidrohg, an investor in the Simply Wall St Community, that content per accelerator is central to the thesis, while the elevated valuation and share price swings keep execution risk and sentiment shifts front of mind.
According to isidrohg’s analysis, Astera Labs reaches a fair value of US$628.83 by pairing 36.0% annual revenue growth with a future profit margin of 30.7%. Together, these factors support a high earnings power narrative once the business scales into its AI connectivity workloads over time.
Uncover why Astera Labs' fair value indicates a 191% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Astera Labs looks very different if you focus on the bullish catalyst around Aries 7 PCIe 7 and the optical roadmap. The most optimistic analysts were already penciling in revenue of about US$6.1b and earnings of US$1.7b by 2029 before this quarter’s guidance and board change, so their narrative could shift sharply as new information lands.
Explore 6 other Astera Labs fair value estimates, including one that suggests as much as 191% potential upside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Astera Labs research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Astera Labs. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Astera Labs' overall financial health at a glance.
Looking for more Astera Labs style investment ideas?
If the Astera Labs story has you thinking about what else might be hiding in plain sight, it can help to cast a wider net using structured stock lists instead of scrolling tickers at random.
- For readers who care most about valuation support and balance sheet strength, consider screening for companies that combine quality with a discounted price tag by checking the 35 high quality undervalued stocks.
- If resilience and capital preservation sit higher on your priority list, filter for businesses with lower risk profiles and steadier fundamentals through the 30 resilient stocks with low risk scores.
- When you want to hunt for earlier stage opportunities that still have solid foundations, focus on stocks with robust financials that are not yet widely followed by reviewing the 20 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com