


Matador Resources has delivered a 28.1% share price gain over the past year, even after a recent pullback, which puts a spotlight on whether that move lines up with what its earnings can support. With fresh operating updates and new infrastructure agreements in the mix, the key issue is how much of that story is already embedded in today's valuation.
- The 28.1% return over the last 12 months raises a simple question for Matador Resources investors: how much of the business's earnings power is already reflected in the current price.
- Recent production growth, reserve additions and midstream expansion through San Mateo Midstream may support expectations for more stable earnings and cash generation over time, which feeds directly into what investors are prepared to pay for each dollar of profit.
- There is a second opinion on Matador Resources worth weighing. See what analysts think Matador Resources's shares could be worth.
The issue now is whether Matador Resources' current share price around US$50 fairly reflects its earnings when set against the Fair Ratio benchmark.
If this has you wondering how other companies with earnings stories under the microscope are priced today, take a look at 35 high quality undervalued stocks.
Is Matador Resources Still Cheap on Earnings?
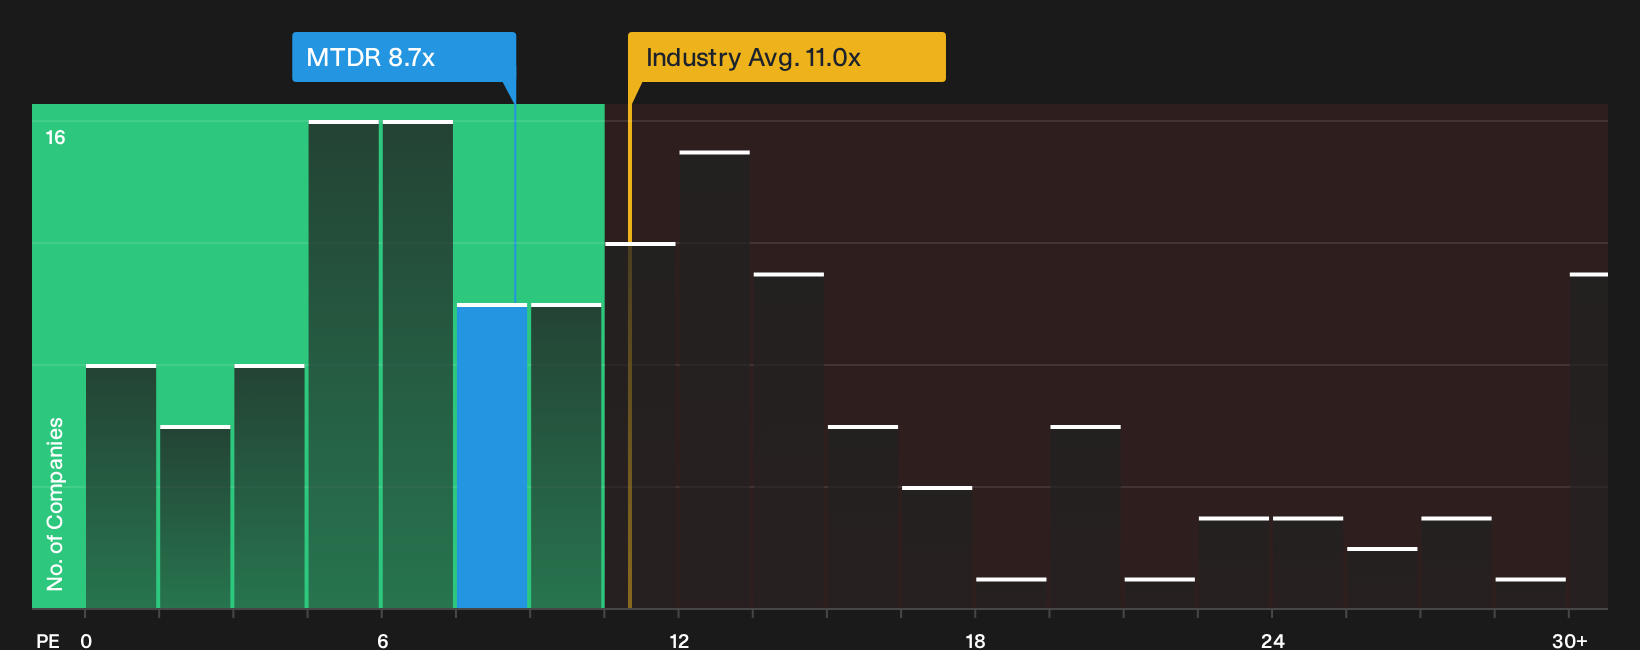
The P/E ratio tends to fit Matador Resources because earnings are a key focus for investors in profitable oil and gas producers. On this yardstick, Matador Resources trades on about 8.7x earnings, which is below the broader oil and gas sector average of roughly 11.0x and well under the peer group on about 26.1x. The Fair Ratio model, which adjusts for the company’s own growth profile, margins, scale and risk, points to a higher multiple than where the shares trade today, so the current P/E sits on the undervalued side of that benchmark.
Because the recent Q3 2026 update highlighted higher production and expanded reserves along with integrated midstream exposure through San Mateo, this lower P/E suggests the market is still pricing Matador Resources at a discount despite that operating backdrop. For investors, the key judgment is whether the earnings that underpin this 8.7x P/E look durable enough to merit something closer to what similar oil and gas businesses command. Explore the numbers behind Matador Resources's P/E valuation.
The Matador Resources Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the valuation questions around Matador Resources leave off by spelling out which paths for future growth, margins and earnings would need to play out for the stock to be worth materially more or less than it is today, and they sit on the company’s Community page. Each narrative treats fair value as a hypothesis about Matador Resources' business that can be tracked over time rather than a one off snapshot.
One of the top narratives on Matador Resources: 15% undervalued
This Narrative is the bearish analyst Narrative on Simply Wall St, built on the most pessimistic analyst price target and forecasts, not one person's view.
"The current valuation implies the market is pricing Matador Resources as if recent revenue volatility and macro driven share price swings will outweigh the potential benefits..."
Discover why this Narrative puts Matador Resources at 15% undervalued.
One more angle on Matador Resources that could change the story
Even with the focus on earnings and valuation, the people setting Matador Resources' priorities and how they are rewarded can strongly influence where the business goes next. See who runs Matador Resources and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com