


Element Solutions (ESI) has drawn fresh attention after a recent pullback, with the share price closing at US$32.75 and declining over the past week, month and past 3 months.
Recent trading has cooled some of that enthusiasm, with the share price retreating over the past week, month and quarter. Element Solutions still carries a 26.25% year to date share price return and a 3 year total shareholder return of 66%, which suggests earlier momentum is now being tested as investors reassess growth potential and risks at around US$32.75.
Scan how Element Solutions compares with other materials players under pressure right now by reviewing the hand picked 30 resilient stocks with low risk scores in the same market segment.
The recent pullback has created a very different entry setup for Element Solutions compared with earlier in the year. Does it make sense to step in at US$32.75 now, or is it better to wait until valuation is discussed next?
Most Popular Narrative: 30% Undervalued
Against a last close of $32.75, the analyst consensus Narrative on Simply Wall St anchors Element Solutions at a fair value of $46.45, implying a sizeable valuation gap that investors now weigh against the recent pullback.
The shift in Element Solutions' portfolio toward electronics end markets, with more than 70% of revenue now from electronics and roughly 75% of that sold into B2B and enterprise customers, reduces reliance on mobile devices at about 5% of total revenue and can support more stable, higher value revenue and margin mix over time.
Element Solutions' portfolio of specified, qualified consumables with high switching costs and intensive technical service, combined with disciplined capital allocation that keeps net leverage below the 3.5x ceiling and capex at roughly 3% of sales while focusing spend on high return projects, underpins ex metals adjusted EBITDA margins that reached 27.8% in Q2 2026 and supports the potential for further margin and earnings expansion.
See why 4 investors see Element Solutions as 30% undervalued.
The same Narrative applies a 7.65% discount rate to those future cash flows and earnings, which is the hurdle used to translate analyst forecasts into today’s $46.45 fair value estimate for Element Solutions.
Result: Fair Value of $46.45 (UNDERVALUED)
Still, the narrative around Element Solutions can weaken if raw material and logistics costs remain elevated, or if AI and data center spending slows more quickly than analysts expect.
Find out about the key risks to this Element Solutions narrative.
Another View: Element Solutions Looks Expensive On Earnings
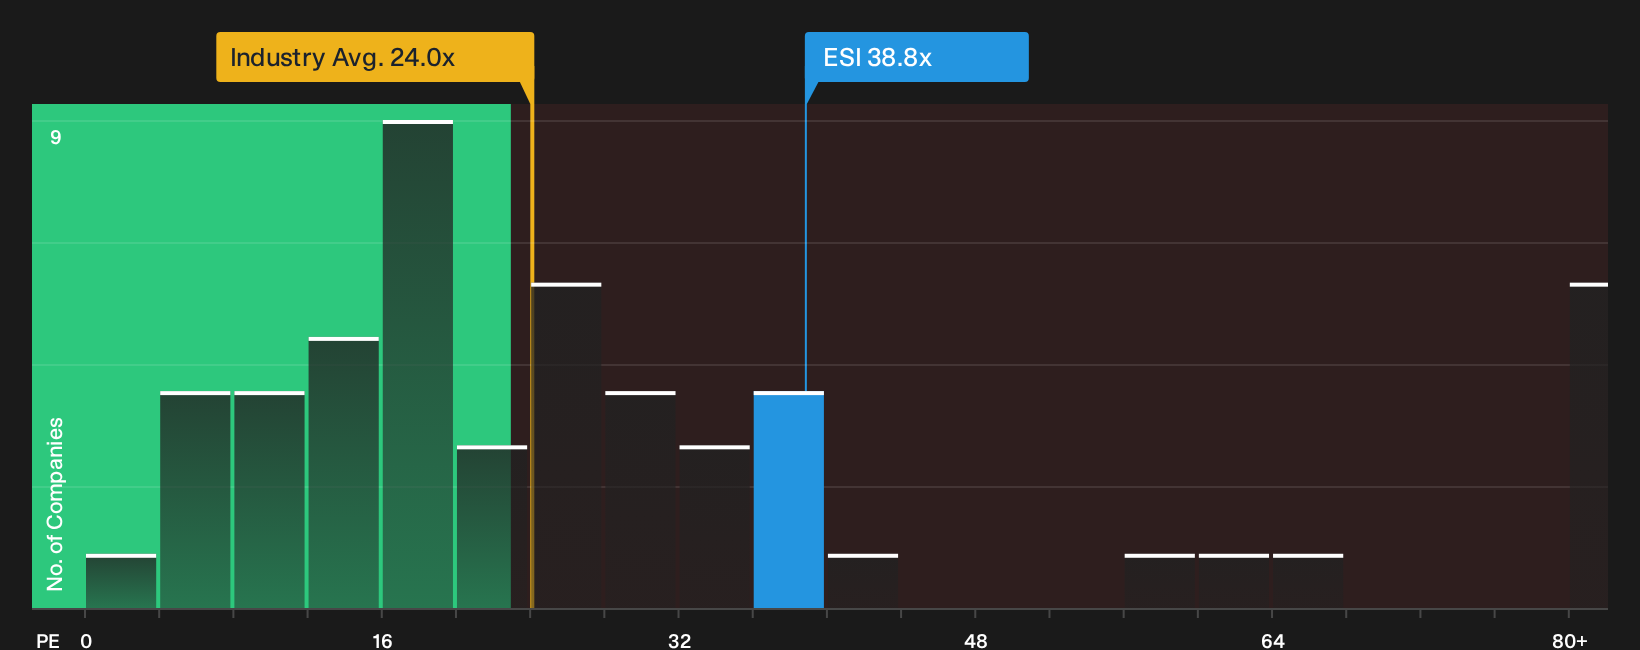
The DCF based fair value points to upside for Element Solutions, yet the current P/E ratio of 38.8x tells a different story. That multiple is well above both the US Chemicals industry at 24.1x and the stock's own fair ratio of 28.2x, which implies investors are already paying up for future growth that still has to be delivered. How comfortable are you paying a premium entry price when the market could drift back toward that fair ratio?
To see how this earnings based view stacks up against a full intrinsic value approach, review the SWS DCF workup for Element Solutions next, starting with the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed messages in the Element Solutions story so far. If you want to move quickly and form your own stance, start with the 3 key rewards and 2 important warning signs.
Looking for more Element Solutions style investment ideas?
If Element Solutions has you thinking harder about price, quality and risk, spread that effort across a wider watchlist and give yourself better options.
- Target quality at a discount by scanning a curated pool of companies with strong fundamentals using the 35 high quality undervalued stocks.
- Build a sturdier portfolio core by zeroing in on businesses screened for balance sheet strength via the list of solid balance sheet and fundamentals (24 results).
- Get ahead of the crowd by tracking quieter opportunities with strong metrics filtered through the 20 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com