


T-Mobile US has seen its share price move sharply in recent years, and with earnings now in the spotlight, the question is whether the current valuation still lines up with what the business is actually earning. Recent headlines around its parent Deutsche Telekom, changing partner relationships, and product expansion only sharpen the focus on how much of T-Mobile's earnings story may already be built into the price.
- Over the past 5 years, T-Mobile US has delivered a total return of 50.2%, which puts real weight on whether its present earnings can support that kind of share price journey.
- Deutsche Telekom's higher medium term targets for the U.S. unit, alongside T-Mobile's reported adjusted EBITDA AL growth and account additions, can shape how investors think about the durability of earnings and the multiple they are prepared to pay.
- Your read on T-Mobile US is one view; the desks covering it have another. See what analysts think T-Mobile US's shares could be worth.
The stock's next move may depend on whether T-Mobile US's current price can be justified by its earnings when set against the Fair Ratio benchmark.
If you are weighing T-Mobile US against other opportunities and want a tighter starting list, a focused screen of 35 high quality undervalued stocks can provide a broader view of earnings and valuation.
Does T-Mobile US Look Undervalued on Earnings?
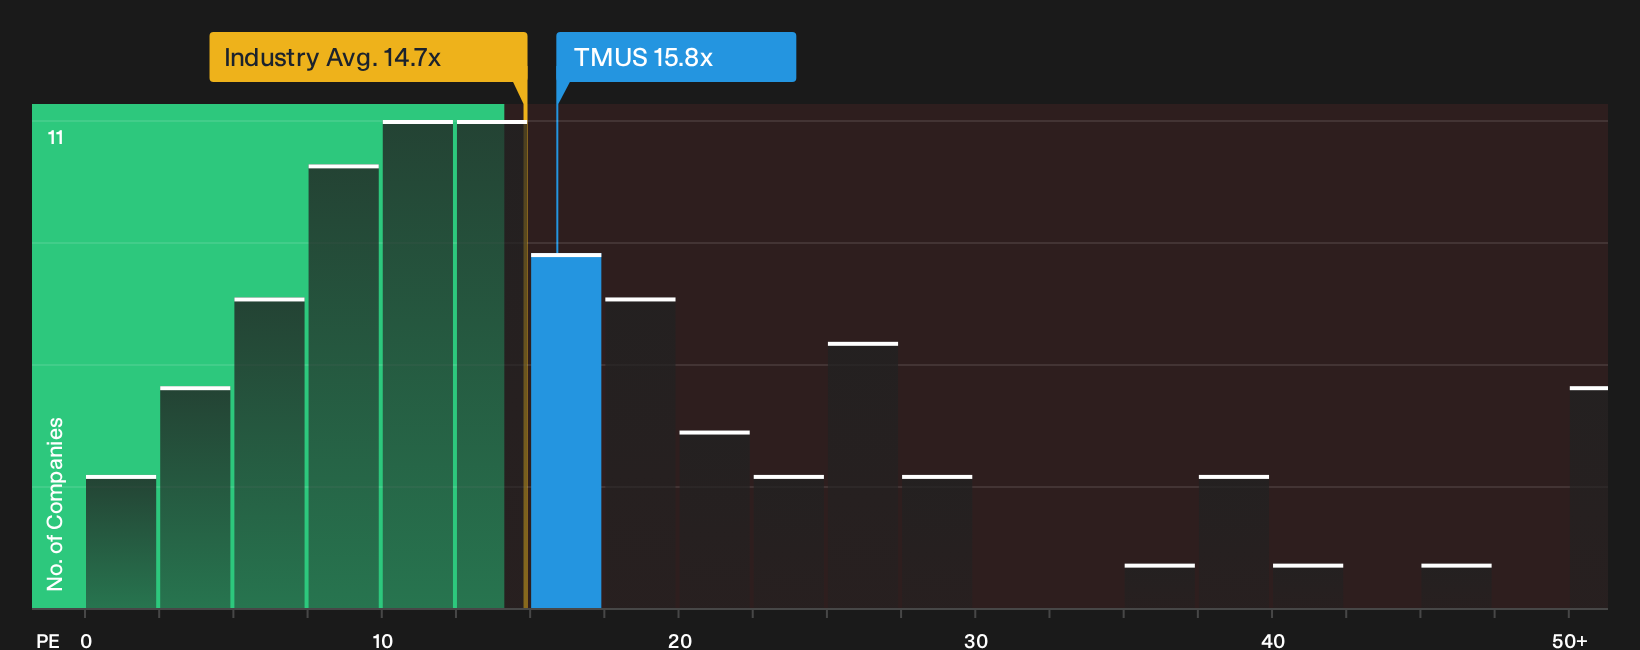
The P/E ratio suits T-Mobile US because earnings remain a key yardstick for mature, cash generative telecom groups. The stock trades on a P/E of about 15.8x, which is very close to both the Wireless Telecom industry average of roughly 14.7x and the peer group on about 15.6x. On a simple comparison, the market is attaching only a small premium to T-Mobile US relative to its sector.
Fair Ratio modelling, which adjusts for factors like margins, scale and perceived risk, points to a higher P/E than where the shares trade today. As a result, the current multiple screens as undervalued on this framework. Deutsche Telekom's higher medium term targets for the U.S. unit and T-Mobile US reporting 11.4% adjusted EBITDA AL growth sit against a valuation that still prices the equity below that Fair Ratio marker. For investors, the key question is whether those fundamentals and targets justify the gap that the Fair Ratio suggests. Explore the numbers behind T-Mobile US's P/E valuation.
The T-Mobile US Narrative: What Would Justify Today's Price?
T-Mobile US' Simply Wall St Narratives sit between the current valuation puzzle and the assumptions that could push the share price meaningfully higher or lower over time, spelling out in plain language what would need to happen to growth, margins and earnings for those outcomes to make sense. Instead of leaving you with just a single model output, they unpack the future that number leans on so you can watch how the actual story lines up with it on the Community page.
Views on T-Mobile US split between those who see more upside in the current multiple and those who think expectations already look full.
Bull case: 26% undervalued
This view comes from the analyst consensus Narrative on Simply Wall St, which leans on shared Street forecasts and targets.
"The current valuation implies the share price does not fully reflect the uplift from higher 2030 broadband targets, rising free cash flow guidance and ongoing buybacks…"
Discover why this Narrative puts T-Mobile US at 26% undervalued.
Bear case: roughly fairly valued
This angle reflects the bearish analyst Narrative on Simply Wall St. It is built from the most cautious forecasts and assumptions.
"Although T-Mobile is leaning into its 5G advanced network and physical AI partnerships, including Figure AI robots and live translation embedded in the core network, the need for sustained capital investment and uncertain monetization paths could weigh on future net margins and the pace of earnings growth…"
Explore why this Narrative puts T-Mobile US at roughly fairly valued.
T-Mobile US valuation still leaves one crucial piece of the story unanswered
Earnings, targets and multiples only tell part of the picture for T-Mobile US, because recent checks also highlight specific business risks that investors may want to weigh before relying on the current pricing. Take a closer look at 1 warning sign before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com