


- AAON (NasdaqGS:AAON) reported a material weakness in internal controls over financial reporting tied to its 2026 quarterly results.
- The company plans to restate its first and second quarter 2026 financial statements to correct errors identified in its reporting process.
- Alongside the control issue, AAON announced record third quarter 2026 results and raised its full year 2026 sales outlook.
- The internal controls weakness, restatements and updated 2026 outlook are only part of the broader AAON story. Our analysis turns up 3 other big wins for AAON as well.
For a wider view on companies exposed to similar demand trends, explore related stocks in the same space through 53 AI infrastructure stocks.
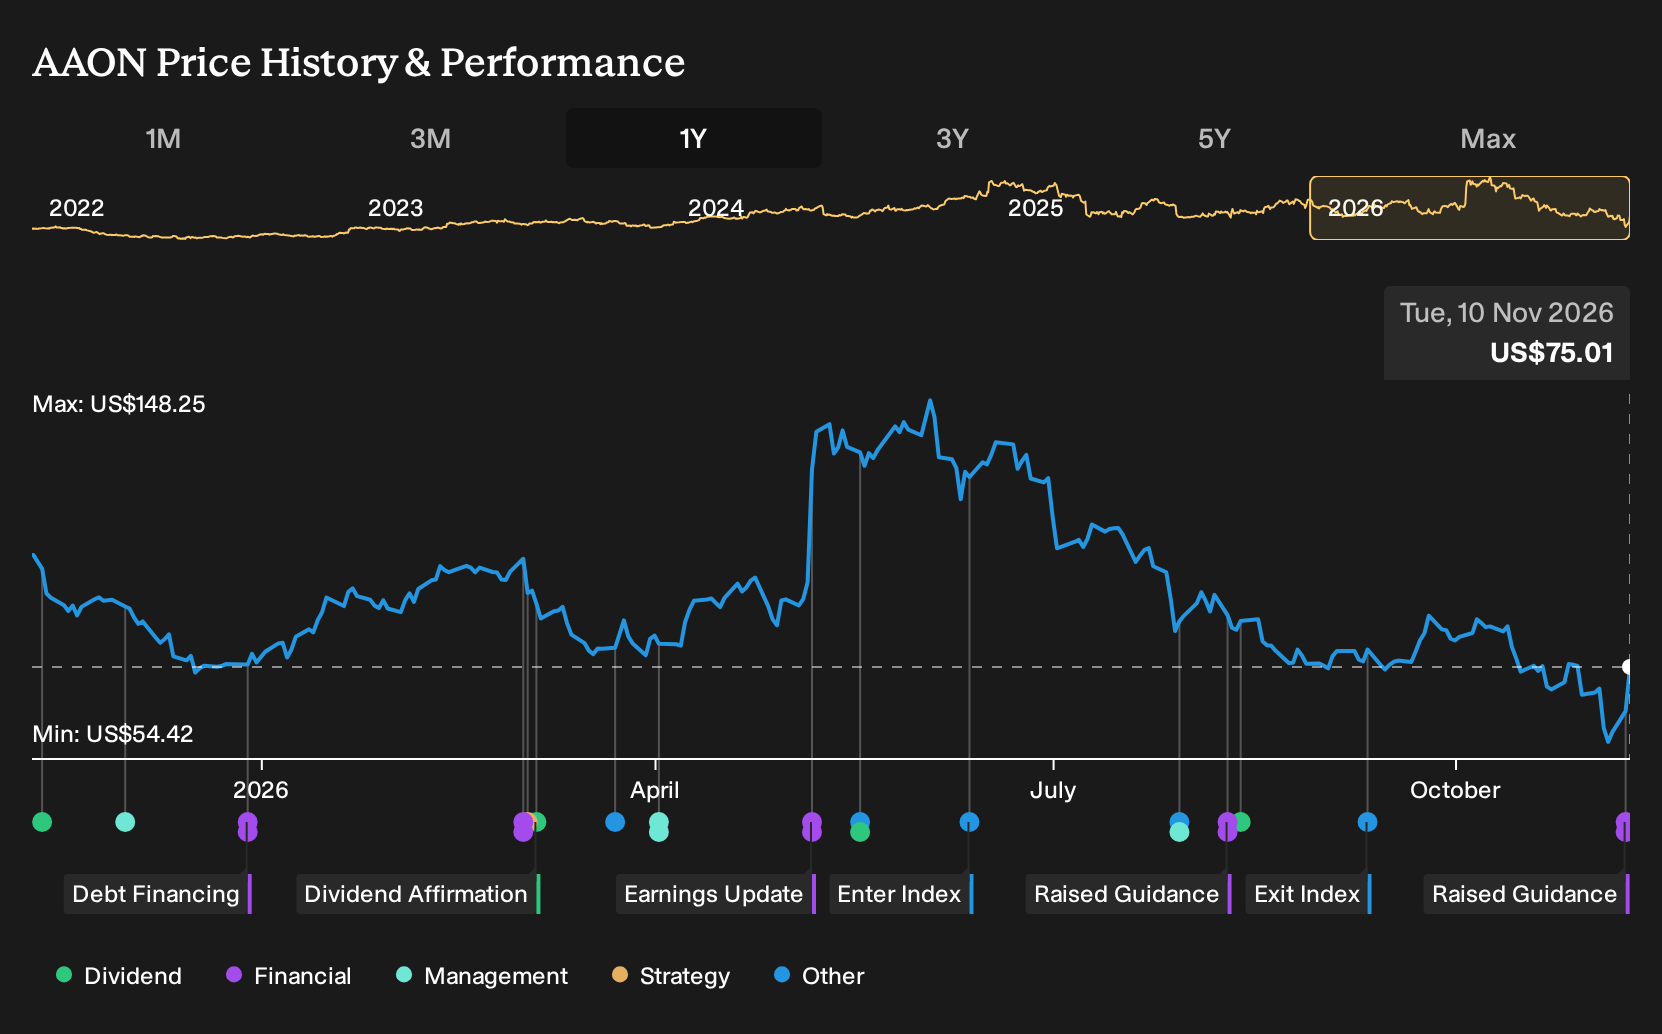
AAON operates in the US and Canadian heating and air conditioning equipment market, so any internal reporting issue or shift in sales guidance directly affects how investors assess demand tied to construction, renovation activity, and longer term building efficiency spending in this segment.
See how AAON's balance sheet measures up.
Does the material weakness change how AAON’s recent Q3 numbers are viewed?
The disclosure indicates the reporting process for early 2026 was flawed, even as Q3 2026 showed US$707.43 million in sales and US$68.96 million in net income. Restating the first half means investors need to see whether the pattern of higher revenue and earnings holds once the corrected figures are in place.
Does this conflict with the existing AAON Narrative?
The Narrative emphasizes AAON converting BASX driven data center demand and heavy capex into cleaner margins and stronger free cash flow over time. A control weakness and restatements do not directly alter that operational thesis, but they do raise questions about how clearly investors can track the margin pressure already flagged in earlier quarters.
See how these catalysts shape AAON's path to a $128 fair value.
What should AAON investors watch next to judge the impact?
The key checkpoint is the restated Q1 and Q2 2026 financials and any follow up commentary in AAON’s next earnings report or filings. Readers will be looking for clear remediation steps on internal controls, full detail on how the corrections affected sales and EPS, and whether the higher 2026 sales outlook is reaffirmed.
One more AAON question that goes straight to what the business may be worth
There is a valuation view built purely from AAON's cash generation that can be lined up against the current share price, and the gap between those two can be meaningful for long term holders. Find out exactly what AAON is worth today based on its cash flows.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com