


The Morning Bull - UK Market Morning Update Wednesday, 11 Nov 2026
UK markets are set for a slightly upbeat open, with sentiment leaning constructive. The main driver is stronger than expected domestic retail activity heading into the key festive trading period.
UK retail sales in October rose 1.5% year on year, with like for like spending up 1.1%. Card data support that picture, as Barclays reported a 2.3% annual increase in spending, pointing to consumers still willing to open their wallets.
Healthier tills matter because they support revenue expectations for consumer facing businesses, which can ease some concerns about earnings pressure from higher household bills. Stronger demand also gives companies a little more ability to pass through cost increases without immediately losing volume.
The unresolved question is how long this spending resilience can last while consumer confidence stays weak. Attention now shifts to tomorrow’s UK GDP figures, which will test whether robust shopfloor activity aligns with broader economic momentum.
Stocks to Watch Before the Opening Bell
Ferrexpo (FXPO)
Production at Ferrexpo is temporarily halted after attacks on Ukraine’s power grid disrupted electricity supplies to its sites. The facilities themselves were not damaged, but unstable energy provision has paused normal output.
Investors will be watching how long the stoppage lasts, any update on export volumes, and whether the company provides fresh guidance on costs and capital spending.
Funding Circle Holdings (FCH)
Funding Circle Holdings has raised full year profit guidance again, now targeting at least £44 million of pre tax earnings. That is about 5% above previous consensus, with revenue expectations lifted to at least £275 million from more than £255 million.
The group is pointing to resilient SME demand and a profit margin of around 16%. Watch for any commentary on credit quality and loan losses.
Avon Technologies (AVON)
Avon Technologies reported a 50.6% increase in adjusted operating profit to US$60.7 million for the year to 30 September 2026, supported by 12.7% revenue growth to US$353.7 million and record filter volumes. The adjusted operating margin reached 17.2%, already ahead of the firm’s medium term ambition.
Guidance for 2027 highlights mid single digit revenue growth, free cash flow of US$50 million to US$60 million, and a 16% to 18% margin range.
Top Movers
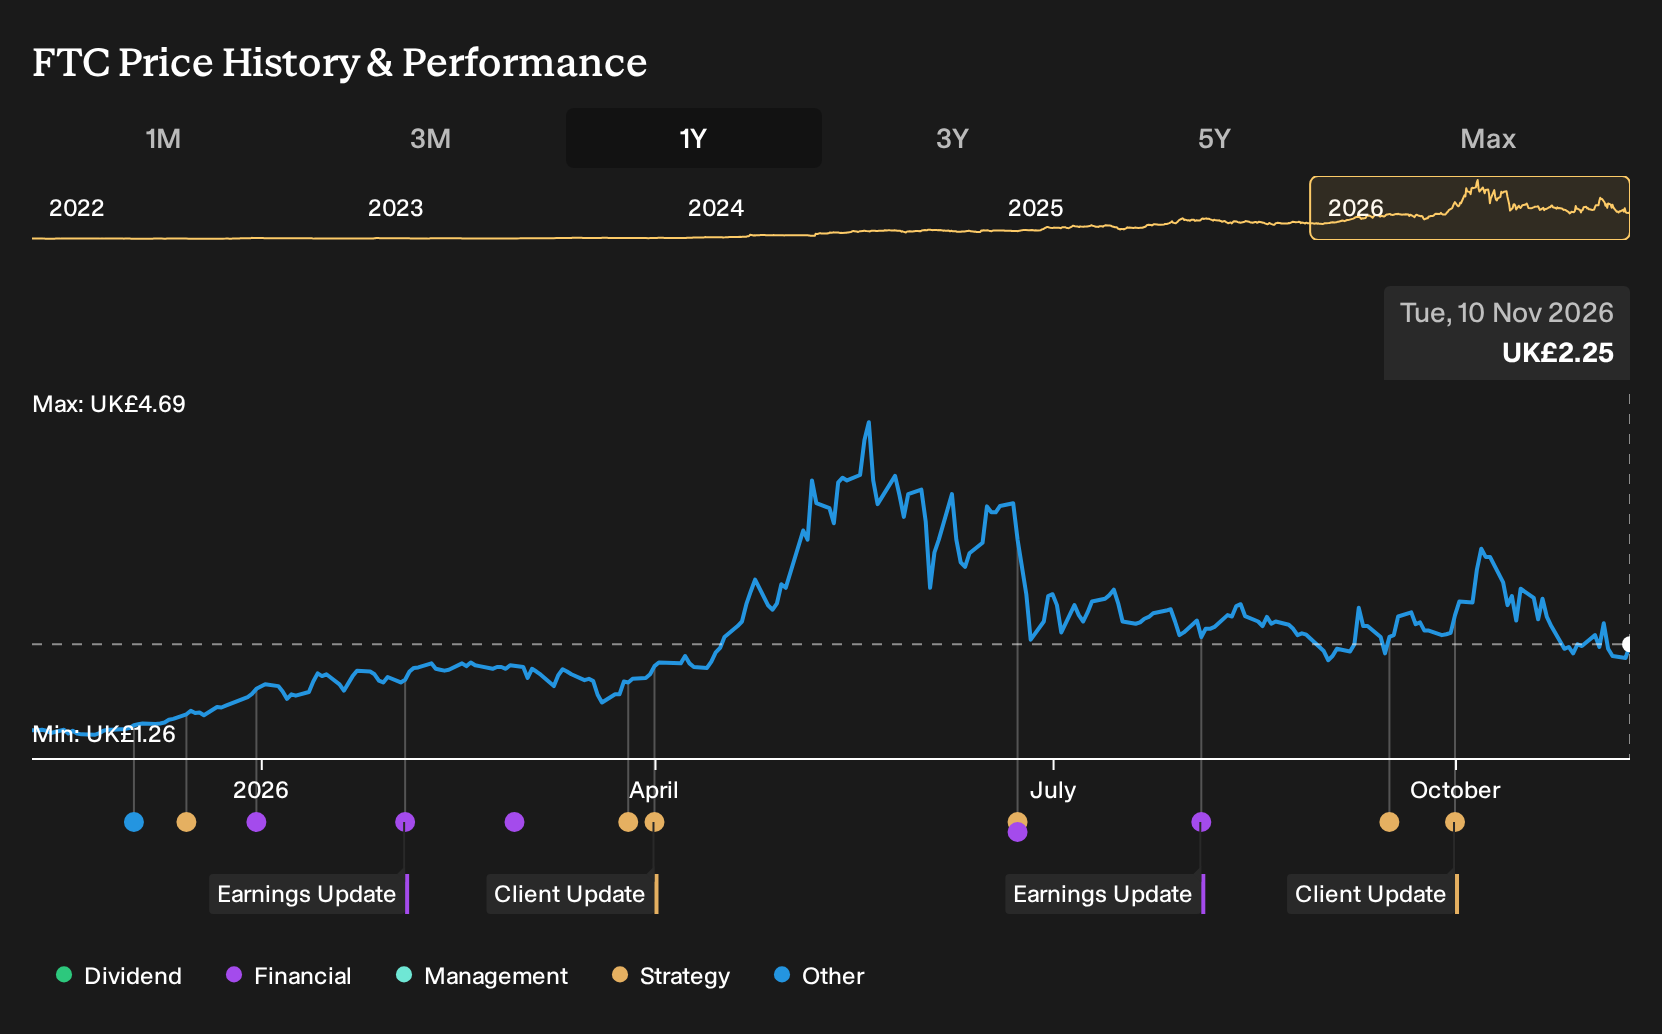
- Filtronic (AIM:FTC) surged 7.14%.
- TBC Bank Group (LSE:TBCG) gained 3.19% after quarterly earnings showed higher net income and earnings per share.
- J D Wetherspoon (LSE:JDW) advanced 2.92% after Jefferies lifted its price target following the latest fiscal Q1 update.
Top Losers
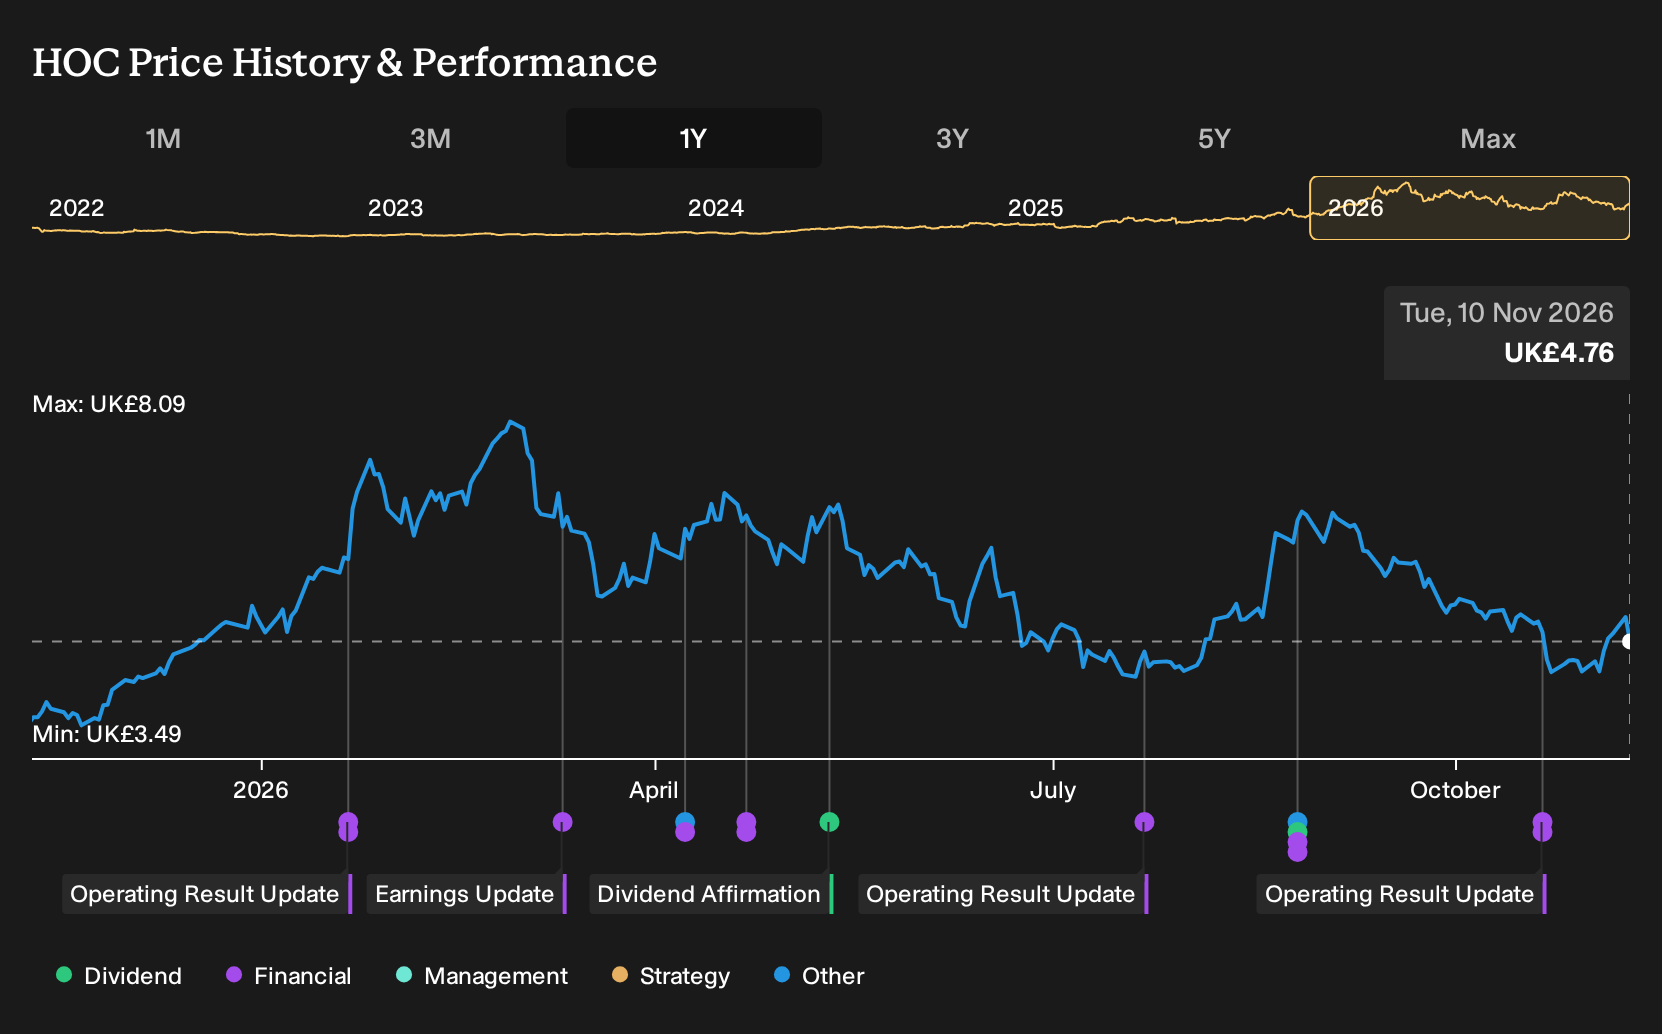
- Hochschild Mining (LSE:HOC) declined 7.17%.
- MHP (LSE:MHPC) declined 7.17%.
- Oxford Nanopore Technologies (LSE:ONT) declined 4.47%.
On The Radar
UK macro data and a run of London listed earnings over the next two days give you a tight read on growth, inflation and how listed companies are handling consumer demand.
- UK Q3 GDP releases Thu 12 Nov. The quarterly figure has a previous reading of 0.5% and a consensus of 0.7%. A result above consensus would point to firmer growth and could support expectations for stickier borrowing costs and a firmer pound.
- UK September activity data and trade Thu 12 Nov. Monthly GDP has a previous value of 0.1% and a 0% consensus, while the goods trade deficit is forecast at £18.7b. Stronger output or a narrower gap would tend to help domestically focused cyclicals.
- UK industrial and manufacturing production Thu 12 Nov. Industrial output previously rose 0.8% month on month with a consensus for a 0.4% decline, and manufacturing was up 1.2% with an expected 0.5% fall. Any resilience would matter for industrials and exporters on the FTSE.
- Cluster of UK earnings including B&M European Value Retail, Burberry Group, 3i Group and others Thu 12 Nov. First half and interim numbers across value retail, luxury, private equity and consumer brands will show how different parts of UK quoted retail and consumer finance are converting recently firm shop spending into revenue and margins.
- UK labour market data and wages Tue 17 Nov. Unemployment previously stood at 4.7% with a forecast of 4.9%, while average earnings growth was 3.7%. Any upside surprise on pay would keep pressure on inflation and rate expectations, which affects rate sensitive sectors.
Sector & Industry Watch
Consumer Discretionary: Festive spend keeps recovery alive
Fresh UK retail sales data showing October spending up 1.5% year on year, with card use also higher, helps Consumer Discretionary extend its recent 30 day and 7 day improvement after a flat year. That kind of resilience matters for anything linked to holidays, eating out and bigger ticket purchases.
The single swing factor now is Thursday’s UK Q3 GDP release, which will quickly influence how confident investors feel about UK focused retailers and leisure groups.
Airlines: Strong week as travel theme builds
Airlines have enjoyed a powerful 7 day gain on top of already firm 12 month progress, helped by steady sector interest and ongoing brand investment in premium hotels from groups such as IHG. Ownership changes at easyJet underline that larger investors remain active in the space, which can amplify day to day price moves.
The number to watch is again UK Q3 GDP on Thursday, since a weaker growth print could make markets question how long business and leisure travel can stay this buoyant.
Energy and Oil and Gas: Pullback continues as oil cools
Energy and Oil and Gas are down over the last week and over 30 days, even though year to date and 12 month returns are still positive. Softer crude prices and headlines around BP reshaping some activities, together with more muted progress at DCC Energy, keep attention on how closely profits track the commodity tape and regulatory decisions.
For near term direction, US crude inventory data on Thursday evening matters most because any sharp stock build or draw can reset revenue expectations for UK listed producers in a single session.
Metals and Mining: Rebound meets project and funding questions
Metals and Mining have moved higher over the past 7 days after a weaker month, with the industry up around 3% and still ahead over 12 months. Support from firmer commodity pricing combines with mixed company headlines, including Ferrexpo’s power related production halt in Ukraine plus funding reviews at Zanaga Iron Ore, Pensana and Bradda Head Lithium.
Thursday’s UK industrial and manufacturing production reports are the key checks, since factory output data help investors judge whether real economy demand is keeping up with the stronger price signals miners currently reflect.
Telecom: Earnings upgrades but shares tread water
Telecom performance has been broadly flat over the past week and month, despite solid 12 month gains and upgrades to earnings guidance at several groups. Vodafone lifting revenue and cash flow targets, Aeorema raising profit expectations and BT pausing its Starlink launch together paint a picture of stable cash generation with some operational questions still in play.
The next macro cue is Tuesday’s UK labour market and wages data, because any change in pay growth or employment can directly affect how comfortable households feel about monthly phone and broadband bills that underpin sector income.
Find Stocks Poised To Move
If resilient October retail spending is the part of today’s update that matters most to you, start with this list of list of solid balance sheet and fundamentals (194 results)
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com