


Hotter than expected US inflation data has pushed bond markets around and kept interest rate expectations in focus, which tends to reward companies that generate real cash today rather than distant promises. That is where Canadian stocks with solid cash flows but discounted valuations come in. This article highlights three candidates from a cash flow focused value screen that could appeal if you are hunting for mispriced resilience.
The three stocks highlighted below are only a starting sample, as the full cash flow focused value screen surfaced 4 more companies with equally compelling stories that are not covered in this article.
If you want to identify potential mispricings and analyze which names best fit your own return and risk criteria, head straight into the Undervalued Stocks Based On Cash Flows screener
Stantec (TSX:STN)
Stantec is a global design and engineering group that earns a large share of its value from long term water and infrastructure work, where contract based projects help underpin cash flow. The business generated about CA$3.6b from the United States, CA$1.7b from global operations and CA$1.6b from Canada, and the stock is valued around CA$12.1b.
The analyst consensus Narrative on Simply Wall St describes Stantec as a cash generative infrastructure and water focused platform where the market may not fully reflect the scale or duration of its project backlog.
Recent large acquisitions such as Page, Cosgroves and Ryan Hanley have significantly expanded Stantec's presence in the U.S., New Zealand and Ireland. With Page reported as performing strongly, and with Niche in Australia added in mid 2026, the larger platform may continue to widen the revenue base and deliver the integration benefits described by analysts.
What happens to Stantec’s valuation if a single assumption about how efficiently those projects convert into margins and free cash proves too cautious?
If that margin conversion angle matters to your thesis, the full narrative for Stantec outlines how cash generation, valuation and project risk could be decoupling.

Barrick Mining (TSX:ABX)
Barrick Mining is a diversified miner focused on gold and copper deposits that generate long lived production and the cash flows used in discounted cash flow models, with the Toronto based group valued at about CA$97.3b.
Barrick Mining appeals to this cash flow focused screen because its long life mines produce sizeable, recurring cash streams that the market is currently pricing at a discount according to the analyst consensus Narrative on Simply Wall St.
Agreement with Newmont to restructure the Nevada Gold Mines joint venture, including bringing Fourmile and Newmont’s Mike and Fiberline assets into the JV and resolving historic disputes, is expected to let Barrick Mining reconfigure processing capacity, reduce ore trucking and pursue higher throughput in Nevada, which would directly affect group revenue and unit cash costs.
The real swing factor is how that new operating setup filters through to sustained unit costs if one key execution assumption proves too hopeful.
If that cost curve is the real hinge, the full narrative for Barrick Mining illustrates how execution risk, copper exposure and cash flow resilience could be getting misread by the market.
DPM Metals (TSX:DPM)
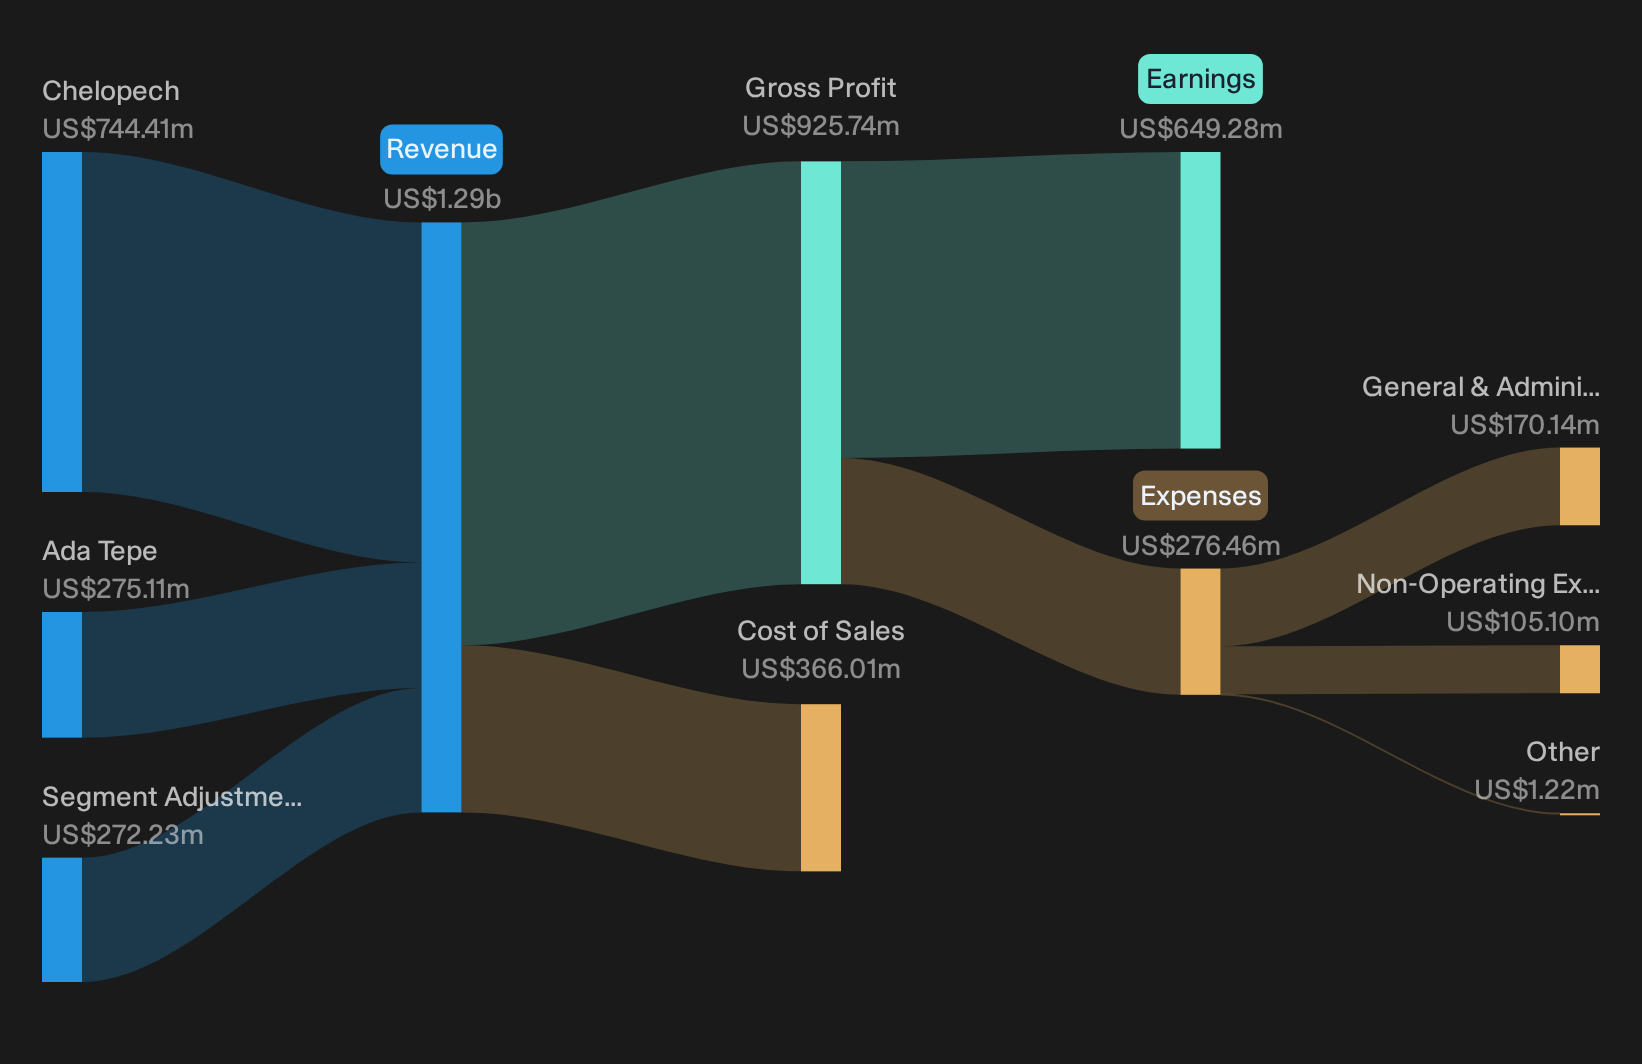
DPM Metals is a Toronto based precious metals producer. Its gold focused mining and processing operations in Bulgaria, Bosnia and Herzegovina, Serbia and Ecuador generate the free cash flows used in SWS DCF work, with Ada Tepe contributing about $275 million and Chelopech around $744 million toward a roughly CA$13.2b market value.
The bullish analyst Narrative on Simply Wall St argues that one operating shift could be central to how investors value DPM Metals’ future cash generation.
Completion of Vareš ramp up to the targeted 850,000 tonnes per year together with reported all in sustaining costs at that mine that are below the group average creates scope for DPM Metals to blend a higher share of lower cost ounces into the portfolio, which could support group level net margins.
What happens to DPM Metals’ cash flow appeal if a single unseen cost pressure changes how much of those margins actually reach shareholders?
If that unseen pressure is what keeps you on the sidelines, the full narrative for DPM Metals shows how those costs, mine mix and cash generation could be quietly accelerating.
Seeking Alternatives Before The Crowd Moves
Fresh ideas move first. Breakout trends, new momentum and falling valuations often get caught by early screens while it still matters and before attention flies elsewhere, so consider your options promptly.
- Spot high quality cash generators before momentum builds by scanning the 5 high quality undervalued stocks while these candidates are still under the radar for now.
- Target resilient payout streams by reviewing the 3 dividend fortresses and see which high yielders still look built to handle pressure.
- Follow the next wave of automation by tracking 91 robotics and automation stocks and identify potential beneficiaries before the story fully reaches the wider market.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com