


Axos Financial has delivered a strong multi year share price run, so the immediate question for anyone looking at the stock today is whether that move still lines up with what its earnings can justify. Recent trading has been choppy, which puts even more focus on what the profit line actually supports at the current valuation.
- Over the past 3 years, Axos Financial has returned about 137.3%, which raises the obvious question of how much of that climb is backed by sustainable earnings power.
- The latest results showed higher net income and earnings per share alongside expectations for faster loan growth, which can influence how investors think about the durability and timing of future profits that underpin valuation multiples.
- The analysts covering Axos Financial have run their own numbers. See what analysts think Axos Financial's shares could be worth.
The issue now is whether Axos Financial's current share price of US$92.17 is adequately explained by the earnings the business is generating today.
If you want to test the same earnings backed valuation question beyond Axos Financial, compare it with other companies using 35 high quality undervalued stocks
Is Axos Financial Still Cheap on Earnings?
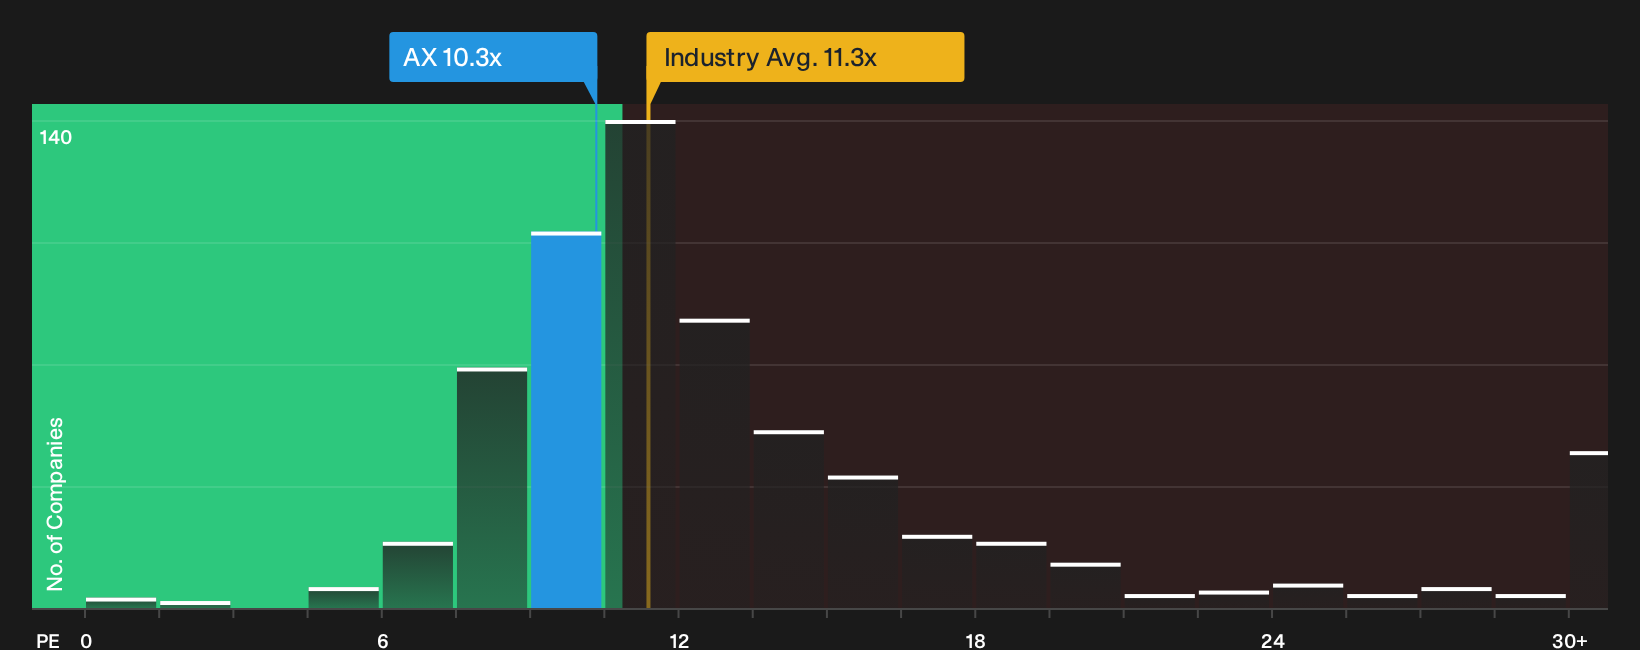
The P/E ratio is a useful yardstick for Axos Financial because earnings are a central driver of how investors value banks. On this measure, the stock trades on about 10.3x earnings, which is below both the wider Banks sector on roughly 11.3x and the peer group average near 14.2x. That places Axos Financial at a discount to many listed lenders on headline earnings.
The Fair Ratio model, which builds in factors such as expected profitability, balance sheet intensity and risk, points to a higher multiple than the one the share price currently reflects, so the stock screens as undervalued on this framework. Because the latest quarterly update in September 2026 showed net income and earnings per share at current levels, the gap between Axos Financial’s earnings power and its lower P/E suggests investors are still pricing the bank more cautiously than those benchmarks imply. Explore the numbers behind Axos Financial's P/E valuation.
The Axos Financial Narrative: What Would Justify Today's Price?
Narratives for Axos Financial pick up where the P/E question leaves off and spell out what kind of future for growth, margins and earnings would need to play out for the current share price to look high, low or roughly fair. Each scenario focuses on the assumptions that sit behind its view of fair value, so you can line those up against Axos Financial's actual results as they are reported.
One of the top narratives on Axos Financial: 22% undervalued
This Narrative is the analyst consensus Narrative on Simply Wall St, which compiles analysts' consensus price target and revenue and earnings forecasts, not one person's view.
"The main thing that has to go right is that Axos Financial continues to grow specialty lending and equipment finance volumes, while keeping credit losses contained..."
Discover why this Narrative puts Axos Financial at 22% undervalued.
Before acting on Axos Financial’s valuation, one more piece of the puzzle matters
Price and earnings only tell part of the story, because the people steering Axos Financial and the way their pay is structured can strongly shape how the business is run over time. See who runs Axos Financial and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com